


Repulse and DPO - 4H OnlyLong-Strategy on Dax
Hello
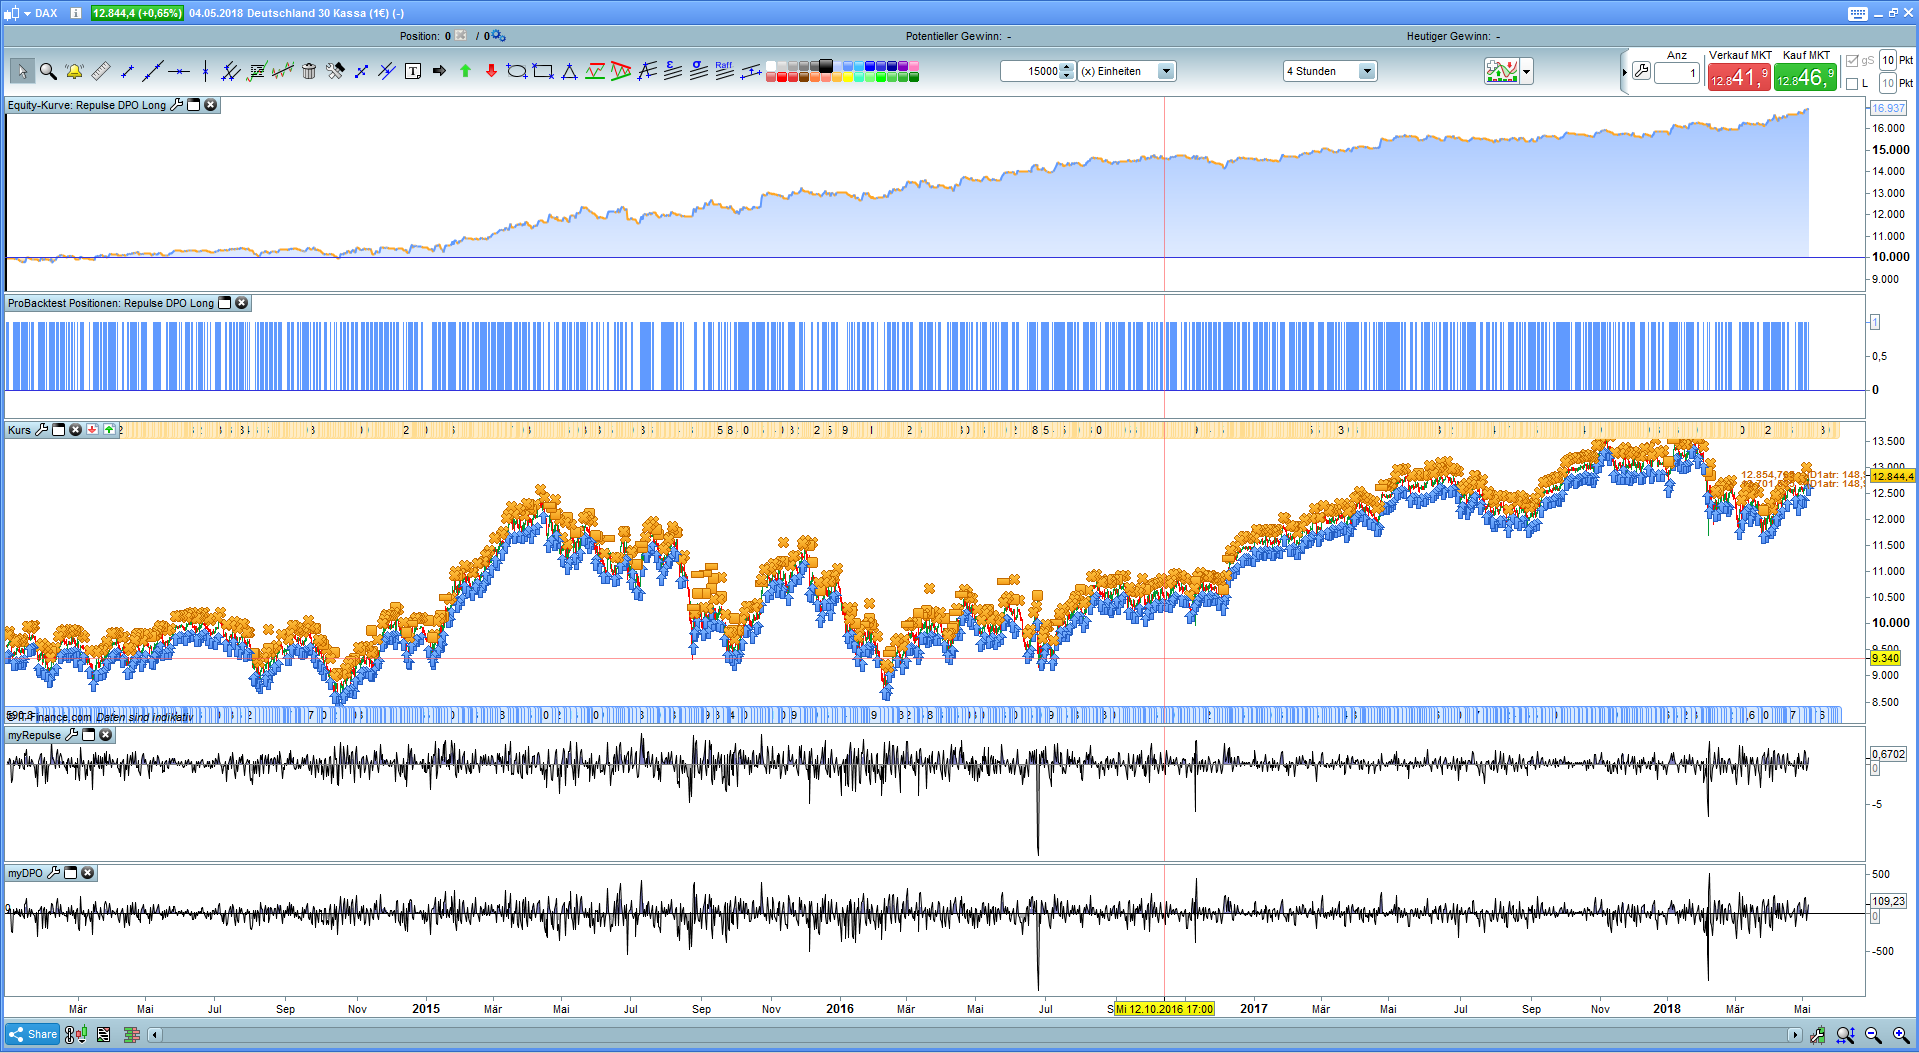
This is a small OnlyLongstrategy with quite acceptable results.
The Detrended Price Oscillator and the power of the candles with the Repulse Indicator are used.
If both > 0.1 we buy a position, if one of the two indicators Short < 0.1 we sold. Buying and selling is quite convenient at the usual times in the Dax at 09.00 / 13.00 / 17.00 and 21.00 hours (utc+2 “Berlin-time”). Who likes can protect the losses and profits in percent and not only via the indicators.
Like all trend-following systems, it has weaknesses in sudden trend changes and range phases, but this strategy still achieves a better result than the Dax itself.
kind regards
JohnScher
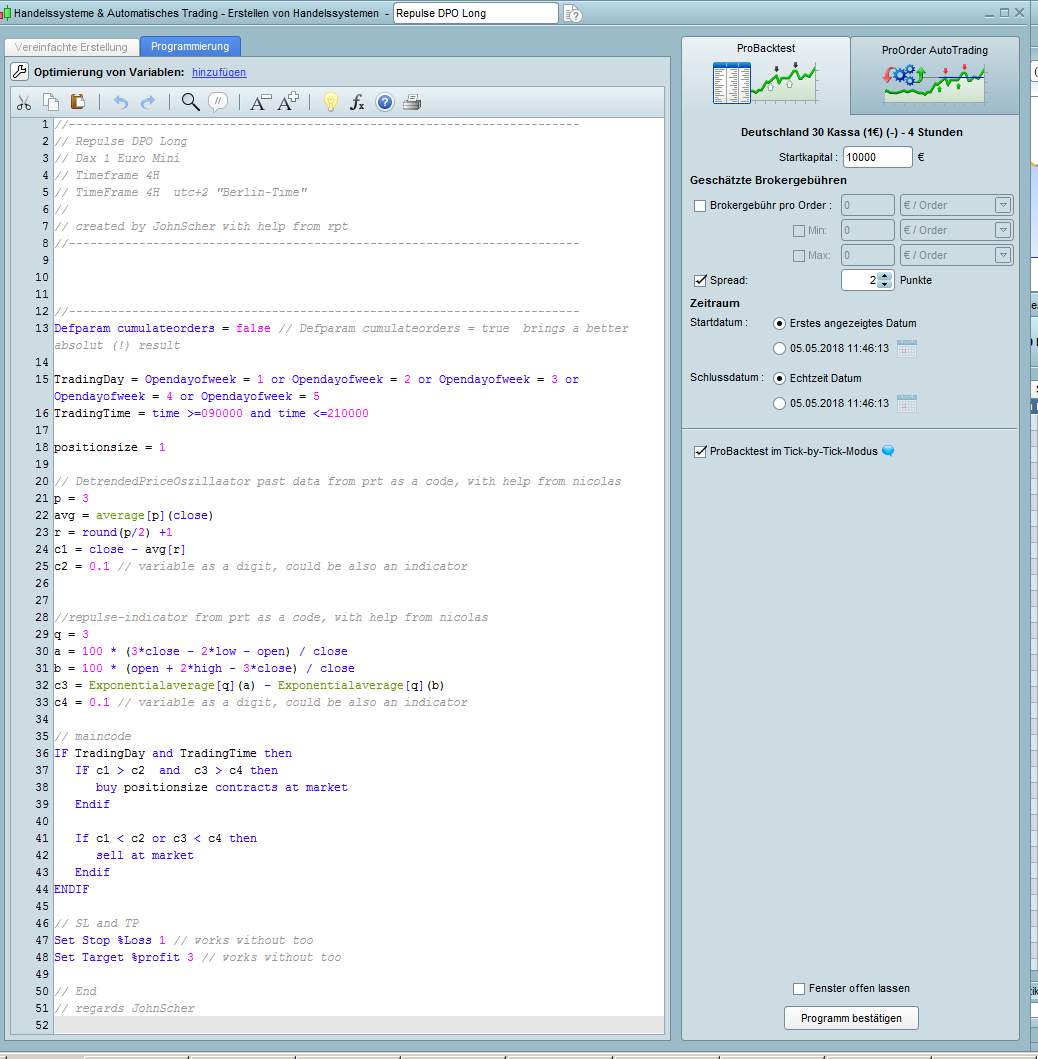
//-------------------------------------------------------------------------
// Repulse DPO Long
// Dax 1 Euro Mini
// Timeframe 4H
// TimeFrame 4H  utc+2 "Berlin-Time"
//
// created by JohnScher with help from rpt
//-------------------------------------------------------------------------


//-------------------------------------------------------------------------
Defparam cumulateorders = false // Defparam cumulateorders = true  brings a better absolut (!) result

TradingDay = Opendayofweek = 1 or Opendayofweek = 2 or Opendayofweek = 3 or Opendayofweek = 4 or Opendayofweek = 5
TradingTime = time >=090000 and time <=210000

positionsize = 1

// DetrendedPriceOszillaator past data from prt as a code, with help from nicolas
p = 3
avg = average[p](close)
r = round(p/2) +1
c1 = close - avg[r]
c2 = 0.1 // variable as a digit, could be also an indicator


//repulse-indicator from prt as a code, with help from nicolas
q = 3
a = 100 * (3*close - 2*low - open) / close
b = 100 * (open + 2*high - 3*close) / close
c3 = Exponentialaverage[q](a) - Exponentialaverage[q](b)
c4 = 0.1 // variable as a digit, could be also an indicator

// maincode
IF TradingDay and TradingTime then

If c1 > c2  and  c3 > c4 then
buy positionsize contracts at market
Endif

If c1 < c2 or c3 < c4 then
sell at market
Endif

ENDIF

// SL and TP
Set Stop %Loss 1 // works without too
Set Target %profit 3 // works without too

// End
// regards JohnScher
Comments
You must be logged in to post a comment.
Hello. I have updated the code littel bit. On the one hand I switched to GMT+1. On the other hand, I optimized the entries and exits using the Optimazingtool via the Repulse, thus slightly improving the result in the backtest. In the attachment the itf.ile. If there are problems with the download and/or opening, here is the code again //------------------------------------------------------------------------- // maincode : Dax Only Long by Repulse and DPO // timezone GMT+1 new !! // timframe 4H // Spread 2 // created by JohnScher //------------------------------------------------------------------------- Defparam cumulateorders = false TradingDay = Opendayofweek = 1 or Opendayofweek = 2 or Opendayofweek = 3 or Opendayofweek = 4 or Opendayofweek = 5 TradingTime = time >=080000 and time 0.01 and Repulse [3] >= 0.21 then // new ... 0.0 before buy position contracts at market Endif If Repulse [3] <-0.17 then // new .. 0.0 before sell at market Endif Endif Set Stop %Loss 5 // stays !! //Set Target %profit 3
Is this trading system expected overnight? or is it my problem? I see long at 21 hours, which are closed the next day
Sorry John I have no time.
Sorry John, I do not have much time to. But tested on lesser timefrom for 1hr and 4hr blocks beginning at session open likely a good starting point.
Perhaps the answer is just take Longs above the 4Hourly openprice and Short below the 4Hourly open .
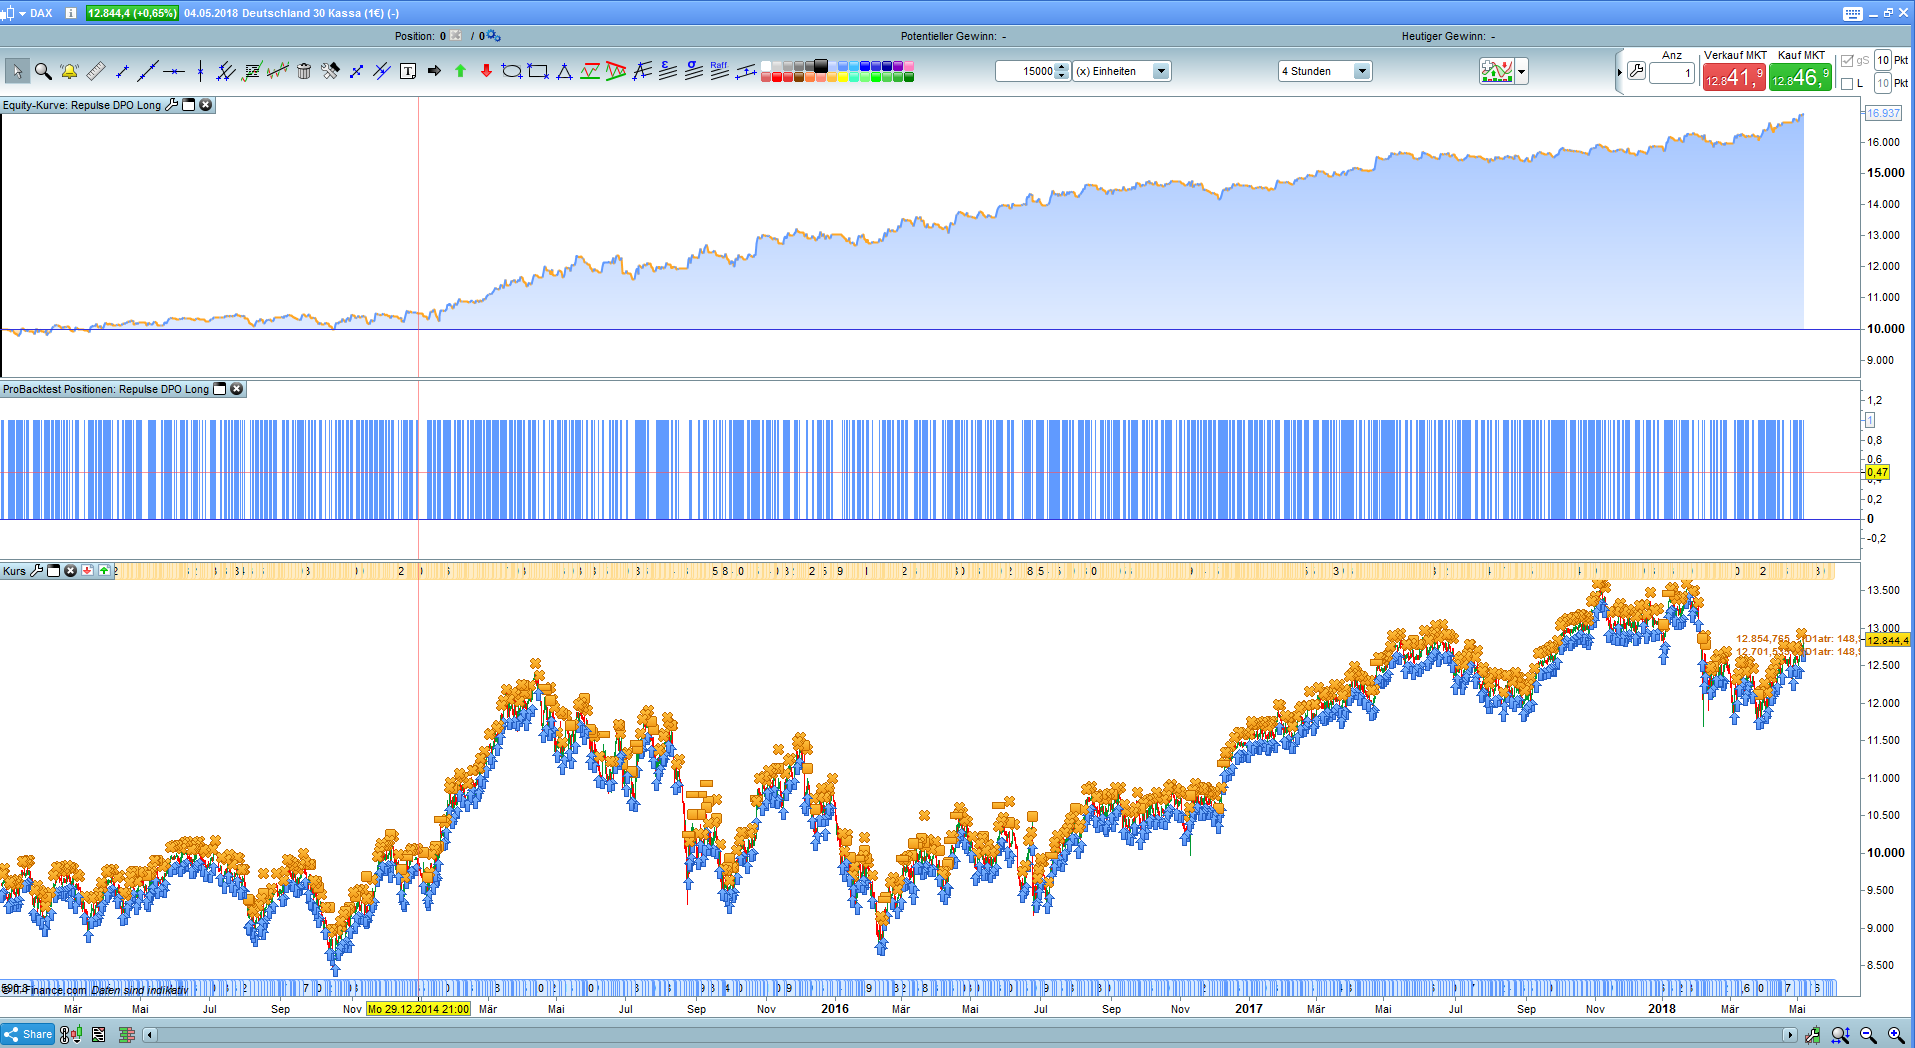
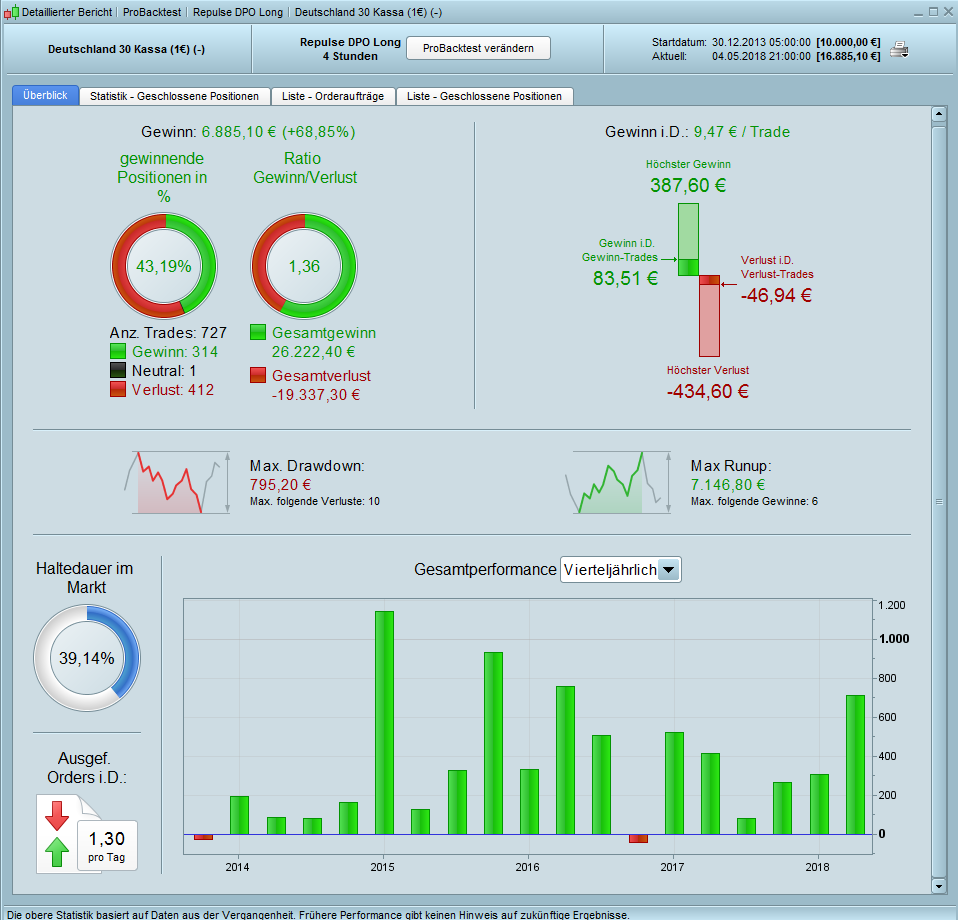
Dear John, nice strategy, with 1.7 pips average spread and optimising p and q to respectively 3 and 7 outperformes indeed the DAX, it gives a profit of 6.093 Euro over a period from January 2014 to May 2018, with an In Sample result of 4.705 Euro (first 68% of the bars) and Out of Sample 1,388 Euro (remaining 32% of the bars), the Out of Sample result is 62% which sounds relative good. Also good to know is that with this strategy you are only less then 40 % in the market ! Maybe also good to mention that the first 11 months, from January 2014 to December 2014, profits are ZERO, which is annoying and it would be hard to maintain the strategy if the simulation would have been true during that year !
I did not come up with the baking test results, they were supplied by PRT. I didn't go through a change from p and q to 3 or 7. And times I'm not on the market I haven't checked either, but I'll make up for that. Currently I also have the strategy programmed by someone in MT4 to get a separate backtest. Depending on the result of the backtest from MT4, I then go live on air "Who beats the Dax?
Perhaps the answer is just be long above Hourly open and Short below hourly open.
This is dangerous as it doesn’t consider a 50-100 pip swing before the bar close direction.
Hi JohnSher, Nice but not the same result Do you have the last itf of it ? Good result in production ? or it was just a test in demo account ?