






EURUSD Mini overnight trading strategy 3 minutes TF
Good afternoon,
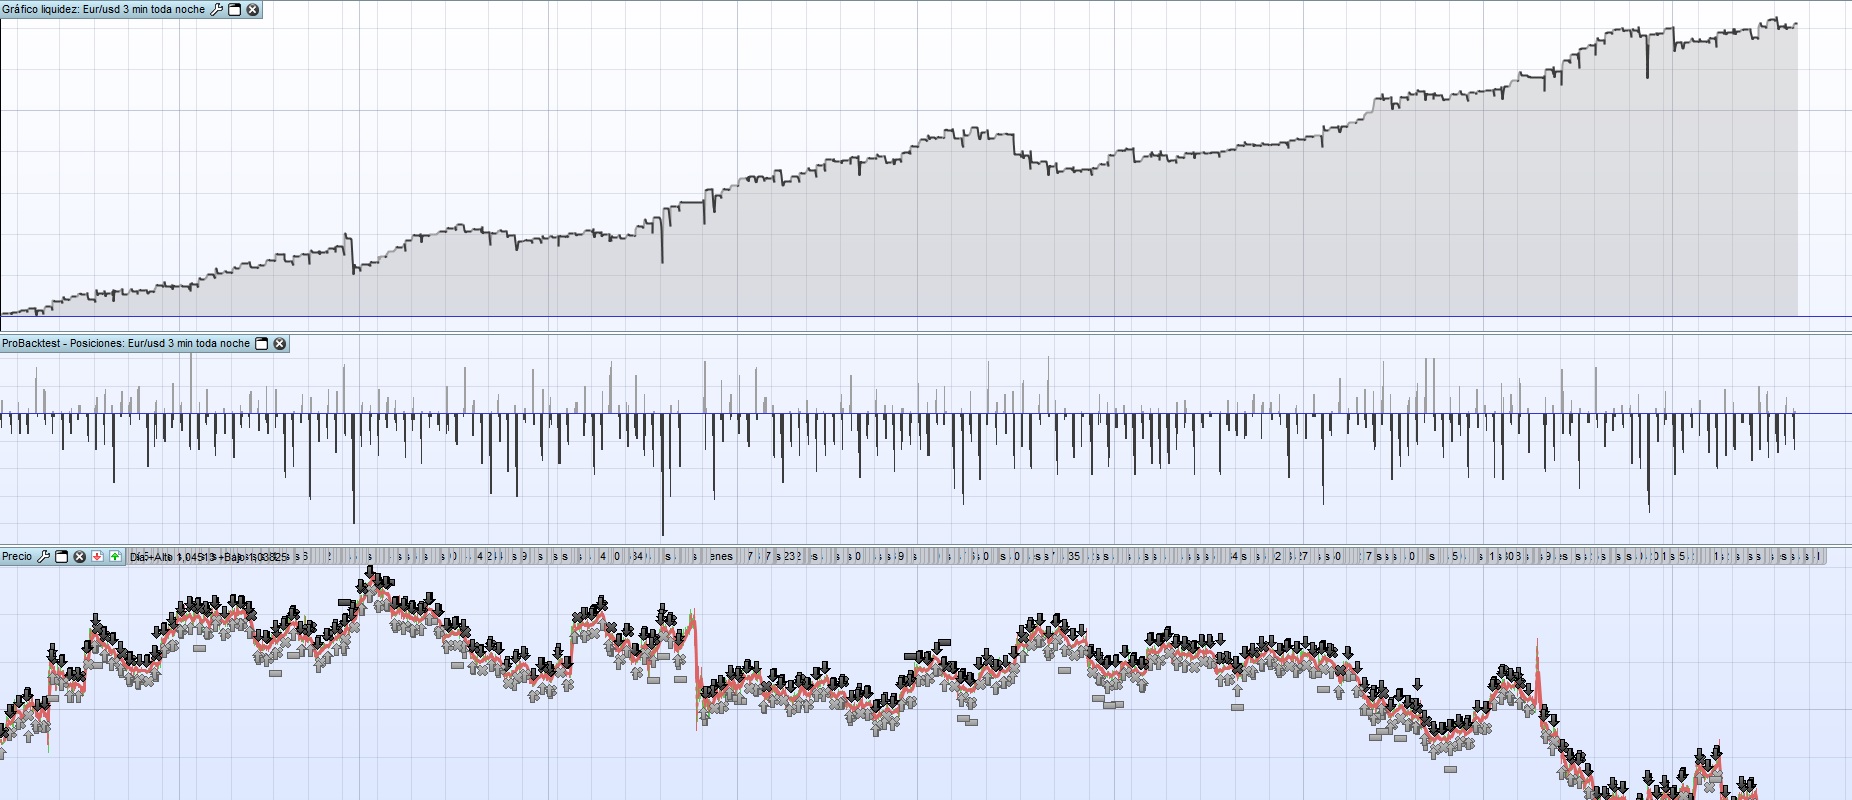
This strategy is designed for the Eur / Usd mini 1 € with a 3-minute timeframe and a spread of 0.6 pips. It only works in the evenings. Let’s see what you think and if anyone is encouraged to improve it. 😉 I have already put it with real money for a month and the backtest corresponds to what the robot does in real.
Buenas tardes,
Esta estrategia esta diseñada para el Eur/Usd mini 1€ con un timeframe de 3 minutos y un spread de 0,6 pips. Exclusivamente funciona por las noches. A ver que os parece y si alguno se anima a mejorarlo. 😉 Ya lo tengo puesto con dinero real desde hace un mes y el backtest se corresponde a lo que hace el robot en real.
DEFPARAM CumulateOrders = true // Acumulación de posiciones desactivada
DEFPARAM FlatAfter = 080300
// No se abren nuevas posiciones después de la vela que se cierra a las 5:15 p.m.
HoraEntradaLimite = 070000
// El análisis de mercado empieza en la vela de 15 minutos que cierra a las 9:30 a.m.
HoraInicio = 010000
IF ((Month = 6 AND (Day = 23 or day=24))or (month=11 and day=9)) THEN
 DiaTrading = 0
ELSE
 DiaTrading = 1
ENDIf

capital= 3000 + strategyprofit
posicion= capital/3000
if posicion>1then
 posicion=1
endif
if posicion<1then
 posicion=1
endif

if Time >= HoraInicio and time < HoraEntradaLimite and diatrading=1 then
// Condiciones para entrada de posiciones largas
 indicator1 = ExponentialAverage[35](close)-2*std[5](close)
 c1 = (close < indicator1[1])

 indicator2 = RSI[11](close)
 c2 = (indicator2 < 30)

 IF c1 AND c2 THEN
  buy posicion CONTRACT AT MARKET
 ENDIF

// Condiciones de entrada de posiciones cortas
 indicator3 = ExponentialAverage[35](close)+2*std[10](close)
 c3 = (close > indicator3[1])

 indicator4 = RSI[5](close)
 c4 = (indicator4 > 70)

 IF c3 AND c4 THEN
  sellshort posicion CONTRACT AT MARKET
 ENDIF

 atr = AverageTrueRange[49](close)
 stopus = atr*300000
 TP = atr*80000

 SET STOP pLOSS stopus
 SET TARGET pPROFIT TP
endif
Comments
You must be logged in to post a comment.

Hi jonjon. If you want to exit at the 4th bar only if the trade is losing money, you have to add following code (for exiting long):
IF POSITIONPERF<0 THEN
perd=(Barindex-Tradeindex)=3
ELSE
perd=0
ENDIF
IF LongOnMarket AND perd THEN
SELL AT MARKET
For exiting short:
IF ShortOnMarket AND perd THEN
SELLSHORT AT MARKET

Hi Raul. Just a thought, is there a way to limit the maximum number or orders that can be accumulated? This could help a little with risk? With the following:
DEFPARAM CumulateOrders = trueis it possible to limit it to a maximum to 4 accumulated orders, for example? If so do you, or anyone else, know the code as I'm being a little slow today? Thanks

Hola Raul,
gracias por compartir sistema, muy interesante. Tengo unicamente una duda sobre el spread que me parece verdaderamente muy bajo. Has probado otra combinaciòn aumentandolo? A la noche normalmente no està tan bajo.
Otra pregunta: el sistema ya està optimizado?
gracias
Giovanni
Hi jonjon, these figures are the most appropriate for the strategy. Atr is an average true range indicator, in eur / usd it has values of 0.001, so multiply by that amount. Anyway is a very risky strategy, to accumulate orders, can be all night accumulating orders without stopping and produce large losses
Hi Raul. Thanks for this code. I understand it all apart from the stop and target code. Can I ask a stupid question: where do you get the 300000 and the 80000 numbers from? I understand what the ATR is but I can't get my head around why you then multiply by these numbers. Thanks


Hola, gracias primero de todo.
Por la mañana entre 7 y 12 también fuciona.
Chao


Great code but those drawdowns is huge!
Thanks Nicolas, I'm sorry, my English is bad, I will translate it in google hehe. In the code, I have put that it does not operate the night of the brexit or of the elections of the usa,
These days better not have automatismes. In the code you can change the number of contracts as the benefits of the strategy increase, currently limited to a contract.
Thank you Raul for sharing your strategy with the community. Every code sharing is appreciated. I have successfully backtest your strategy with new backtest engine of the new PRT version, and results are accurate. I found that you use averaging down to compensate loosing orders, even if you cut all orders at the beginning of a new day, the drawdown of the money equity can be huge sometimes. Maybe you could de-leverage a bit or avoid stacking orders at each new candle if the takeprofit was not met at the first glance. This is just my own thoughts by now, will be happy to discuss more.
Hi, I would like to do a test by doing it by day, but I'm not able to change the start and end times. Someone could help me to set up for example: start time 9.30 am, late at 7 pm Thanks to who will help me