






1% per week on NASDAQ100

The approach was published by Dion Kurczek – the founder of Wealth-Lab.com – in ‘Traders 03/23’.
The trading rules
The author has investigated that Monday is a very weak day in the Nasdaq 100, while Friday is a very strong day in the week.
He therefore waits for the cash open on Monday at 3:30 p.m. and enters the market long as soon as the 3:30 p.m. open falls by one percent.
We exit the trade when the price has regained the original opening price of Monday 3.30 pm (a return to the open but only strategy).
If the price falls a further 0.5%, the take profit goes to breakeven.
Trading ends with a time stop on Friday 9.30 pm at the latest.
These simple rules have been slightly modified
the originally used daily chart was changed to a 5-minute chart
a (here arbitrarily chosen) time window in which buying is allowed was implemented
a stop of 5% has been added as insurance against major moves
Nothing else has been optimized
Optimizations can be made e.g. with regard to
the time window
for all percentages
Various indicators could be added as additional filters.
Money management that works with a trailing trailing stop after the take profit or breakeven has been reached could further improve the result.
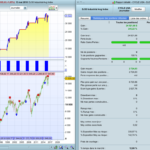
The system also runs profitably on the S&P500 here in the picture
………………………………………………………………………………………………………..
// .....................................
// 1% per week
// published by Dion Kuzczek
// here timezone europe, berlin
// timeframe 5 mins
// instrument nas100
// .....................................

defparam cumulateorders = false

If opendayofweek = 1 and time = 153000 then
Kauf = close - close/100*1
AnpassungTP = close - close/100*1.5
Endif

timec1 = (opendayofweek = 1 and time >= 153000) or (opendayofweek > 1)
timec2 = (opendayofweek < 2) or (opendayofweek = 2 and time <= 213000)

If timec1 and timec2 then
buy at Kauf limit
set target %profit 1
Endif

If longOnMarket and (close - tradePrice) =< AnpassungTP then
set target profit Kauf
Endif

If longonmarket and opendayofweek = 5 and time = 213000 then
sell at market
Endif

set stop %loss 5
Comments
You must be logged in to post a comment.

Thanks for sharing this. I've tested it over 13 years, and each year has been profitable. I conducted robustness tests by adjusting the 1% range, profit targets, stop loss, and I experimented with trailing stops. It holds up quite well across various parameter values, but the original ones seem to return solid results. One thing to consider would be to close positions on a Thursday night, but only if the trade is in profit. Otherwise, allowing it to run through to Friday as normal. This adjustment reduces the time in the market from 16% to 14%, it boosts profits by around 16%, and it doesn't seem to increase the maximum drawdown.
Thank you for this code. looks robust and can easily be improved with trailing stop and adjusted stop loss. Do you use it live?