



More from ProRealCode
ProRealCode - Trading & Coding with ProRealTime™
The ProRealTime™ community on the web! Officially sharing ProRealTime knowledge to Worldwide users since 2015!



Universal XBody Strategy on Jp Morgan Chase (1Day)
August 22, 2023, 4:55 PM
Strategies
8 Comments
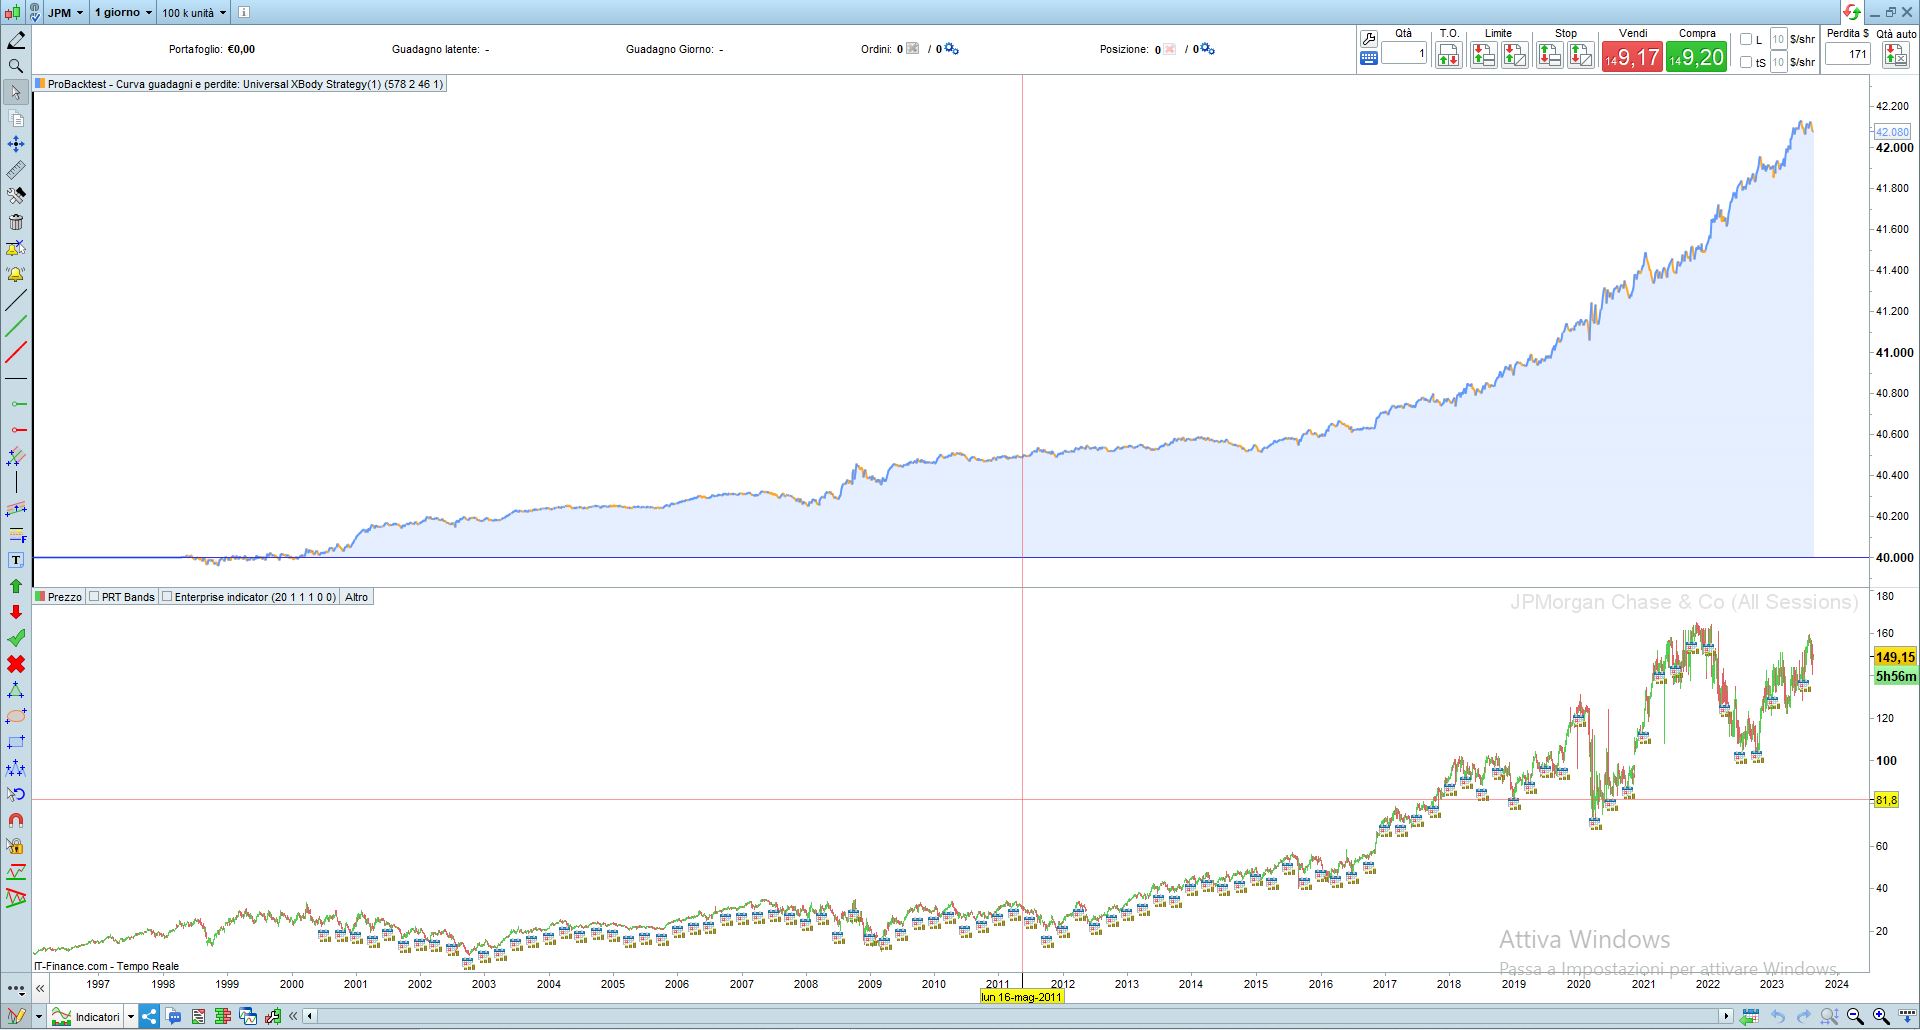
here is the same strategy (other one can be found here) with the parameters adapted to follow the movements of the shares of the famous JP Morgan Chase bank.
//-------------------------------------------------------------------------
// Codice principale : Universal XBody Strategy
//-------------------------------------------------------------------------
//Universal XBody STrategy
// instrument: Jp Morgan Chase
// timeframe : Daily
// Spread: 0.3
// created and coded by davidelaferla
//————————————————————————-
//-------------------------------------------------------------------------
defparam cumulateorders=false

//***********************************************************************************************************

//------------------ SYSTEM VARIABLES---------------------------------------
//CAC40 Values:      -------------------------------------------- Ottimization info
period=578// Optimize best value for each Symbol, range=1-1000, with step=1
mode=2// Optimize the best trading mode , range=1-4, with step=1
invertsignal=1// 1=positive signal, -1=negative signal, range=-1-1, with step=2
//***********************************************************************************************
//------------------ SYSTEM FILTER---------------------------------------
filter1=46// to set after the variable optimization, range=1-100, with step=1
filter2=1// to set after the variable optimization, range=1-100, with step=1
//------------------ INDICATOR ---------------------------------------

n=5
giorno=opendayofweek
body=close-open
var=(body-body[1])
sumvar=summation[period](var)
if sumvar>filter1*pipsize then
green=(sumvar)
endif
if sumvar<-filter2*pipsize then
red=(sumvar)
endif

if mode=1 then
c1=red<red[1]
c2=green>green[1]
endif
if mode=2 then
c1=red>red[1]
c2=green<green[1]
endif
if mode=3 then
c1=red<red[1]
c2=green<green[1]
endif
if mode=4 then
c1=red>red[1]
c2=green>green[1]
endif
if c1 then
signal=1*invertsignal
elsif c2  then
signal=-1*invertsignal
endif

// Conditions for entering long positions and exit short positions
IF signal>0 and opendayofweek<5 then
BUY n contract AT market
ENDIF
// Conditions for entering short positions and exit long positions
IF signal<0 and opendayofweek<5 THEN
SELLSHORT n CONTRACTs AT market
ENDIF
Download
Filename:
Universal-XBody-Strat-JpMorgan.itf
Downloads:
153
Average
Code artist, my biography is a blank page waiting to be scripted. Imagine a bio so awesome it hasn't been coded yet.
Author’s Profile
Similar code
Gap trading CatcherStrategies
Universal XBody Strategy on CAC (1Day)Strategies
The “Explosive Stocks” screenerScreeners
US Stocks Workspace (1920×1080)FHD 1920x1080
“Forex Reversi” indicator & strategyIndicators
Comments
You must be logged in to post a comment.


3 years ago
Hello daviddelaferla. Ok, but to optimize period and mode, filter1 and filter2 must be 0 or 1, or... ? Thank you
3 years ago
Hello YvesRobert! To optimize period and mode, filter1 and filter2 must be 0
3 years ago
Hello, how is it possible to optimized the 3 parameters (period, filter1 and filter2) at the same time because combinations number is over than 10000 ? Thank you.
3 years ago
Follow these instructions: first optimize the period and the mode (leaving invertsignal=1 ) , and then optimize filters 1 and 2

Loading...
Musiar können sie den code des automatischen systems teilen.