






"RSI-2 Strategy" from Larry Connors
Hi all !
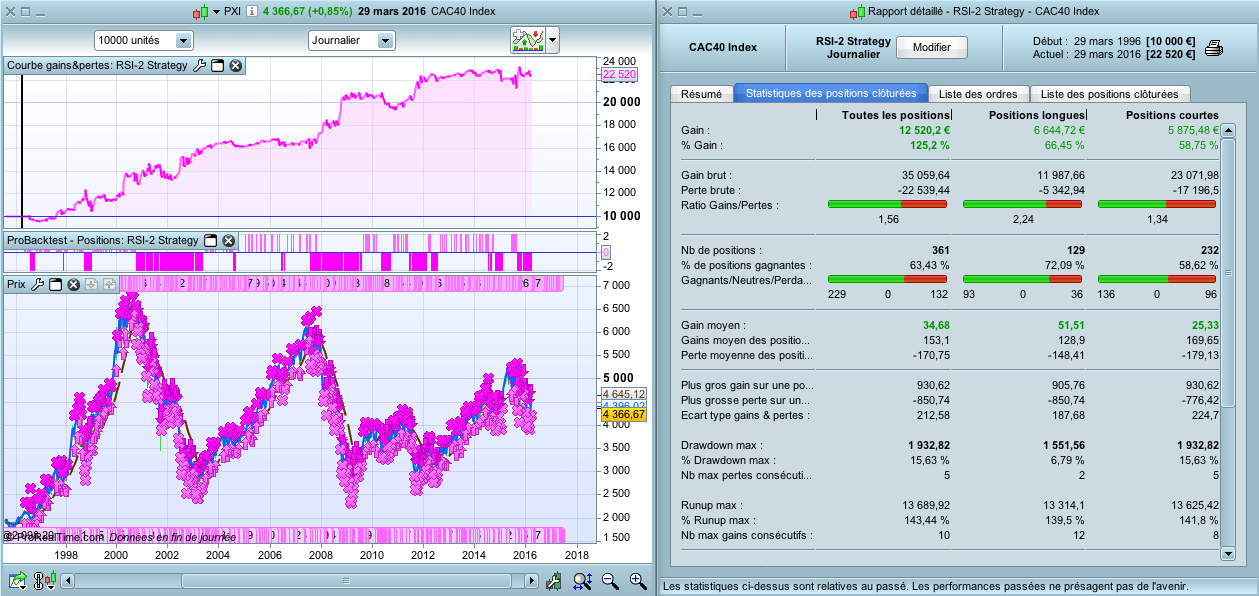
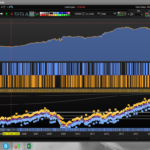
Here is the backtest that I made, from the « RSI-2 Strategy » of Larry Connors.
He’s also the co-author of the « Cumulative RSI » Strategy.
It took me 5 minutes to write the code, as the rules are very simple : no need to detail them.
Even if the strategy is positive on many stocks, indices, I don’t find it that great.
But you are free to test it and why not improve it.
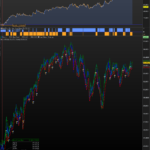
The picture shows the CAC40 for the last 20 years.
Best Regards,
DEFPARAM CumulateOrders = False

n = 2

// Conditions pour ouvrir une position acheteuse

MM200 = Average[200](close)

MM5 = Average[5](close)

RSI2 = RSI[2](close)

c1 = close > MM200

c2 = close < MM5

c3 = RSI2 < 10

IF c1 AND c2 AND c3 THEN

BUY n SHARES AT MARKET

ENDIF

// Conditions pour fermer une position acheteuse

c4 = close > MM5

IF c4 THEN

SELL AT MARKET

ENDIF

// Conditions pour ouvrir une position en vente à découvert

c1v = close < MM200

c2v = close > MM5

c3v = RSI2 > 90

IF c1v AND c2v AND c3v THEN

SELLSHORT n SHARES AT MARKET

ENDIF

// Conditions pour fermer une position en vente à découvert

c4v = close < MM5

IF c4v THEN

EXITSHORT  AT MARKET

ENDIF
Comments
You must be logged in to post a comment.
Hello,
You are right, this system isn't designed for day trading.
In my opinion, RSI with short periods work well for daily candles (there are plenty of strategies with RSI2, RSI5, etc.), but not for intraday trading, where there can happen big moves.
Here is the new picture :
http://www.doctrading.fr/wp-content/uploads/2016/03/RSI-2-strategy-n4.png
and the new backtest :
http://www.doctrading.fr/wp-content/uploads/2016/03/RSI-2-backtest-n4.png
more profitable !
Happy trading to all
My apologies to all :
with this new line, backtest show less brute gains, but far less drawdown and better profit factor (from 1,5 to >2).
Test it if you want :)
There is an error at line 41.
It should be :
c3v = RSI2 > 90On the CAC40, it gives better result with the error...
Sorry for it
Hi - the way Larry trades it does not work - discovered that over 10 years ago! BUT If you trade it using specific price formations it works super well