






The "Little Turtle" strategy
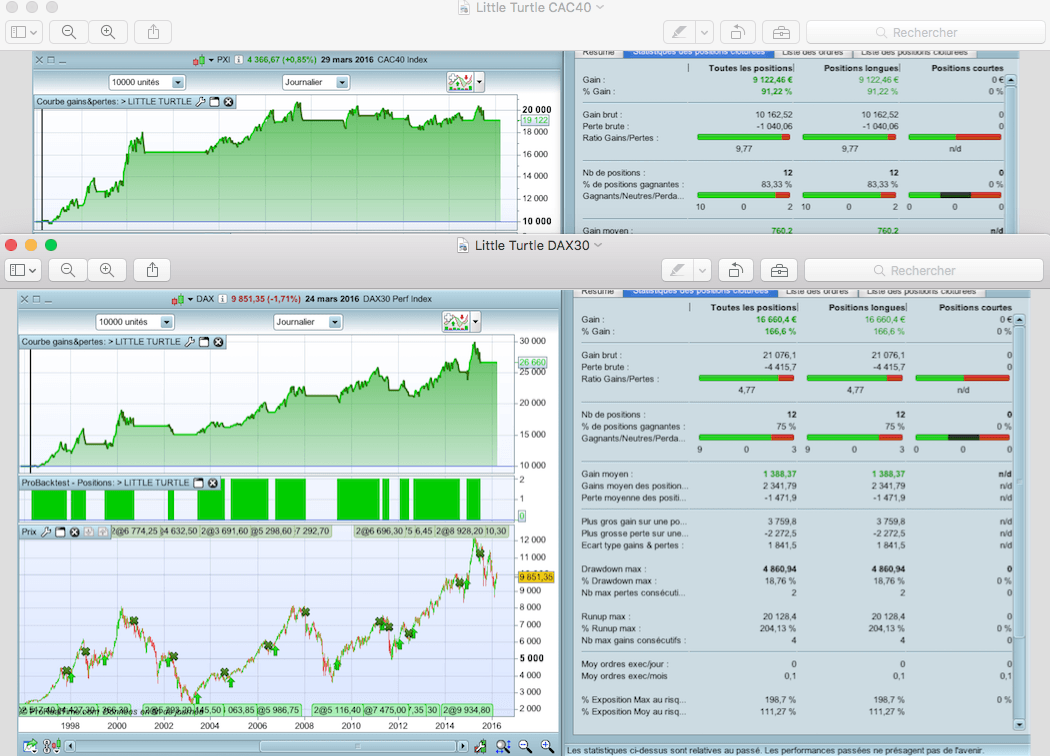
I had the idea of this little code, wishing to implement a strategy deviated from the famous “Turtle” strategy : a breakout above a last high on a certain period.
The code is very simple : we trade with the breakout of the 100 last days ; and so for the exit. Of course you can test with other parameters the value “100” days , but it seems to me profitable on most indices.
Indeed , this code is performing very well on the CAC40 (83.3 % success , profit factor of 9.7 !), The DAX30, the S&P500, even the NIKKEI, etc.
After weeks of very hard work, and with some other parameters, I did finally succeed to develop a very high-performance code on the Dax (5 times more profit than this code, with 2x less drawdown), which I use each day.
For now, I suggest you try this mini-code, which proves to be effective for long-term investment.
Defparam cumulateorders = false

n = 2

REM ACHAT
// Le + haut du jour dépasse le +haut des 100 jours précédents
ca1 = high > highest[100](high[1])
IF ca1 THEN
BUY n shares AT MARKET
ENDIF


REM SORTIE ACHAT
// Le + bas du jour dépasse le +bas des 100 jours précédents
ca2 = low < lowest[100](low[1])
IF ca2 THEN
SELL AT MARKET
ENDIF
Comments
You must be logged in to post a comment.



thank you so much for your great job, im very impatient to test your another strategy " the turtle soup +1 "
Jo
Yes, Buy & Hold is effective if the index is keeping growing... this is the case for the DAX, maybe not others...
Thanks for your reply.


Bonjour Nicolas,
Je ne comprends pas où ajouter le code que tu as a donné dans le code initial. Pouvez m'aider svp ?
Merci :)
S