






An Ichimoku Strategy
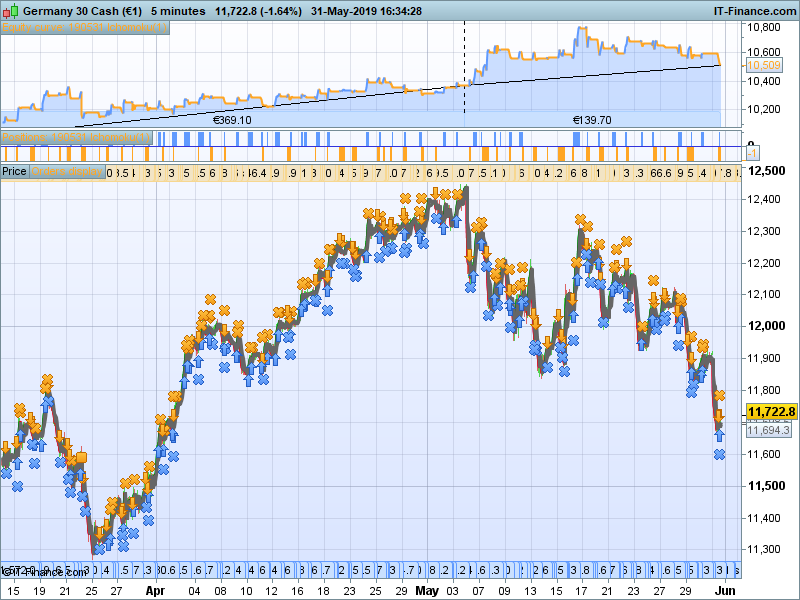
I like the trading concept of Ichimoku. (However the developed Ichimoku Strategy needs to perform better..)
The concept is explained at https://www.investopedia.com/terms/i/ichimoku-cloud.asp
Furthermore I saw some of the learning videos about Ichimoku from Karen Peloille, and an strategy https://www.prorealcode.com/topic/ichimoku-strategy/ on this platform
Searching on the internet I found a strategy fully based upon Ichimoku trading, this has been worked out in the strategy attached.
Distinguished are TenkanSen, KijunSen, Senkou Span A and Senkou Span B
- TenkanSen = (highest[S](high)+lowest[S](low))/2 //Default setting S = 9
- KijunSen = (highest[M](high)+lowest[M](low))/2 // Default setting M = 26
- SenkouSpanA = (Tenkansen[M]+Kijunsen[M])/2 //Default setting M = 26
- SenkouSpanB = (highest[L](High[M])+lowest[L](Low[M]))/2 //Default setting L =52
Trading rules can be described as follows:
Open LONG BUY conditions :
- Tenkan Sen crosses over the Kijun Sen AND
- Close is within 4 periods after the crossing above the Kumo (cloud), defined as Maximum (SenkouSpanA, SenkouSpanB)
Open SHORT SELL conditions :
- Tenkan Sen crosses under the Kijun Sen AND
- lose is within 4 periods after the crossing BELOW the Kumo (cloud), defined as the Minimum (SenkouSpanA, SenkouSpanB)
The exit in for strategy is defined for long positions as when the TenkanSen crosses under the Kijunsen, vice versa for short positions.
I added 2 additional exit methods, below described for long positions, vice versa for short positions:
- Method 2 if the close closes under the upper side of the Kumo / Cloud, based upon the SenkouSpanA
- Method 3 if close closes under the lower side of the Kumo / Cloud, based upon the SenkouSpanB
However:
The default settings 9 for TenkanSen, 26 for KijunSen and 52 for SenkouSpanB do not seen to be profitable.
Therefore I played around with the default settings as well as the exit method.
In the attached ITF file with the strategy, I have left the variables S, M, L and cm (closing method) open as variables.
A result is found for the DAX 5 minutes, see also the screenshots, based upon 10.000 bars of the DAX 5 minutes with trading hours from 7:00 AM till 22:00 PM, settings are S =7, M = 14, L = 55 and cm is 1
No good results found so far for other indices and other periods . . . . .
Probably more robust trading strategies are out there . . , hopefully it assists into further developing of good Ichimoku trading strategies.
Comments are more than welcome.
Please download the attached ITF file to get the strategy and its variables to be optimized.

Comments
You must be logged in to post a comment.

Hi guys, please could someone help with a bit of Ichimoku code that will improve performance on DJ long positions Ive added the indicator to my chart but when asked to select the indicator in the chart which Ive previously applied to price and is showing clearly it doesn't give me the option to select it from the listed indicators so not able to use basic new system coding to give me a start. Thanks in advance.


Hi Thank you for this. I have replaced the S, M, L and cm with backtested figures in preparation for automatic testing but the program still requests me to replace the backtested variables. Not sure how to get this right. I am a prorealtime newbie. Perhaps I could export the code for you to show me where I am going wrong. Kind Regards Allan

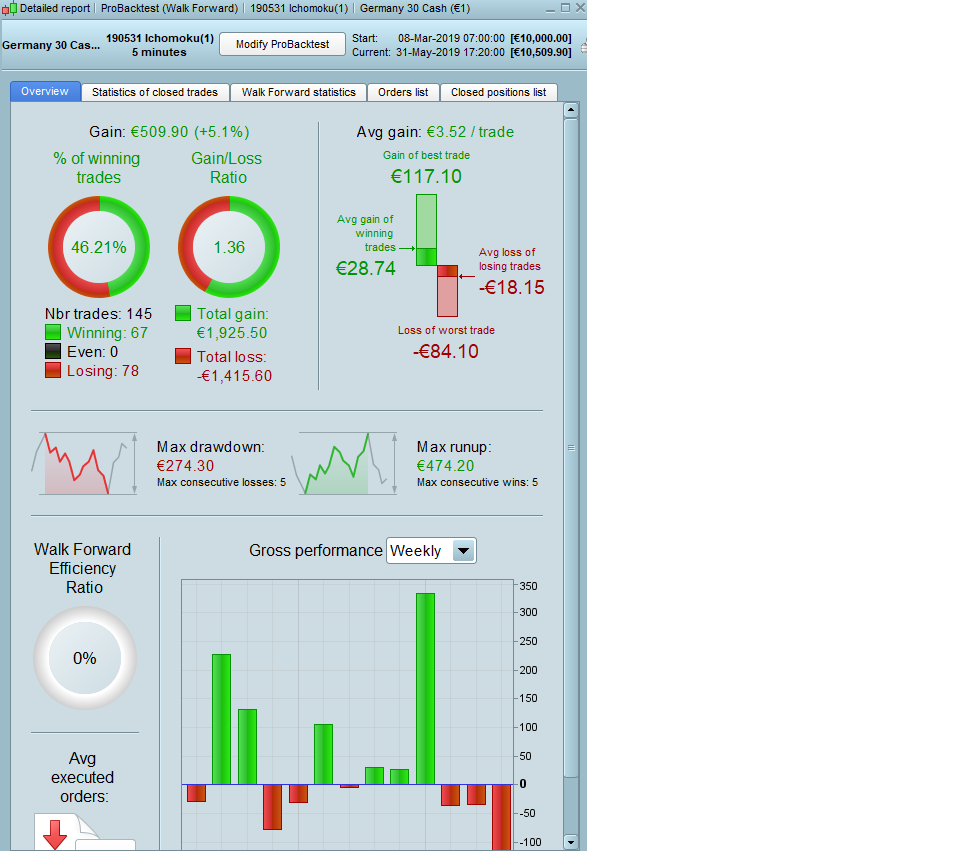
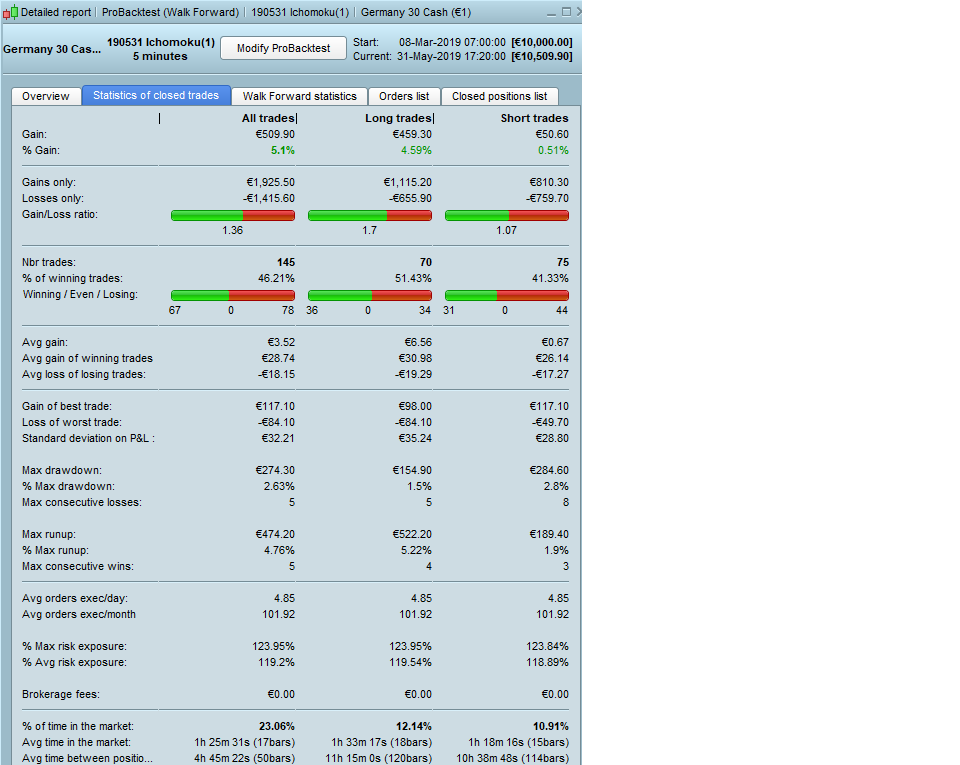
Works good on DJI on 3 min TF over 100k bars. I optimised the time settings at a 1 hour step over the 24 hour period, but best was how you have it set in the .itf file (08:00 to 16:00). I am in UK so a direct comparison to you may be 09:00 to 17:00 (as you are 1 hour ahead in Netherlands). Jan ... thank you so much for sharing your hard work with us all! GraHal PS it be a good / useful if you open a Topic on the Strategy coding Forum - "Discussion on Ichimoku Strategy by Jan Wind" I could then post my results on DJI 3 min. I will be running this in Forward Test starting 10 June 19.

Hello, the result on my plateform is totaly different...
how can we change the default settings?