






Beating the S&P 500 – Long Term
Hello!
This is my first submission to the strategy section of this site. My goal is to build filters for market regimes that provide the biases for more short term trading strategies. This submission is a byproduct of my research:
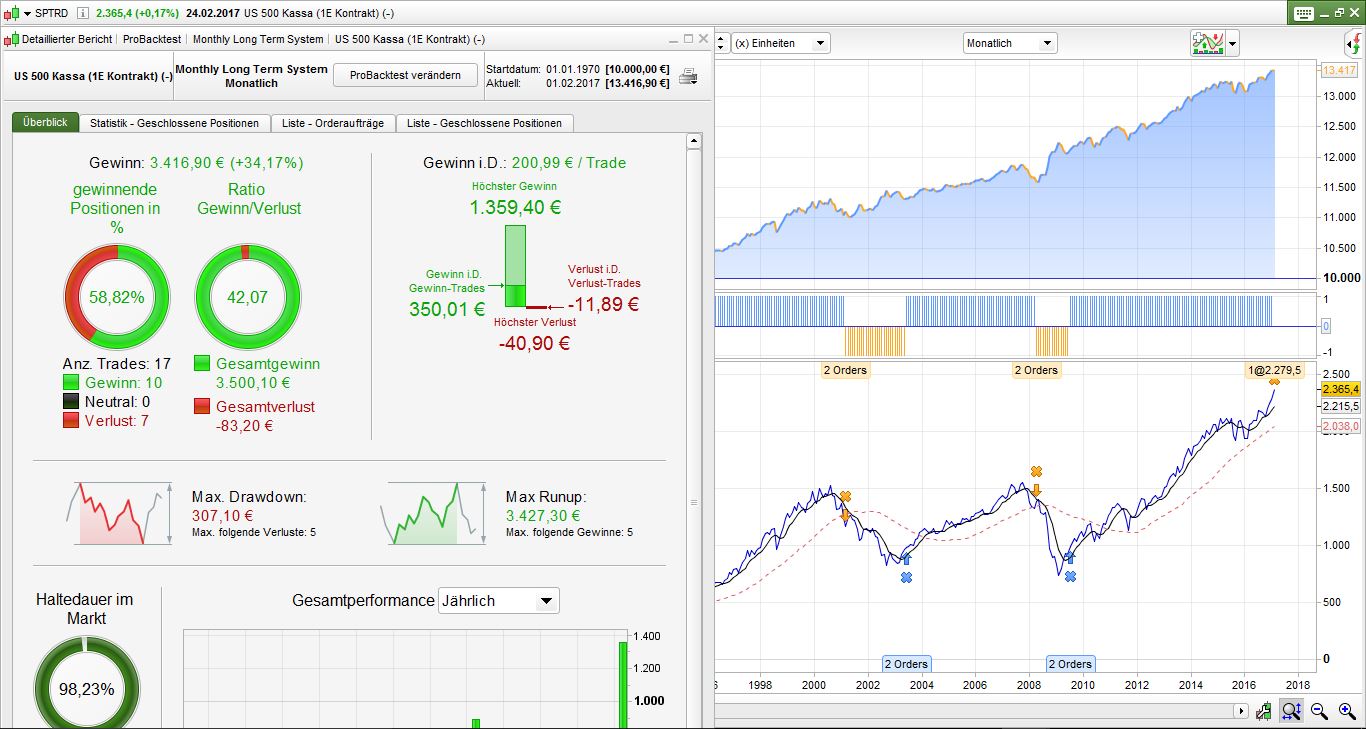
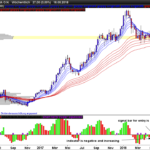
Following is a long term system based on a very simple timing model for capital preservation.
Timeframe is monthly and 2 indicators are used:
- John Ehlers Supersmoother at the standard value of 8.
- A 40 period simple moving average. The SMA has been improved and you can check it is robust to a range of variations.
The system is always on the market. Either long or short.
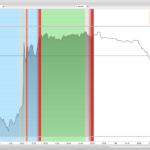
It doesn’t trade very often and it is not supposed to. The very upside of this model is not the profit but the maximum risk exposure of 13.22%! Maximum drawdown is 2.58 percent!
If you think this is interesting, please critique thoroughly because it will be highly appreciated.
DEFPARAM CumulateOrders = false
DEFPARAM PRELOADBARS = 40

//John Ehlers’ "Super Smoother", a 2-pole Butterworth filter combined with a 2-bar SMA that suppresses the Nyquist frequency:
Period = 8
Data = Close
PI = 3.14159
f = (1.414*PI) / Period
a = exp(-f)
c2 = 2*a*cos(f)
c3 = -a*a
c1 = 1 - c2 - c3
if barindex>Period then
 S = c1*(Data[0]+Data[1])*0.5 + c2*S[1] + c3*S[2]
endif

c1 = (close > S)
c2 = (S > S[1])

IF c1 AND c2 THEN
 EXITSHORT 1 CONTRACT AT MARKET
 BUY 1 CONTRACT AT MARKET
ENDIF

c3 = (close CROSSES UNDER Average[40](close))

IF c3 THEN
 SELL  AT MARKET
 SELLSHORT 1 CONTRACT AT MARKET
ENDIF
Comments
You must be logged in to post a comment.
It's a CFD on the futures contract. That's why there is no commission and IG calls it a Forward.
IG offers a automatic rollover into the next future/forward but this will cost more spread or slippage. For example when trading the US500 Jun-17 contract in January with minimum contract size this was no problem at all. But it could be.
With long-term contracts it's less of a problem though (but should not be neglected).

hi Derek,
so you mean that you are using CASH contract as US 500 Cash (mini or full doesn't matter) and this
kind of CFD doesn't involve nightly payments on the cash account ?
When you say that you have to do this manually, what exactly you do and when it is necessary ?
thx for the patience.
bye
Good question. Especially the special types of bear markets in the US can be misleading.
The exact same system even outperforms the Nikkei 225 unfortunately the risk is a lot higher and the entry in the bear market is a disaster. In cases like these I suggest to add another rule.
IF c1 AND c2 and close crosses over Average[40](close) THEN
EXITSHORT 1 CONTRACT AT MARKET
BUY 1 CONTRACT AT MARKET
ENDIF
This will reduce drawdowns a lot.

BONSOIR j ai tenté votre modification mais PRT ne l accepte pas "erreur de syntax" pouvez vous m aider a utiliser le code avec votre modif? merci cordialement


Hallo Derek, ich bin neu hier, wo finde ich die beiden Indikatoren? kansst du sie als itf posten, bitte? ich möchte die Indis zur Kontrolle im Chart sehen, danke. gatowman