






Wisper Breakout Strategy SAF40
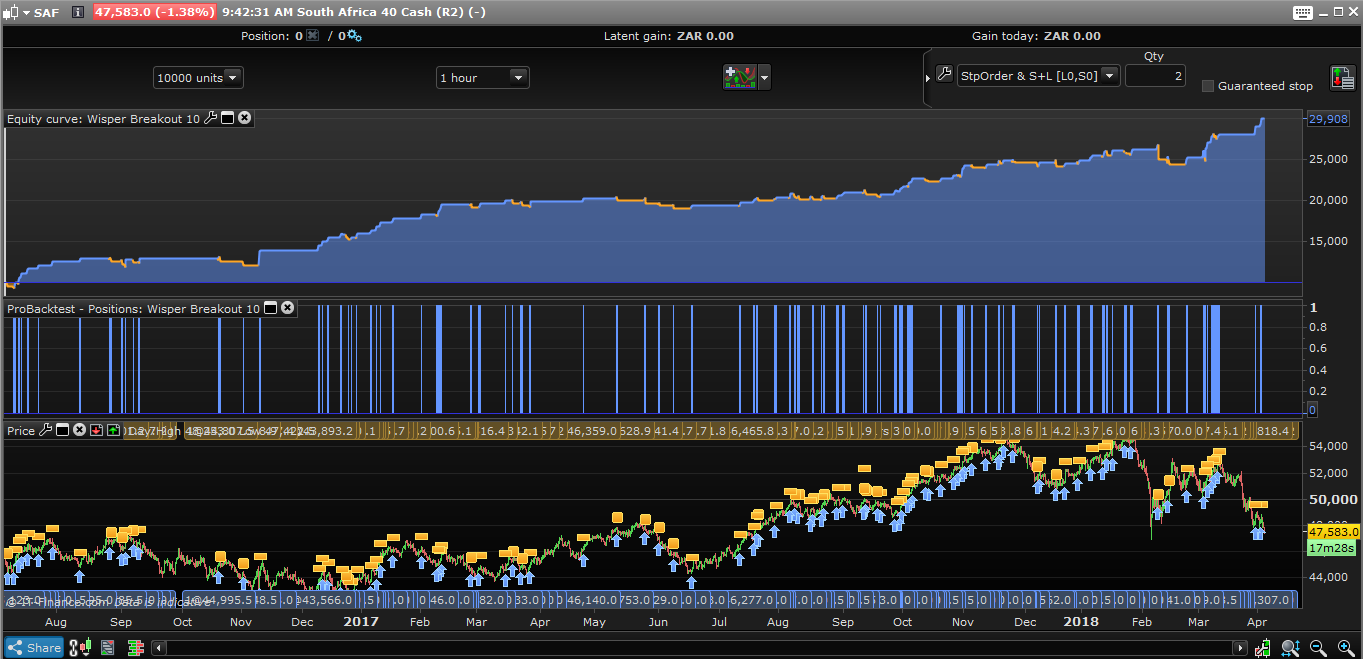
This strategy is one which takes advantage of only long opportunities in the SA Top 40 (SAF40) Index also known as the ALSI.
The code is testing if price is making new highs and lows before setting a new long order at market.
Target and loss levels are based upon the size of a factorized ATR 14 periods. Take profit size is larger than the stop loss one.
//-------------------------------------------------------------------------
// Main code : Wisper Breakout
//-------------------------------------------------------------------------
// Definition of code parameters
DEFPARAM CumulateOrders = false // Cumulating positions deactivated
daysForbiddenEntry = OpenDayOfWeek = 1 OR OpenDayOfWeek = 0

// Conditions to enter long positions
c1 = (close[3] <= high[4])
c2 = (close[3] >= low[4])
c3 = (close[2] <= high[3])
c4 = (close[2] >= low[3])
c5 = (close[1] <= high[2])
c6 = (close[1] >= low[2])

if high[4] > high[3] then
 ath = high[4]
else
 ath = high[3]
endif
if high[2] > ath then
 ath = high[2]
else
 ath = ath
endif
if high[1] > ath then
 ath = high[1]
else
 ath = ath
endif

c7 = (close > ath)

IF c1 AND c2 AND c3 AND c4 AND c5 AND c6 AND c7 AND not daysForbiddenEntry THEN
 BUY 1 CONTRACT AT MARKET
ENDIF

// Stops and targets
atr = AverageTrueRange[14](close)
SET STOP pLOSS atr * 2
SET TARGET pPROFIT atr * 2.5
Comments
You must be logged in to post a comment.
I Agree with you JaunJ, and Yes Eric, what you say makes sense too. Optimizing the Stop Loss and Profit Target to 3.9 and 3.5 X ATR respectively back-tested in favour of the system at a spread of 30. I guess we can play around with the numbers but ultimately I feel that the logic of the system still holds true.


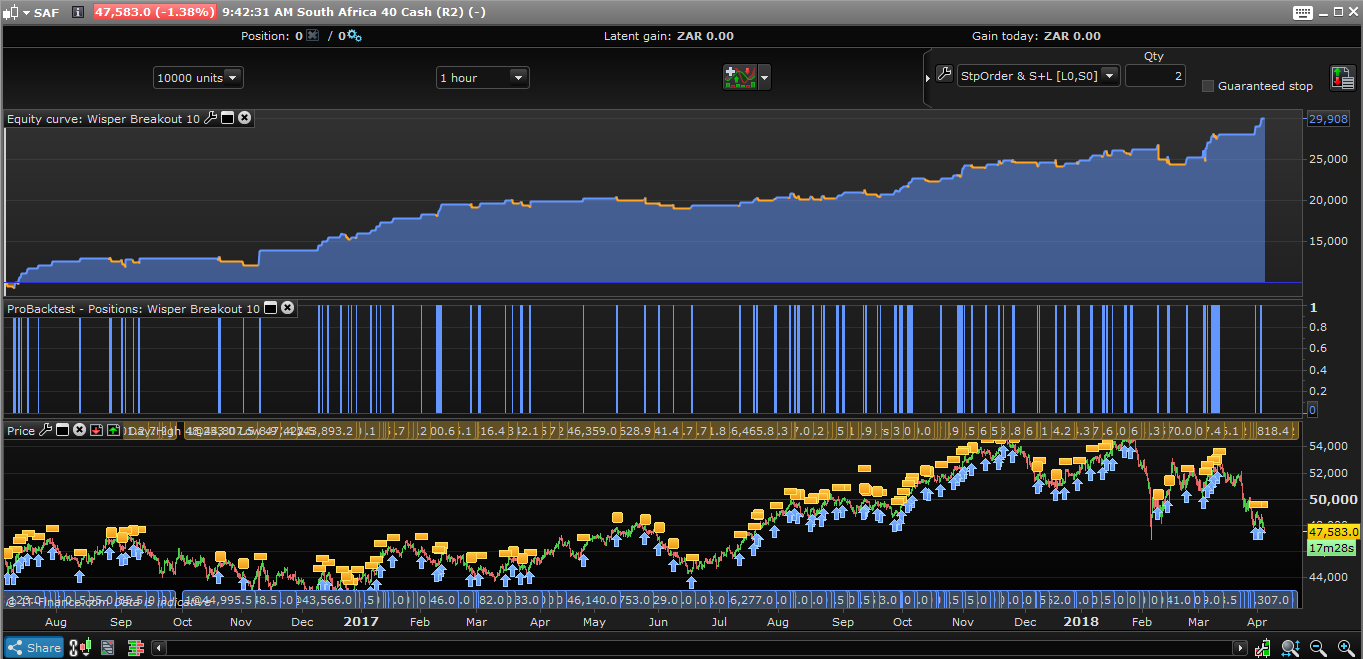
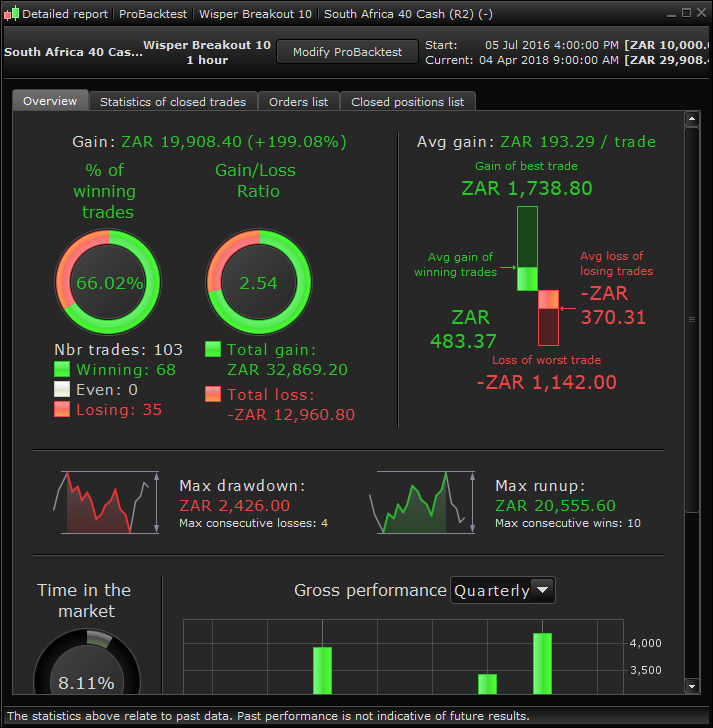
If I run the backtest with a zero spread the backtested result look similar to your screenshot. If however, I include a realistic spread of 40 the backtest only show the strategy to be profitable after November 2016. The strategy opens trades both in and out of market hours, meaning it would make sense to include an average spread between the usual 30 (in market hours) and 50 (outside market hours).
Thanks for the system Casenova. In determining the high of the past 4 bars, is there a reason you didn't use the "highest" command? I'm getting to grips with the code and was curious.