






FTSE MIB goes up at night strategy
Hello everyone.
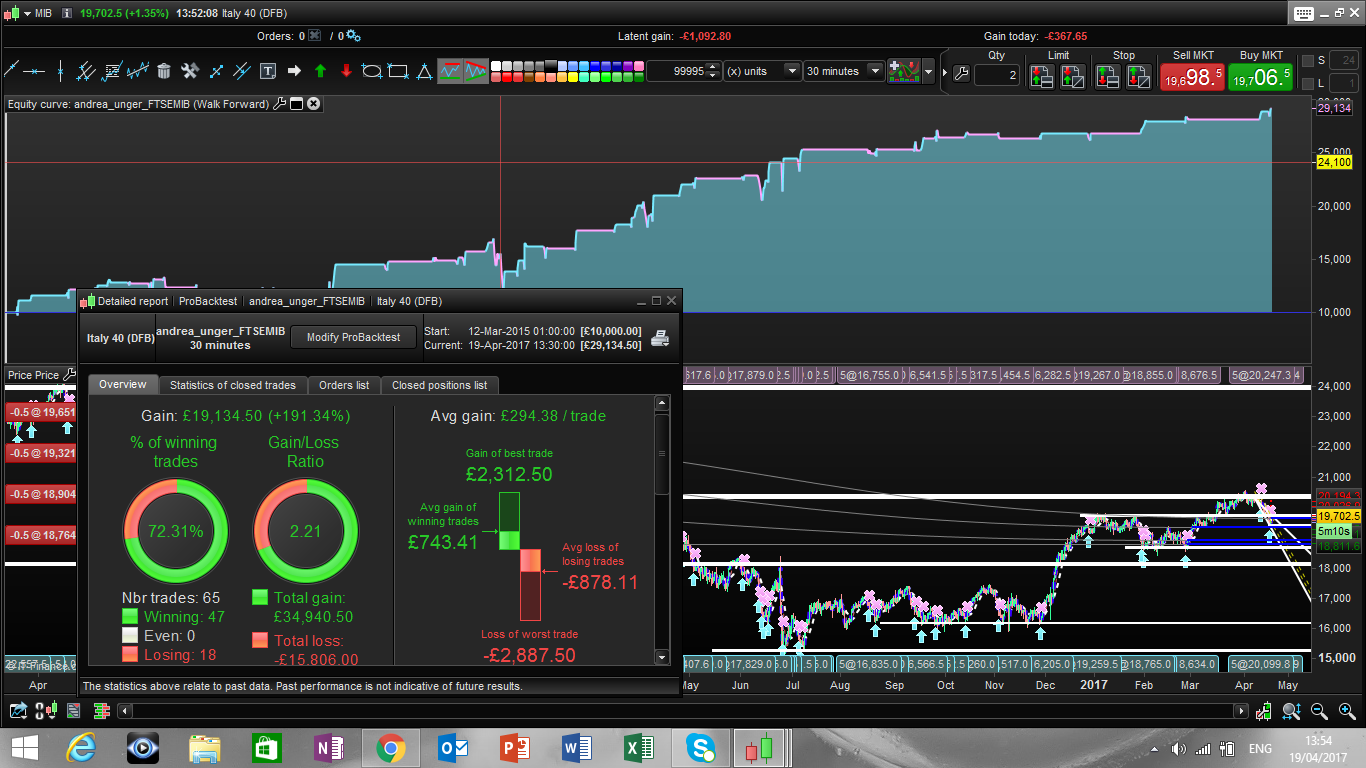
I have coded for PRT this strategy that is based on the publicly available informations on Andrea Unger idea which exploits the fact that the FTSE Mib goes up mainly during night hours.
The idea is simple: buy the index at 5.30 PM and sell it at 9.30 AM.
In the code I added some filters that were discussed in a webinar by Andrea Unger, basically you buy the index at 5.30PM if the open price at 09.30 is < of the previous close and if the closing price at 5.30 pm is lower than the 2 previous daily lowest.
Results and code is attached.
Let me know what you think!
Many thanks
Francesco
// Definition of code parameters
DEFPARAM CumulateOrders = False // Cumulating positions deactivated
timenter = time = 173000
timexit = time = 093000

timeobsopen = time = 093000
if timeobsopen Then
 priceopen = open
endif

timeobsclose = time = 173000
if timeobsclose then
 priceclose = open
endif

c1 = priceopen < DClose(1)
min1 = Dlow(1)
min2 = Dlow(2)
//min3 = Dlow(3)
result = Min(min1,min2)
//minimo = Min(result,min3)

c2 = (priceclose <= result)
size = 5

c3 = c1 and c2

IF c3 AND timenter  THEN
 BUY size PERPOINT AT MARKET
ENDIF

if timexit then
 sell at market
endif
Comments
You must be logged in to post a comment.

Many thanks JR1976 for your improvement,
although results with your filter looks better there is a problem of lack of proper statistic in both mine and yours, as with 100000 observation we get less than 100 trades.
That being said the code is well known as it is a strategy Andrea Unger presented in his webinar and Im quite confident that it was working even in the past.
I really hope someone will test it with 200K bars sometime soon.
Regards
Francesco
Dear Francesco,
nice code .... I have added the stop loss and and the check with ATR 50
What do you think? Should be interest to test with 200k unit
DEFPARAM CumulateOrders = False // Cumulating positions deactivated
timenter = time = 173000
timexit = time = 093000
if timeobsopen Then
priceopen = open
endif
if timeobsclose then
priceclose = open
endif
min1 = Dlow(1)
min2 = Dlow(2)
//min3 = Dlow(3)
result = Min(min1,min2)
//minimo = Min(result,min3)
size = 1
/// New
volfilter= indicator1>30
//Indicatore1 = CALL "ALE_secure"
//if currentmonth <> 8 then
//IF Indicatore1 then
if currentdayofweek <> 5 then
IF c3 AND timenter and volfilter THEN
BUY size PERPOINT AT MARKET
ENDIF
endif
if timexit then
sell at market
endif
set stop ploss 350
6 ticks noramlly here in Italy.

Hi Kasper and thank you for your comment, unfortunately I cant test more than that with my PRT because I dont have a premium membership. Would be really great if someone could do more deeper tests indees.
Regards
Francesco

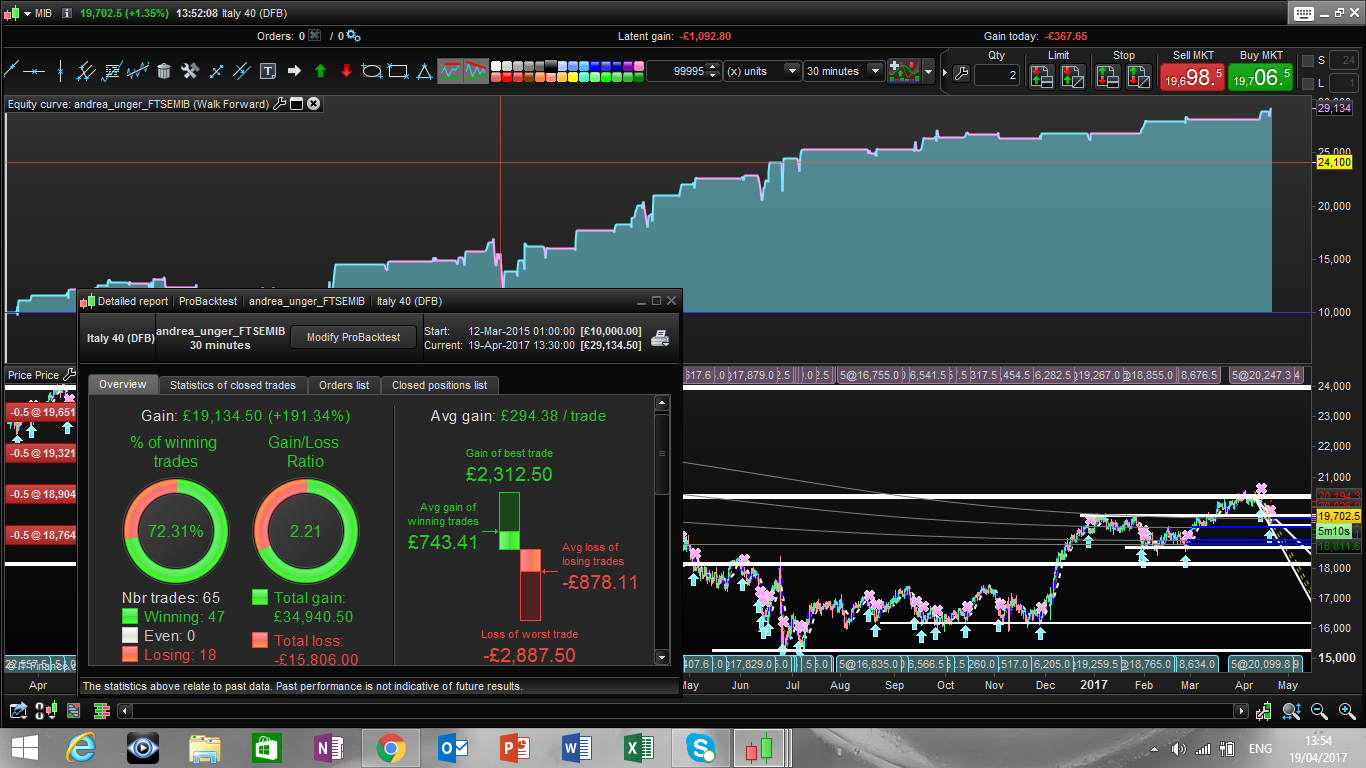

Hi Francesco. Did you try and test with a stoploss and take profit code, so there was an RR>1? Also it could be great to have it tested on a 200k unit. Even though the numbers are great, 65 trades is a bit low for a statistic.
Cheers Kasper
Hi JR, yes indeed quite disappointing in may and today, but still within the max drawdown shown historically, any idea to improve the strategy will be very welcome!