






The "RSI 2P" from Larry Connors
Hi all,
Here is another strategy from Larry Connors, that I did coded for us.
It was designed for M30 timeframe, on various indices / forex / raw materials. But my tests show that is is most of time unprofitable.
I also find that some values are profitable with it, on higher timeframes.
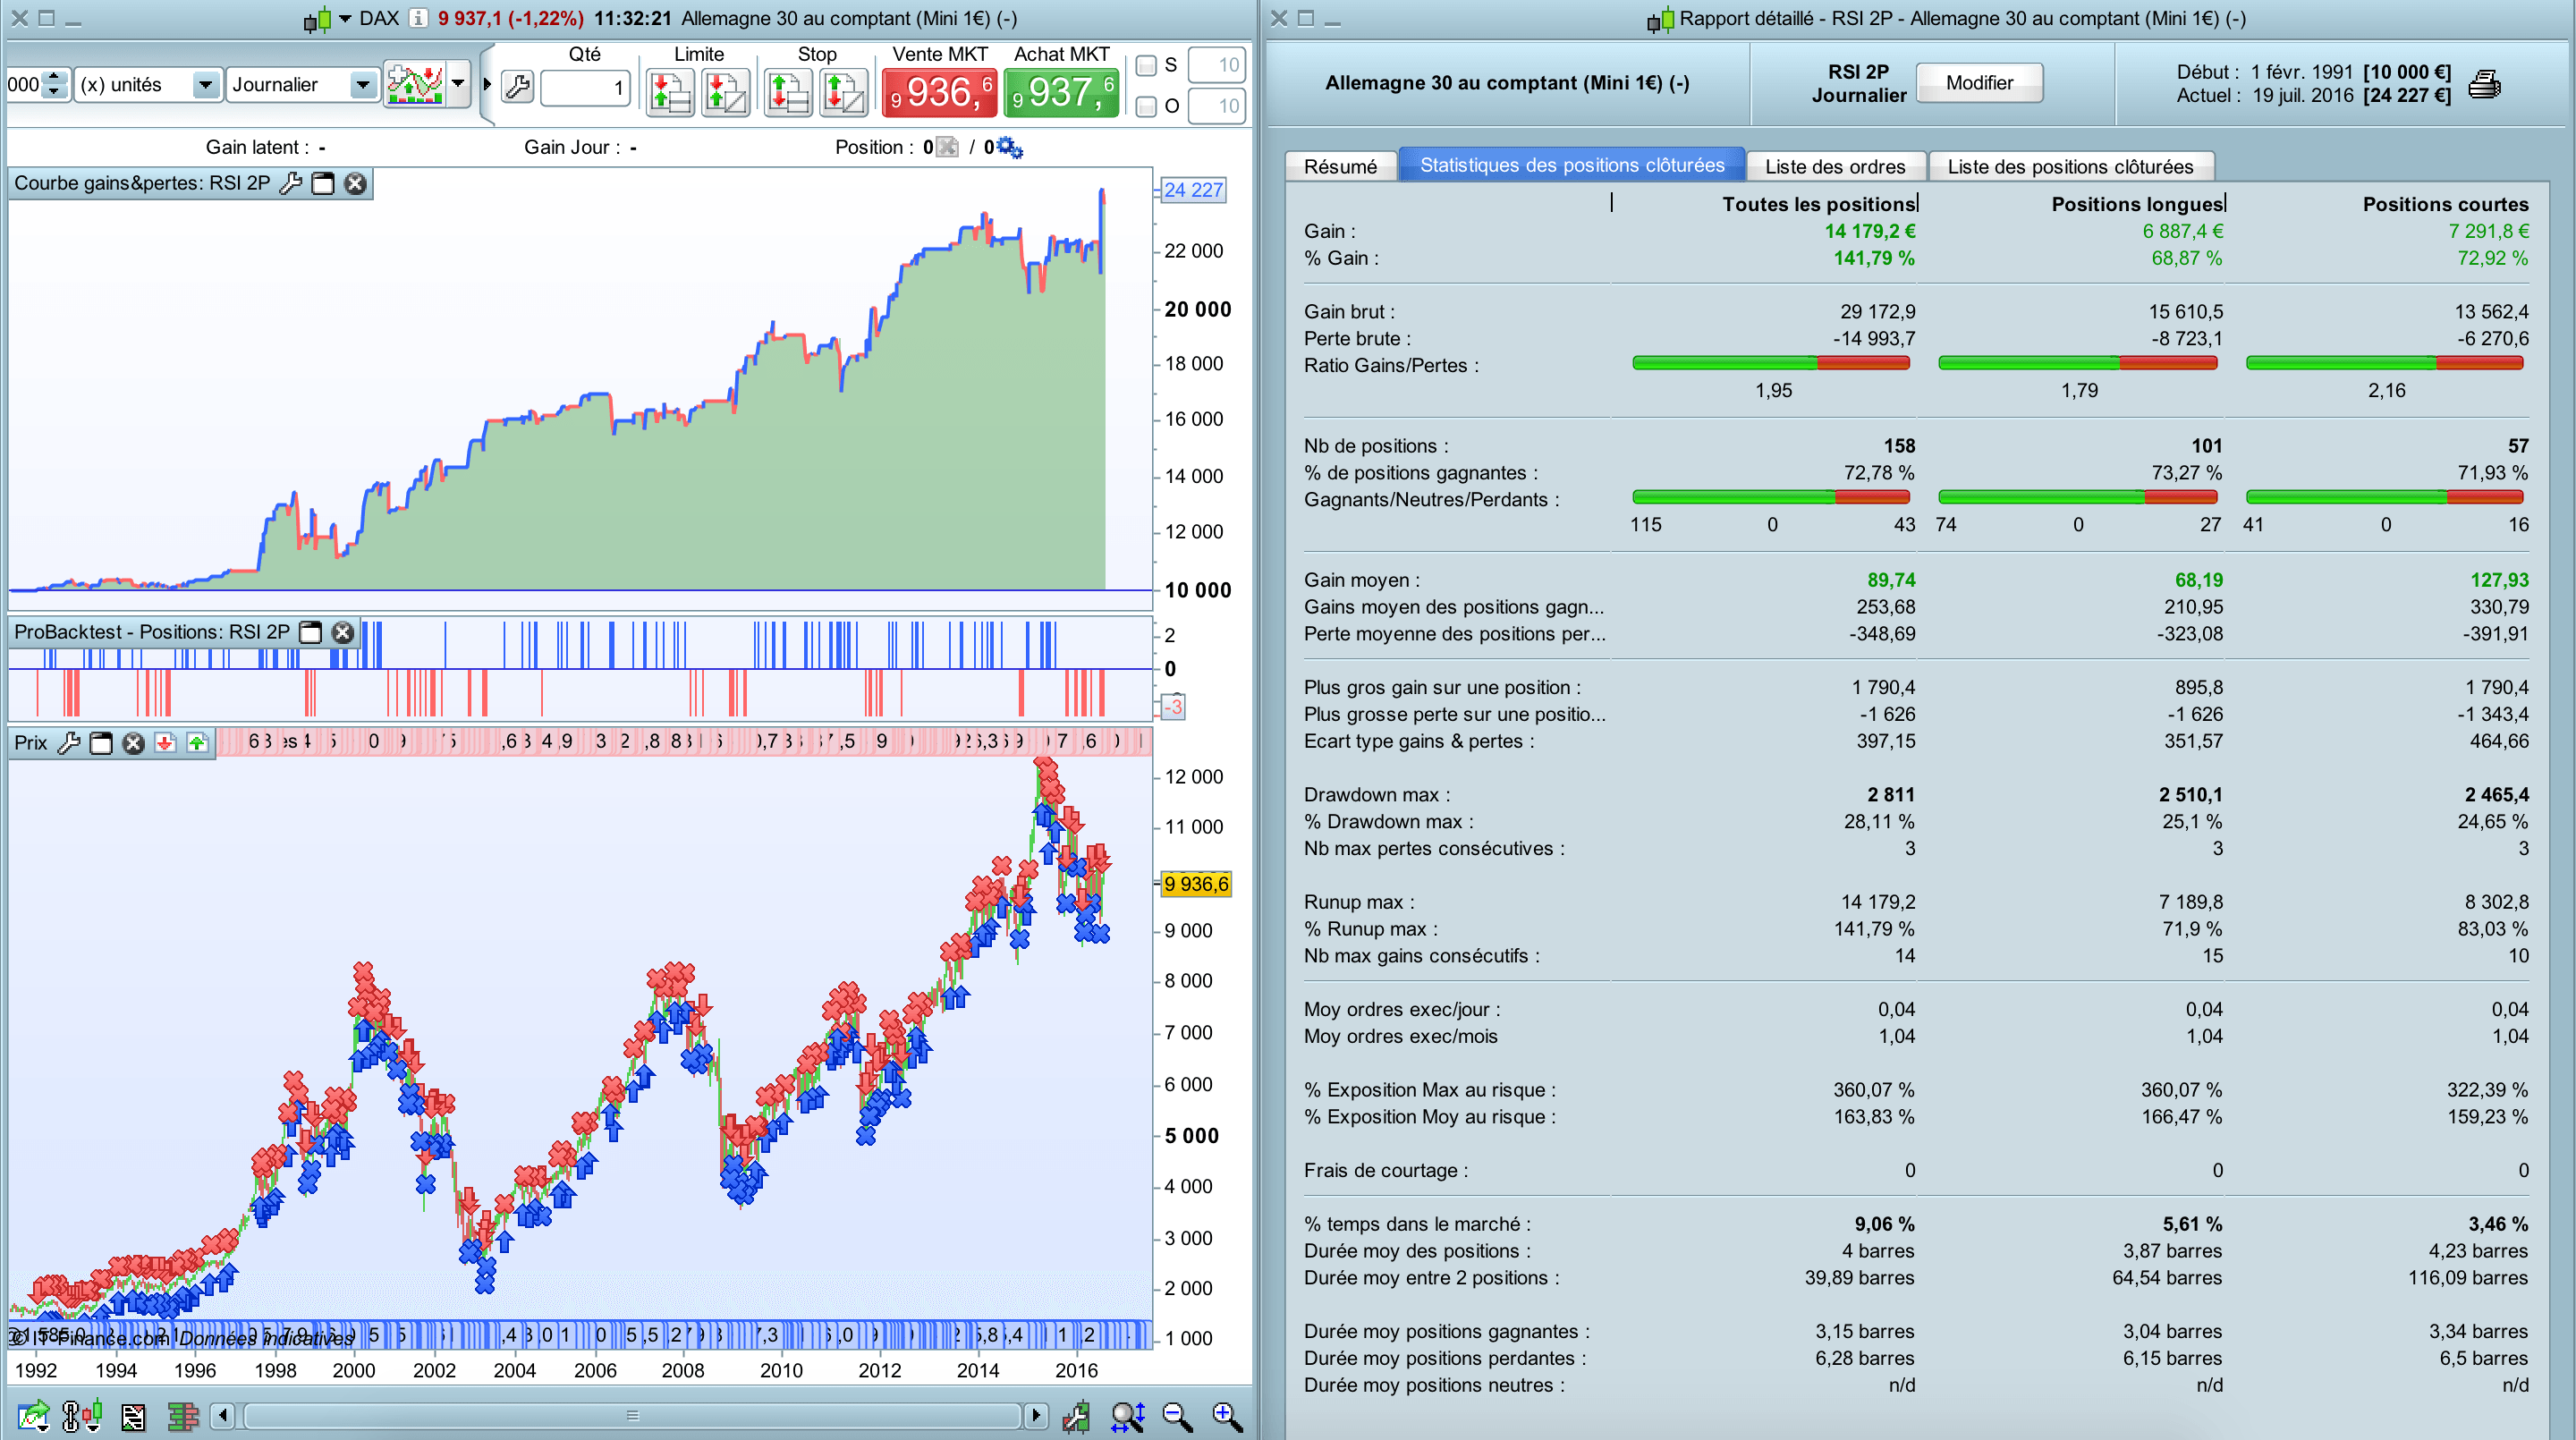
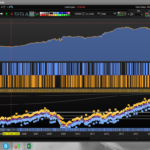
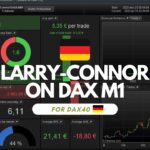
For example as show in the backtest picture (CFD Germany 30, 1€ per point, spread 1 point, daily timeframe).
RULES aver very simple :
BUY if :
- close > SMA200
- RSI2 < 5
CLOSE BUY if :
- close > SMA5
That’s all.
Opposite rules for SELL positions.
Larry Connors didn’t use stop loss ; but you can set one.
// RSI 2P
// de Larry Connors
// www.doctrading.fr

DEFPARAM CUMULATEORDERS = false
n = 3   // mettre ce que vous voulez

// INDICATEURS
MM200 = average[200](close)
MM5 = average[5](close)
RSI2 = RSI[2](close)

// ACHAT
ca1 = close > MM200
ca2 = RSI2 < 5

IF ca1 and ca2 then
 BUY n shares at market
ENDIF

// SORTIE ACHAT
IF close > MM5 THEN
 sell at market
ENDIF

// VENTE
cv1 = close < MM200
cv2 = RSI2 > 95

IF cv1 and cv2 THEN
 SELLSHORT n shares at market
ENDIF

// SORTIE VENTE
IF close < MM5 THEN
 exitshort at market
ENDIF
Comments
You must be logged in to post a comment.

Hi,
Thanks for your works
Sadly, as always, without Walk Forward system, sadly it means nothing
As you said, it was generally unprofitable until you "optimize" somes variables
Personnaly, I stopped doing backtestsand even automatic trading with this actual poor system of PRT with all the defaults with speak before
Have a nice day
Zilliq

Hello Zilliq,
You don't need a system to produce a walk forward test. You can easily create one with help from Excel. Just optimize the "in sample" period and test it on the "out of sample" period and copy the results into Excel were you have created a curve builder. Just as effective in the end as if a system would do for you. It takes some time though.
It is incredible! Thanks for sharing, Doctrading!