






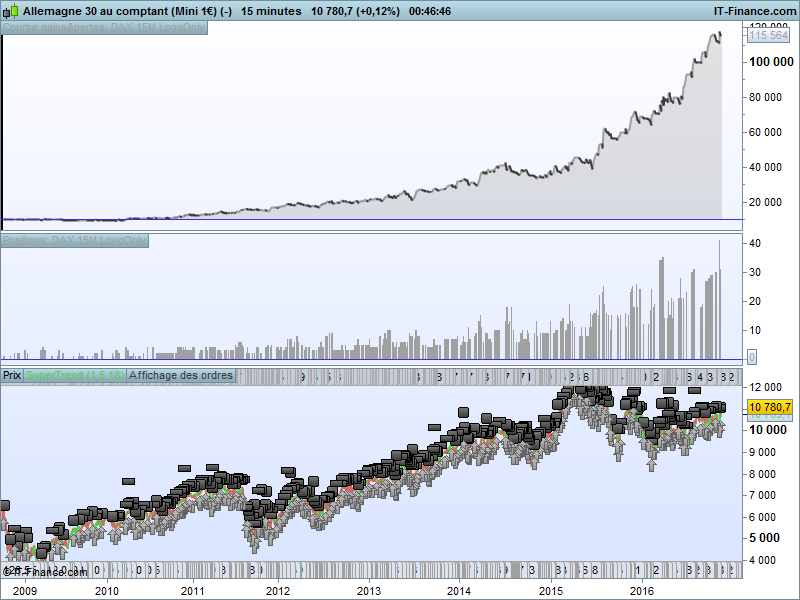
DAX 15Min - False Breakout / SuperTrend
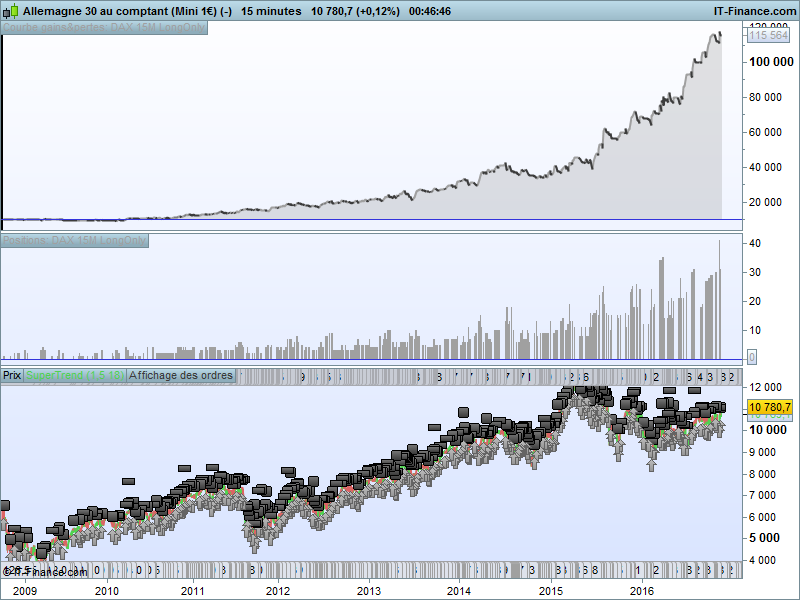
Hi everyone,
First I’d like to thank you all for your contribution on this website. It’s been a goldmine for me so far 😉
You all found good names for your strategies but to be honest I haven’t find mine yet..
Anyway, here is the thing:
- Index: Dax 1€
- TF: 15M
- $Risk: You choose ! 😉 – 1.5% of capital per trade in my backtest. Up to 3.7% due to seasonality (Thanks ALE for your piece of code about seasonality)
- Spread: 2 pips
Variables were optimized different ways. Optimization from the beggining of PRT datas to 31/12/13 shows substantially the same trend. I hope my curve remains not so fitted..
Drawbacks:
- Not so many trades
- Several trades could last a very long time
- Time between trades is also too long
- The reverse short strategy does not lead to gains..
Thus, if you have any comments, ideas or anything that could improve this strategy, it would be really appreciated ! 😉
Thank you all and keep posting interesting things here, I like it !
Maxime
DEFPARAM CumulateOrders = false
//DAX - 15M

sl=80
tp=150
p=18
d=20
m=1.5
Rg = 0.5

ONCE Januaryl = 1
ONCE Februaryl = 2
ONCE Marchl = 3
ONCE Aprill = 1
ONCE Mayl = 1
ONCE Junel = 2
ONCE Julyl = 3
ONCE Augustl = 1
ONCE Septemberl = 1
ONCE Octoberl = 1
ONCE Novemberl =2
ONCE Decemberl = 2
ONCE Monday = 2
ONCE Tuesday = 2
ONCE Wednesday = 1
Once Thursday = 1
Once Friday = 1
Once Saturday = 1
Once Sunday = 1

If Opendayofweek = 1 then
 DayMult = Monday
ElsIf Opendayofweek = 2 then
 DayMult = Tuesday
ElsIf Opendayofweek = 3 then
 DayMult = Wednesday
ElsIf Opendayofweek = 4 then
 DayMult = Thursday
ElsIf Opendayofweek = 5 then
 DayMult = Friday
ElsIf Opendayofweek = 6 then
 DayMult = Saturday
ElsIf Opendayofweek = 7 then
 DayMult = Sunday
Endif
// saisonal pattern long position
IF CurrentMonth = 1 THEN
 saisonalPatternMultiplierl = Januaryl
ELSIF CurrentMonth = 2 THEN
 saisonalPatternMultiplierl = Februaryl
ELSIF CurrentMonth = 3 THEN
 saisonalPatternMultiplierl = Marchl
ELSIF CurrentMonth = 4 THEN
 saisonalPatternMultiplierl = Aprill
ELSIF CurrentMonth = 5 THEN
 saisonalPatternMultiplierl = Mayl
ELSIF CurrentMonth = 6 THEN
 saisonalPatternMultiplierl = Junel
ELSIF CurrentMonth = 7 THEN
 saisonalPatternMultiplierl = Julyl
ELSIF CurrentMonth = 8 THEN
 saisonalPatternMultiplierl = Augustl
ELSIF CurrentMonth = 9 THEN
 saisonalPatternMultiplierl = Septemberl
ELSIF CurrentMonth = 10 THEN
 saisonalPatternMultiplierl = Octoberl
ELSIF CurrentMonth = 11 THEN
 saisonalPatternMultiplierl = Novemberl
ELSIF CurrentMonth = 12 THEN
 saisonalPatternMultiplierl = Decemberl
ENDIF

aMax = Highest[d](High)
aMin = Lowest[d](Low)
SupTnd = SuperTrend[m,p]
RngOk = (High-Low)/(aMax-aMin)<Rg

Equity = 10000+StrategyProfit
Risk = 0.015
n = Max(1,Equity*Risk/Sl/PipValue*SQRT(DayMult*saisonalPatternMultiplierl))
//n=1
cBuy = aMin[1]<aMin[2] And High<aMax[1] And Close>Open And RngOk And Close>SupTnd

If cBuy Then
 Buy n Shares at Market
EndIf

SET STOP ploss sl
SET TARGET pPROFIT tp
Comments
You must be logged in to post a comment.


Hi Triss. the File is in the post for download. There is nothing wrong with the code. Your error describes 2 line- but it empty- perhaps some character sneaked in yours? . Please check that you code is correct copied. or download the file dax-15m-longonly.itf
Cheers Kasper

why do I get error ond line whit DAX? Eihter cod works. Can you chare the file?


Try sniptool/snippingtool?
http://www.capture-screenshot.org/snipping-tool/
Jonjon, do you have screenshoot of this strategy in tick by tick mode?
Hi,
Thanks for your comments and sorry for my late answer :)
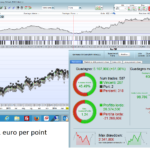
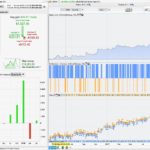
m, d & p are optimized variables which I chose to maximize the Profit/Drawdown Ratio. Hence, since September 2012 using my last settings (0.5 %Loss / 1.5 %Profit / No reinvestment / No multipliers) it gives a worst loss of 1.77%, a DD of 12.8% and a profit of 94.17% with gain/loss = 1.51 and 33.21 winning trades.
As all except 1 of the winning trades came after more than 5 candles in this last backtest, my guess is that tick mode or not it won't change many things.
Maxime

This is very cool. Thank you very much.
I've been playing a bit with it. How did you get your m, p and d values? m and p relate to the Supertrend indicator....as I'm new to this indicator can you tell me if these are pretty standard variables? d = 20 seems reasonable to me.
I have just started paper trading the strategy. Adjusted the variables slightly to make a little more conservative: Rg = 0.4, Risk = 0.01, No reinvest. I've also optimised the p and d to 26 and 21 respectively (hence my question above).
Back tested in tick mode from Sept 2012 which is just 60,000 units back (round number, nothing scientific there however thought it appropriate to base test from period post Draghi saying that ECB would do anything to stop Euro failing in July 2012 and then subsequent quieting down of volatility / market).
I can't attach my results (is this as I'm a Junior Member?)
% winning trades = 40%
Gain / Loss: 2.01
I still want to get the loss of the worse trade down (-3,752) and the size of the Maxdrawdown is too large (-19,291 with 8 consecutive losses).
I'll look further into it however anyone looked at the poor performance in Q2 2013 and last quarter of this year? Down periods are to be expected but just wondering whether there was anything macro going on that we should bear in mind going forward.
I'll let you know how my trades go with this. Looking forward to hearing from any other of you guys paper trading this.
Cheers


Hi Cosmic! What is meant by curve fitting and walk forward test?
Hi!
Thanks for your comments and thanks Reiner for your syntax on seasonality.
I did some walk forward testing and found quite good results particularly in the recent period (see attached .xlsx file).
In my testing, I just managed to solve for the tp and sl (changed from pips to percentages in this study) which give me the best Return/Drawdown ratio using a 2 years period. Then I used those parameters for the next 6 months. And again, and again !
Here is my last version of the code used for this test:
DEFPARAM CumulateOrders = false
//DAX - 15M

ONCE p=18
ONCE d=20
ONCE m=1.5
ONCE Rg = 0.5
ONCE Risk = 0.015
ONCE Monday =2
ONCE Tuesday = 2
ONCE Wednesday = 1
Once Thursday = 1
Once Friday = 1

If Opendayofweek = 1 then
DayMult = Monday
ElsIf Opendayofweek = 2 then
DayMult = Tuesday
ElsIf Opendayofweek = 3 then
DayMult = Wednesday
ElsIf Opendayofweek = 4 then
DayMult = Thursday
ElsIf Opendayofweek = 5 then
DayMult = Friday
Endif

aMax = Highest[d](High)
aMin = Lowest[d](Low)
SupTnd = SuperTrend[m,p]
RngOk = (High-Low)/(aMax-aMin)<Rg
sl=0.5
tp=1.5
Reinv = 1
Coef = 0
Balance = 23827.1
If Reinv = 1 Then
Equity = Balance+StrategyProfit
Else
Equity = 10000
EndIf
If Coef<>1 Then
DayMult=1
EndIf

n = Max(1,Equity*Risk/(Close*Sl/100)*SQRT(DayMult))

cBuy = aMin[1]<aMin[2] And High<aMax[1] And Close>Open And RngOk And Close>SupTnd

If cBuy Then
Buy n Shares at Market
EndIf

SET STOP %loss sl
SET TARGET %PROFIT tp
Maxime


The code dose not work
Syntax error: line 2, character 12
One of the following characters would be more suitable than "CumulateOrders":
- ","
- "
Why?
Thank you very much for this fascinating trading system. It is still proving to be extremely effective in 2024. It illustrates once again how valuable individual trading systems can be.