



More from ProRealCode
ProRealCode - Trading & Coding with ProRealTime™
The ProRealTime™ community on the web! Officially sharing ProRealTime knowledge to Worldwide users since 2015!



The "BIG Candle" strategy
June 6, 2016, 8:20 AM
Strategies
2 Comments
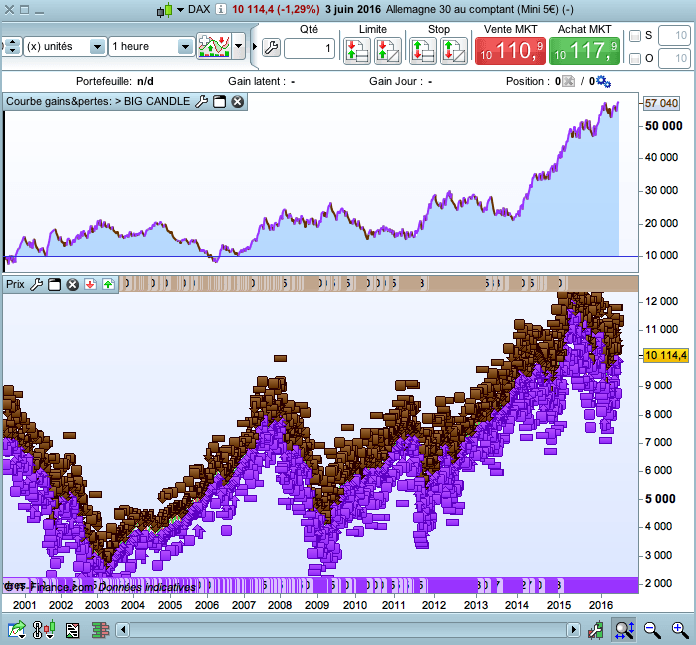
Hi all,
This strategy can be applied on any timeframe.
It seems to be very very profitable on M15 timeframe on the DAX. But because of the spread, it’s not really winning.
So you must test it on > H1 timeframe.
The strategy takes position with a “big candle”, which breaks the highest(8) or lowest(8), and with an amplitude > ATR(24).
The take profit is same to the stop loss * 1.5
The backtest is made with 1 point spread on the DAX (trades taken from 09AM to 5PM).
Maybe someone could improve it.
Best regards,
DEFPARAM CumulateOrders = False

n = 1

Haut = highest[8](high[1])
Bas = lowest[8](low[1])
amplitude = abs(close - open)

Ctime = time >= 090000 and time <= 170000

// CONDITIONS ACHAT
c1a = close > open
c2a = close > Haut
c3a = amplitude > AverageTrueRange[24]

IF c1a AND c2a AND c3a AND Ctime THEN
 BUY n shares AT MARKET
ENDIF

// CONDITIONS VENTE
c1v = close < open
c2v = close < Bas
c3v = amplitude > AverageTrueRange[24]

IF c1v AND c2v AND c3v AND Ctime THEN
 sellshort n shares AT MARKET
ENDIF

// STOP LOSS & TAKE PROFIT
sl = 20     // 20 en M15   75 en H1
set stop loss sl
set target profit sl*2
Download
Filename:
BIG-CANDLE.itf
Downloads:
171
Master
Hello, I'm Marc.
Nice to meet you.
Author’s Profile
Similar code
Bollinger200 TrendCatcher 15minStrategies
DAX Trend following – 2-hours timeframeStrategies

Loading...
Hello,
As I usually say, strategies are exposed to be improved :)
So yes, I think there must be good ways to improve this one.
We could set an ATR ratio as a stop loss / take profit, it could be done.