

Traducir de mq4 a PRT:"Quantile based signed volume analysis"

Viewing 8 posts - 1 through 8 (of 8 total)
  • Author
    Posts
  • #112904 quote
    Fr7Fr7
    Participant
    Master

    Hola Nicolás,

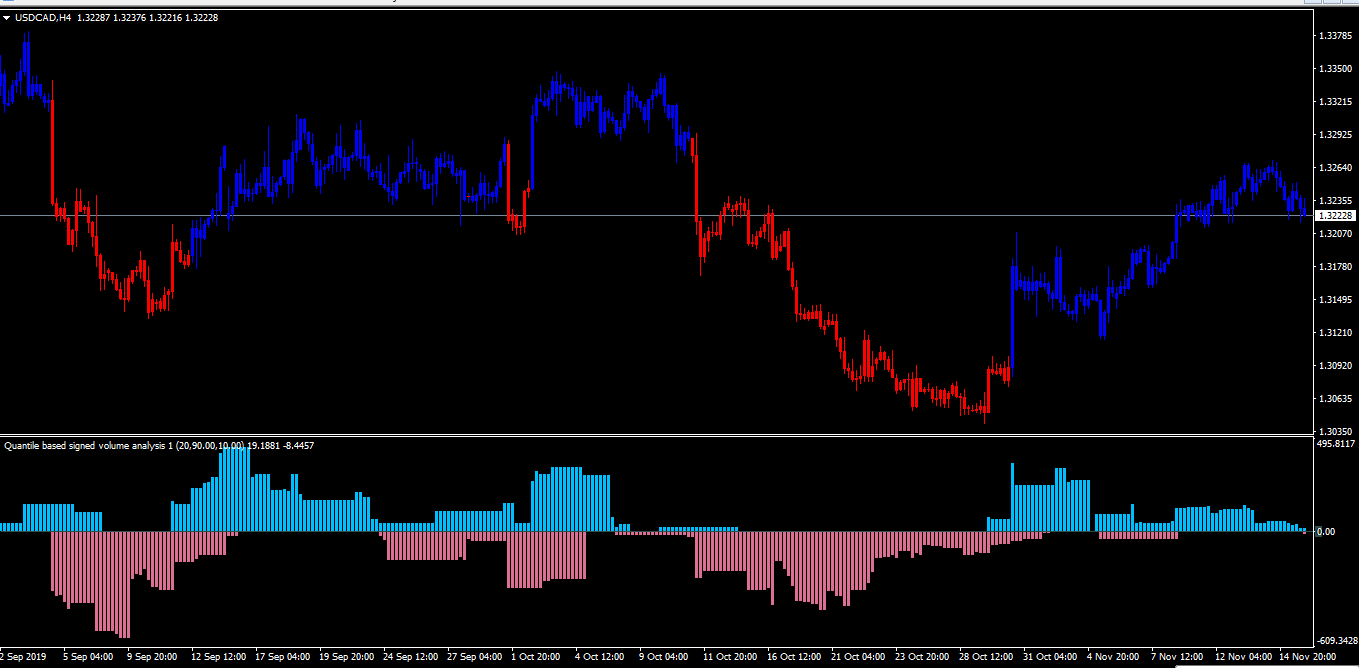
    A ver si es tan amable de traducir este código de mq4 a PRT.

    Se basa en el indicador ATR y el volumen.

    Creo que sería un indicador de gran utilidad.

    Un saludo y gracias.


    //+------------------------------------------------------------------+
    //|                            Quantile based signed volume analysis |
    //+------------------------------------------------------------------+
    #property copyright 
    #property link      
    
    #property indicator_separate_window
    #property indicator_buffers 2
    #property indicator_color1  DeepSkyBlue
    #property indicator_color2  PaleVioletRed
    #property indicator_width1  2
    #property indicator_width2  2
    
    //
    //
    //
    //
    //
    
    extern int    Periods             = 20;
    extern ENUM_APPLIED_PRICE Price   = PRICE_CLOSE;
    extern double UpQuantilePercent   = 90;
    extern double DownQuantilePercent = 10;
    extern double AtrUpperPercent     = 75;
    extern double AtrLowerPercent     = 25;
    extern bool   LimitToZeroes       = true;
    extern bool   UseRealVolume       = false;
    
    //
    //
    //
    //
    //
    
    double bufferUp[];
    double bufferDn[];
    double quantUp[];
    double quantDn[];
    double prices[];
    double trend[];
    
    
    //+------------------------------------------------------------------+
    //|                                                                  |
    //+------------------------------------------------------------------+
    //
    //
    //
    //
    //
    
    int init()
    {
       IndicatorBuffers(6);
          SetIndexBuffer(0,bufferUp); SetIndexStyle(0,DRAW_HISTOGRAM);
          SetIndexBuffer(1,bufferDn); SetIndexStyle(1,DRAW_HISTOGRAM);
          SetIndexBuffer(2,quantUp);
          SetIndexBuffer(3,quantDn);
          SetIndexBuffer(4,prices);
          
          //
          //
          //
          //
          //
          
          Periods             = MathMax(Periods,1);
          UpQuantilePercent   = MathMax(MathMin(UpQuantilePercent,100),0);
          DownQuantilePercent = MathMax(MathMin(DownQuantilePercent,100),0);
       IndicatorShortName("Quantile based signed volume analysis 1 ("+Periods+","+DoubleToStr(UpQuantilePercent,2)+","+DoubleToStr(DownQuantilePercent,2)+")");
       return(0);
    }
    int deinit() { return(0); }
    
    //+------------------------------------------------------------------+
    //|                                                                  |
    //+------------------------------------------------------------------+
    //
    //
    //
    //
    //
    
    int OnCalculate (const int rates_total,      // size of input time series 
                     const int prev_calculated,  // bars handled in previous call 
                     const datetime& time[],     // Time 
                     const double& open[],       // Open 
                     const double& high[],       // High 
                     const double& low[],        // Low 
                     const double& close[],      // Close 
                     const long& tick_volume[],  // Tick Volume 
                     const long& volume[],       // Real Volume 
                     const int& spread[]         // Spread 
       )
    {
       int counted_bars=IndicatorCounted();
       int i,limit;
    
       if(counted_bars<0) return(-1);
       if(counted_bars>0) counted_bars--;
               limit=MathMin(Bars-counted_bars,Bars-1);
    
       //
       //
       //
       //
       //
    
       for(i=limit; i>=0; i--)
       {
          prices[i]  = iMA(NULL,0,1,0,MODE_SMA,Price,i);
          quantUp[i] = iQuantile(Periods,UpQuantilePercent  ,i);
          quantDn[i] = iQuantile(Periods,DownQuantilePercent,i);
          
          //
          //
          //
          //
          //
          
          bufferUp[i] = 0;
          bufferDn[i] = 0;
          for (int k=0; k<Periods; k++)
          {
             double atr  = iATR(NULL,0,1,i+k);
             double sign = 0;
                if (prices[i+k] > Low[i+k]+atr*AtrUpperPercent/100.0 && prices[i+k]>prices[i+k+1]) sign =  1;
                if (prices[i+k] < Low[i+k]+atr*AtrLowerPercent/100.0 && prices[i+k]<prices[i+k+1]) sign = -1;
                if (!UseRealVolume)
                {
                   if (prices[i+k] > quantUp[i+k]) bufferUp[i]+= sign*tick_volume[i+k]*prices[i+k]*atr;
                   if (prices[i+k] < quantDn[i+k]) bufferDn[i]+= sign*tick_volume[i+k]*prices[i+k]*atr;
                }
                else
                {
                   if (prices[i+k] > quantUp[i+k]) bufferUp[i]+= sign*volume[i+k]*prices[i+k]*atr;
                   if (prices[i+k] < quantDn[i+k]) bufferDn[i]+= sign*volume[i+k]*prices[i+k]*atr;
                }               
          }
          if (LimitToZeroes)
          {
             bufferUp[i] = MathMax(bufferUp[i],0);
             bufferDn[i] = MathMin(bufferDn[i],0);
          }         
       }
       return(0);
    }
    
    //+------------------------------------------------------------------+
    //|                                                                  |
    //+------------------------------------------------------------------+
    //
    //
    //
    //
    //
    
    double quantileArray[];
    double iQuantile(int period, double qp, int i)
    {
       if (ArraySize(quantileArray)!=period) ArrayResize(quantileArray,period);
                      for(int k=0; k<period && (i+k)<Bars; k++) quantileArray[k] = prices[i+k];
           ArraySort(quantileArray);
    
       //
       //
       //
       //
       //
       
       double index = (period-1)*qp/100.00;
       int    ind   = index;
       double delta = index - ind;
       if (ind == NormalizeDouble(index,5))
             return(            quantileArray[ind]);
       else  return((1.0-delta)*quantileArray[ind]+delta*quantileArray[ind+1]);
    }
    quantile.png quantile.png Quantile-based-signed-volume-analysis-1.1.mq4
    #112938 quote
    NicolasNicolas
    Keymaster
    Legend

    Intentaremos revisar esa conversión de código la próxima semana. ¡Por favor recuérdame si no lo hago!

    #113321 quote
    Fr7Fr7
    Participant
    Master

    Hola Nicolás,si tiene tiempo libre recuerde hacer el código.

    GRACIAS

    #114384 quote
    Fr7Fr7
    Participant
    Master

    Nicolás,por favor no se olvide de mí y si tiene tiempo libre ayudeme con el código.GRACIAS

    #118715 quote
    Fr7Fr7
    Participant
    Master

    Nicolás,por favor sé que está muy liado perovsi tiene tiempo libre ayúdeme con el código.GRACIAS

    #118726 quote
    NicolasNicolas
    Keymaster
    Legend

    En realidad, hay 2 limitaciones principales que podrían resolverse con PRT v11:

    1. un cálculo más fácil se haría con el soporte de matrices de variables
    2. tick_volume que no conocemos con códigos pero que posiblemente podría calcularse aproximadamente en gráficos de ticks y con el nuevo soporte de matrices con la versión 11 (tenga en cuenta que no pudimos obtener el historial y solo en la vela actual)
    #143098 quote
    Fr7Fr7
    Participant
    Master

    Hola Nicolás ,ahora que está la versión PRT v11……¿Podría realizar el indicador?GRACIAS

    #143113 quote
    NicolasNicolas
    Keymaster
    Legend

    Sí, pero el problema principal es la clasificación de matrices, que no es posible fácilmente. En los próximos meses se agregarán muchas instrucciones nuevas a ProBuilder, y con una funcionalidad ArraySort.

    jonpt88 thanked this post
Viewing 8 posts - 1 through 8 (of 8 total)
  • You must be logged in to reply to this topic.
ProRealAI ProRealAI New

Stuck on this ProBuilder code?

Describe what this topic is trying to build, in plain English, and ProRealAI writes the ProRealTime™ indicator, screener or system for you.

Available in 7 languages
Try ProRealAI

Traducir de mq4 a PRT:"Quantile based signed volume analysis"


ProBuilder: Indicadores y Herramientas

New Reply
Author
author-avatar
Fr7 @fr7 Participant
Summary

This topic contains 7 replies,
has 2 voices, and was last updated by NicolasNicolas
6 years, 1 month ago.

Topic Details
Forum: ProBuilder: Indicadores y Herramientas
Language: Spanish
Started: 11/15/2019
Status: Active
Attachments: 2 files
ProRealCode ProRealCode
Loading...
