

I need help with translate code from tradingview Pine

Viewing 9 posts - 1 through 9 (of 9 total)

  • Author
    Posts
  • #64375 quote
    daniel123321daniel123321
    Participant
    New

    Can somebody translate code from Pine to PRT, It’s a strategy code not that long.

    #64380 quote
    NicolasNicolas
    Keymaster
    Legend

    Topic moved to ProOrder support forum since it’s related to automatic trading. Please post the code here and I’ll have a look later, thank you.

    daniel123321 thanked this post
    #64408 quote
    daniel123321daniel123321
    Participant
    New

    One last question does the PRT backtest with hirstorical spread info, because TV only can add commission.. ?


    //@version=3
    strategy(shorttitle=”CTO stratrgy RISKLEVEL=1/2/3 (XAUUSD 4h Settings)RSI/FILTER”, title=”CTO”, overlay=true)

    //////RSI
    RSIlength = input(2,title=”RSI Period Length”)
    //we need oversold rsi cuz its better performing
    RSIoverSold = 50
    RSIoverBought40 = 40
    RSIoverBought50 = 50
    price = close
    vrsi = rsi(price, RSIlength)

    //////BBands
    src = input(ohlc4, title = “source”)
    len = input(224, title = “timeframe/# of periods”)
    e = ema(src,len)
    evar = (src – e)*(src – e)
    evar2 = (sum(evar,len))/len
    std = sqrt(evar2)
    Multiplier = input(1, minval = 0.01, title = “Multiplier”)
    upper = e + (Multiplier * std)
    lower = e – (Multiplier * std)
    //
    plot(e, color = aqua, linewidth = 1, title = “AQUA”)

    p1 = plot(upper, color=green)
    p2 = plot(lower, color=red)
    fill(p1, p2 ,purple)

    //STRATEGY with SL and TP-at opposite band not aqua tp
    //FILTER BUY
    length = input(title=”LSMABUYLength”, type=integer, defval=19)
    offset = input(title=”LSMASELLOffset”, type=integer, defval=0)
    src1 = input(close, title=”LSMA-BUYSource”)
    lsma = linreg(src1, length, offset)
    plot(lsma)

    //CONDITIONS
    source = lsma

    //MAP
    buyEntry = crossover(source, lower)
    sellEntry = crossunder(source, upper)
    takeProfitbuy = crossunder(source, e)

    //Strategy RR3

    //LONG ENTRY
    if crossover(source, lower)
    strategy.entry(“LE”, strategy.long, oca_type=strategy.oca.cancel, stop=lower, oca_name=”CTO”, comment=”LE”)
    //LONG S/L
    if (crossunder(source, lower))
    strategy.close(id=”LE”)
    //TAKE PROF LONG
    if (cross(source, e) and cross(vrsi, RSIoverSold)) or crossunder(source, upper)
    strategy.close(id=”LE”)

    //SHORT ENTRY
    if crossunder(source, upper)
    strategy.entry(“SE”, strategy.short, oca_type=strategy.oca.cancel, stop=upper, oca_name=”SE”, comment=”SE”)
    else
    strategy.cancel(id=”SE”)
    //SHORT S/L
    if (crossover(source, upper) and crossunder(vrsi, RSIoverBought50)) or (crossover(source,upper) and crossunder(vrsi,RSIoverBought40))
    strategy.close(id=”SE”)
    //TAKE PROF SHORT
    if (cross(source, e) and crossover(vrsi, RSIoverBought50)) or cross(source, lower)
    strategy.close(id=”SE”)
    //last idea buy tp fix


    //Strategy RR2

    //LONG ENTRY
    if crossover(source, lower)
    strategy.entry(“LE”, strategy.long, oca_type=strategy.oca.cancel, stop=lower, oca_name=”CTO”, comment=”LE”)
    //LONG S/L
    if (crossunder(source, lower))
    strategy.close(id=”LE”)
    //TAKE PROF LONG
    if (cross(source, e) and cross(vrsi, RSIoverSold)) or crossunder(source, upper)
    strategy.close(id=”LE”)

    //SHORT ENTRY
    if crossunder(source, upper)
    strategy.entry(“SE”, strategy.short, oca_type=strategy.oca.cancel, stop=upper, oca_name=”SE”, comment=”SE”)
    else
    strategy.cancel(id=”SE”)
    //SHORT S/L
    if (crossover(source, upper) and (vrsi < 50 ))
    strategy.close(id=”SE”)
    //TAKE PROF SHORT
    if (cross(source, e) and crossover(vrsi, 50 )) or cross(source, lower) or crossover(source, e)
    strategy.close(id=”SE”)


    //Strategy RR1

    //LONG ENTRY
    if crossover(source, lower)
    strategy.entry(“LE”, strategy.long, oca_type=strategy.oca.cancel, stop=lower, oca_name=”CTO”, comment=”LE”)
    //LONG S/L
    if (crossunder(source, lower))
    strategy.close(id=”LE”)
    //TAKE PROF LONG
    if (cross(source, e) and cross(vrsi, RSIoverSold)) or crossunder(source, upper)
    strategy.close(id=”LE”)

    //SHORT ENTRY
    if crossunder(source, upper) and (vrsi > 15)
    strategy.entry(“SE”, strategy.short, oca_type=strategy.oca.cancel, stop=upper, oca_name=”SE”, comment=”SE”)
    else
    strategy.cancel(id=”SE”)
    //SHORT S/L
    if crossover(source, upper)
    strategy.close(id=”SE”)
    //TAKE PROF SHORT
    if (cross(source, e) and crossover(vrsi, RSIoverBought50)) or cross(source, lower)
    strategy.close(id=”SE”)

    #64427 quote
    daniel123321daniel123321
    Participant
    New

    //@version=3
    strategy(shorttitle=”CTO stratrgy RISKLEVEL=4 (XAUUSD 4h Settings)DB/RSI/FILTER”, title=”CTO”, overlay=true)

    //////RSI
    RSIlength = input(2,title=”RSI Period Length”)
    //we need oversold rsi cuz its better performing
    RSIoverSold = 50
    RSIoverBought40 = 40
    RSIoverBought50 = 50
    price = close
    vrsi = rsi(price, RSIlength)

    //////BBands
    src = input(ohlc4, title = “source”)
    len = input(224, title = “timeframe/# of periods”)
    e = ema(src,len)
    evar = (src – e)*(src – e)
    evar2 = (sum(evar,len))/len
    std = sqrt(evar2)
    Multiplier = input(1, minval = 0.01, title = “Multiplier”)
    upper = e + (Multiplier * std)
    lower = e – (Multiplier * std)
    //
    plot(e, color = aqua, linewidth = 1, title = “AQUA”)

    p1 = plot(upper, color=green)
    p2 = plot(lower, color=red)
    fill(p1, p2 ,purple)

    //
    //////Detrend Breakout
    lengthdb = input(50),mult = input(2),vol = input(20)
    d = close – rma(close,lengthdb)
    cos = (cum(abs(d))/n) * mult
    upperdb = 0 + cos
    lowerdb = 0 – cos

    //STRATEGY with SL and TP-at opposite band not aqua tp
    //FILTER BUY
    length = input(title=”LSMABUYLength”, type=integer, defval=19)
    offset = input(title=”LSMASELLOffset”, type=integer, defval=0)
    src1 = input(close, title=”LSMA-BUYSource”)
    lsma = linreg(src1, length, offset)
    plot(lsma)

    //CONDITIONS
    source = lsma

    //MAP
    buyEntry = crossover(source,lower)
    sellEntry = crossunder(d,upper)
    takeProfitbuy = cross(source,e)
    takeProfitsell = crossunder(source,e)
    t = volume > sma(volume,vol)

    //LONG ENTRY
    if crossover(source, lower)
    strategy.entry(“LE”, strategy.long, oca_type=strategy.oca.cancel, stop=lower, oca_name=”CTO”, comment=”LE”)
    //LONG S/L
    if (crossunder(source, lower))
    strategy.close(id=”LE”)
    //TAKE PROF LONG
    if (cross(source, e) and cross(vrsi, RSIoverSold)) or crossunder(source, upper)
    strategy.close(id=”LE”)

    //SHORT ENTRY
    if crossunder(d,31) and t
    strategy.entry(“SE”, strategy.short, oca_type=strategy.oca.cancel, comment=”SE”)
    //SHORT S/L
    if (crossover(source, upper) and crossunder(vrsi, RSIoverBought50)) or (crossover(source,upper) and crossunder(vrsi,RSIoverBought40))
    strategy.close(id=”SE”)
    //TAKE PROF SHORT
    if cross(source, e)
    strategy.close(id=”SE”)

    anmoldavesar thanked this post
    #64670 quote
    NicolasNicolas
    Keymaster
    Legend

    Sorry but what is the good strategy to translate? The one from your last post?

    #64746 quote
    daniel123321daniel123321
    Participant
    New

    Last one yes. Its preforming better than RR 1/2 and 3.

    #64747 quote
    daniel123321daniel123321
    Participant
    New

    I have the base code of BB + LSMA for prt but I need to insert more right conditions like DB and RSI.

    // Définition des paramètres du code
    DEFPARAM CumulateOrders = False // Cumul des positions désactivé
    
    // Conditions pour ouvrir une position acheteuse
    indicator1 = LinearRegression[19](close)
    indicator2 = ExponentialAverage[224](close)-std[224](close)
    c1 = (indicator1 CROSSES OVER indicator2)
    
    IF c1 THEN
    BUY 1 SHARES AT MARKET
    ENDIF
    
    // Conditions pour fermer une position acheteuse
    indicator3 = LinearRegression[19](close)
    indicator4 = ExponentialAverage[224](close)
    c2 = (indicator3 CROSSES OVER indicator4)
    
    IF c2 THEN
    SELL AT MARKET
    ENDIF
    
    // Conditions pour ouvrir une position en vente à découvert
    indicator5 = LinearRegression[19](close)
    indicator6 = ExponentialAverage[224](close)+std[224](close)
    c3 = (indicator5 CROSSES UNDER indicator6)
    
    IF c3 THEN
    SELLSHORT 1 SHARES AT MARKET
    ENDIF
    
    // Conditions pour fermer une position en vente à découvert
    indicator7 = LinearRegression[19](close)
    indicator8 = ExponentialAverage[224](close)
    c4 = (indicator7 CROSSES UNDER indicator8)
    
    IF c4 THEN
    EXITSHORT AT MARKET
    ENDIF


    #64867 quote
    daniel123321daniel123321
    Participant
    New

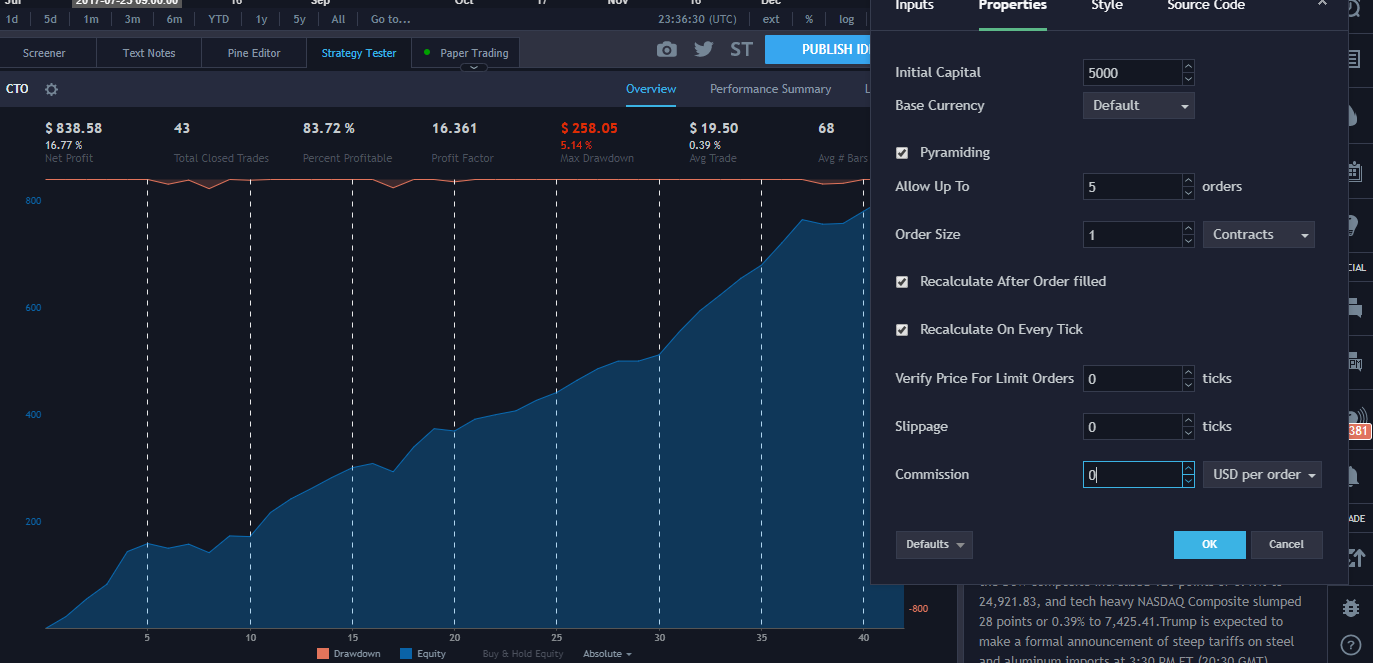
    4years backtest

    anmoldavesar thanked this post
    CTO-last.png CTO-last.png
    #90973 quote
    anmoldavesaranmoldavesar
    Participant
    New

    Can you please mail me this script.. or paste it here.. i am not able to copy properly to work on it. Thanks

Viewing 9 posts - 1 through 9 (of 9 total)
  • You must be logged in to reply to this topic.
ProRealAI ProRealAI New

Stuck on this ProBuilder code?

Describe what this topic is trying to build, in plain English, and ProRealAI writes the ProRealTime™ indicator, screener or system for you.

Available in 7 languages
Try ProRealAI

I need help with translate code from tradingview Pine


ProOrder: Automated Strategies & Backtesting

New Reply
Author
Summary

This topic contains 8 replies,
has 3 voices, and was last updated by anmoldavesaranmoldavesar
7 years, 9 months ago.

Topic Details
Forum: ProOrder: Automated Strategies & Backtesting
Language: English
Started: 03/04/2018
Status: Active
Attachments: 1 files
ProRealCode ProRealCode
Loading...
