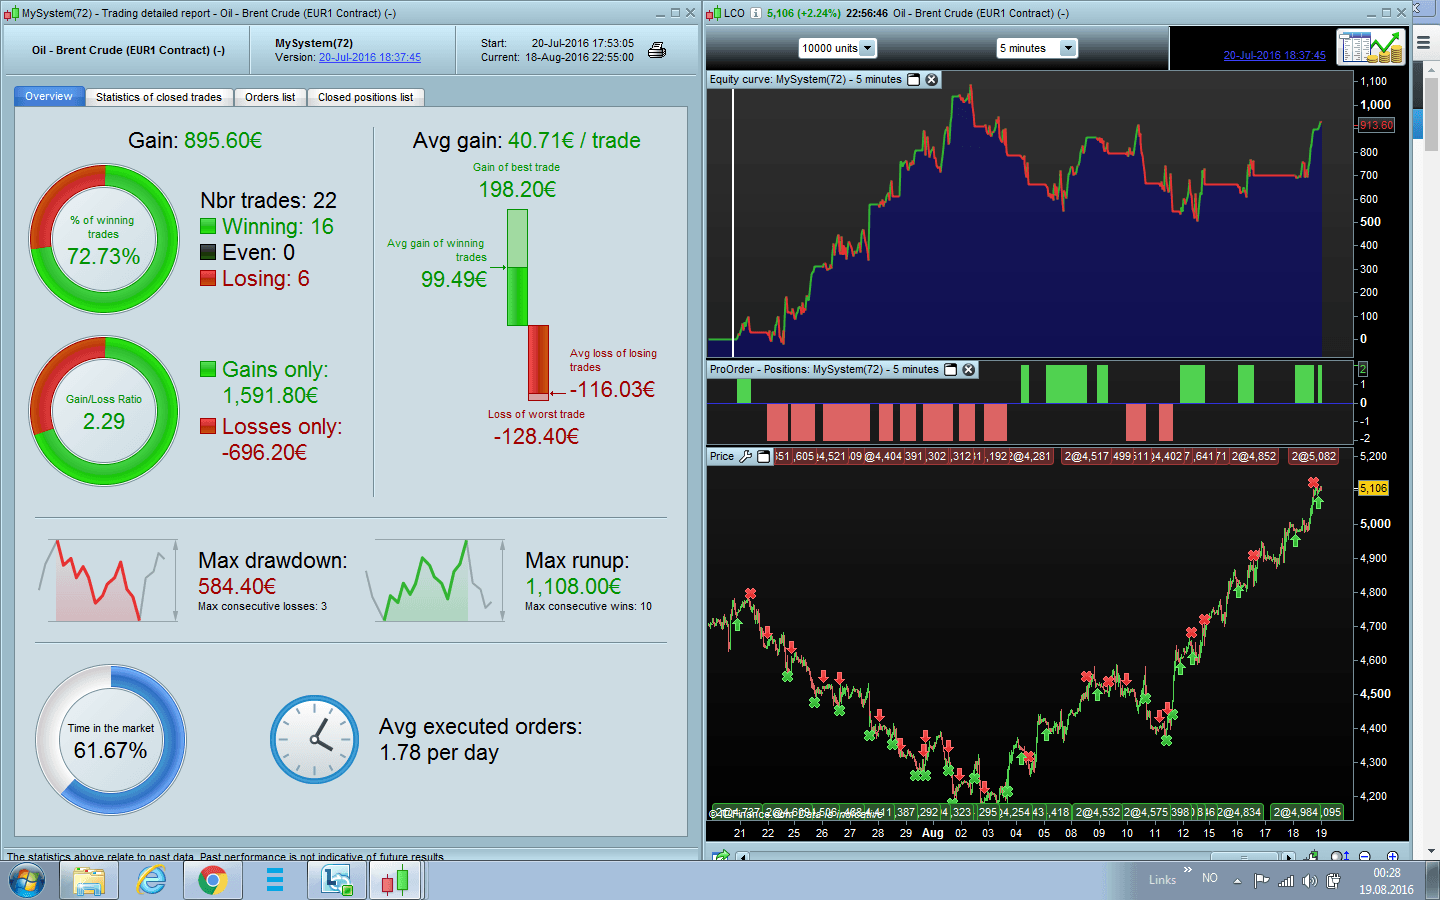
Hi..
I am new too this and are not so good to wrigh own codes.
I would like to share my strategy I am currently running live and hope someone can help me with a code to make it buy extra contract if I loose 2 in a row ect.
I tried to apply a martin gale code by my self but with no sucsess.
There were some code somewhere here that buys more contract when winning, i’m sure that could be changed to what you want. Here is the basic. I’m not finished with it yet as it has some non linear risks that needs to be adressed. Btw it was orginally
Grizzlys code.
MaxPositionA=100
Account=5000
Ratio=1
Equity = (Strategyprofit+account)

Risk = min(round(Ratio*Equity/100000)*1,MaxPositionA)

Losses = positionperf(1)<0 and positionperf(2)<0 and positionperf(3)<0
streak = positionperf(1)>0 and positionperf(2)>0 and positionperf(3)>0

if losses then
PositionSize  = max(abs(round(max(3+risk-2,risk-2))),2)
elsif not losses then
PositionSize  = max(abs(round(max(3+risk,risk))),2)
Endif
if streak then
PositionSize  = max(abs(round(max(5+risk,risk))),2)

Endif
posistin size is not working.
How do I change it so its for buy/sell contracts?
can someone help me with filling it in for me in my code?
or a martin gale code?
DEFPARAM CumulateOrders = False // Cumulating positions deactivated
//defparam flatbefore = 230000
//defparam flatafter = 065500
// Conditions to enter long positions
indicator1 = TimeSeriesAverage[29](close)
indicator2 = WilderAverage[66](close)
c1 = (indicator1 >= indicator2)
indicator3 = SMI[9,6,14](close)
c2 = (indicator3 CROSSES OVER -44)
IF c1 AND c2 THEN
BUY 2 CONTRACT AT MARKET
ENDIF
// Conditions to enter short positions
indicator4 = TimeSeriesAverage[10](close)
indicator5 = WilderAverage[86](close)
c3 = (indicator4 <= indicator5)
indicator6 = SMI[6,1,16](close)
c4 = (indicator6 >= 45)
IF c3 AND c4 THEN
SELLSHORT 2 CONTRACT AT MARKET
ENDIF
//************************************************************************
//trailing stop function
trailingstart = 34 //trailing will start @trailinstart points profit
trailingstep = 1 //trailing step to move the “stoploss”
//reset the stoploss value
IF NOT ONMARKET THEN
newSL=0
ENDIF
//manage long positions
IF LONGONMARKET THEN
//first move (breakeven)
IF newSL=0 AND close-tradeprice(1)>=trailingstart*pipsize THEN
newSL = tradeprice(1)+trailingstep*pipsize
ENDIF
//next moves
IF newSL>0 AND close-newSL>=trailingstep*pipsize THEN
newSL = newSL+trailingstep*pipsize
ENDIF
ENDIF
//manage short positions
IF SHORTONMARKET THEN
//first move (breakeven)
IF newSL=0 AND tradeprice(1)-close>=trailingstart*pipsize THEN
newSL = tradeprice(1)-trailingstep*pipsize
ENDIF
//next moves
IF newSL>0 AND newSL-close>=trailingstep*pipsize THEN
newSL = newSL-trailingstep*pipsize
ENDIF
ENDIF
//stop order to exit the positions
IF newSL>0 THEN
SELL AT newSL STOP
EXITSHORT AT newSL STOP
ENDIF
//************************************************************************
SET STOP ploss 78//78
SET TARGET pPROFIT 136//98
change:
IF c1 AND c2 THEN BUY 2 CONTRACT AT MARKET ENDIF
to
IF c1 AND c2 THEN BUY PositionSize CONTRACT AT MARKET ENDIF
and change
IF c3 AND c4 THEN SELLSHORT 2 CONTRACT AT MARKET ENDIF
to
IF c3 AND c4 THEN SELLSHORT PositionSize CONTRACT AT MARKET ENDIF
OK
thanks alot for the help
Can you please explain me how your Money management strategy works Elsborgtrading?
like risk= ? and how account works?
if it looses 3 in a row it will buy 5 contracts right ?
and if I change the
Risk = min(round(Ratio*Equity/100000)*1,MaxPositionA) from 100000 to lets say 100 I get a insane profit that I dont really understand since when I check the
orderlist it goes from lets say 5 and 10 contracts and then suddenly to 1000 contracts if I change
MaxPositionA=100 to 1000.

As I understand I tought it would go from lest say 5 contracts to 10 to 20 ect. depending on your account size. but with me it jumps really fast.
Better understanding if I just put my code up here:
//————————————————————————-
// Main code : MySystem(95)
//————————————————————————-
//————————————————————————-
// Main code : MySystem(65)
//————————————————————————-
//————————————————————————-
// Main code : MySystem(62)
//————————————————————————-
DEFPARAM CumulateOrders = False // Cumulating positions deactivated
//defparam flatbefore = 230000
//defparam flatafter = 065500
//MGT
MaxPositionA=1000
Account=1000
Ratio=1
Equity = (Strategyprofit+account)
Risk = min(round(Ratio*Equity/100)*1,MaxPositionA)
Losses = positionperf(1)<0 and positionperf(2)<0 and positionperf(3)<0
streak = positionperf(1)>0 and positionperf(2)>0 and positionperf(3)<0
if losses then
PositionSize = max(abs(round(max(2+risk-2,risk-2))),2)
elsif not losses then
PositionSize = max(abs(round(max(2+risk,risk))),2)
Endif
if streak then
PositionSize = max(abs(round(max(5+risk,risk))),2)
Endif
// Conditions to enter long positions
indicator1 = TimeSeriesAverage[29](close)
indicator2 = WilderAverage[66](close)
c1 = (indicator1 >= indicator2)
indicator3 = SMI[9,6,14](close)
c2 = (indicator3 CROSSES OVER -44)
IF c1 AND c2 THEN
BUY PositionSize CONTRACT AT MARKET
ENDIF
// Conditions to enter short positions
indicator4 = TimeSeriesAverage[10](close)
indicator5 = WilderAverage[86](close)
c3 = (indicator4 <= indicator5)
indicator6 = SMI[6,1,16](close)
c4 = (indicator6 >= 45)
IF c3 AND c4 THEN
SELLSHORT PositionSize CONTRACT AT MARKET
ENDIF
//************************************************************************
//trailing stop function
trailingstart = 34 //trailing will start @trailinstart points profit
trailingstep = 1 //trailing step to move the “stoploss”
//reset the stoploss value
IF NOT ONMARKET THEN
newSL=0
ENDIF
//manage long positions
IF LONGONMARKET THEN
//first move (breakeven)
IF newSL=0 AND close-tradeprice(1)>=trailingstart*pipsize THEN
newSL = tradeprice(1)+trailingstep*pipsize
ENDIF
//next moves
IF newSL>0 AND close-newSL>=trailingstep*pipsize THEN
newSL = newSL+trailingstep*pipsize
ENDIF
ENDIF
//manage short positions
IF SHORTONMARKET THEN
//first move (breakeven)
IF newSL=0 AND tradeprice(1)-close>=trailingstart*pipsize THEN
newSL = tradeprice(1)-trailingstep*pipsize
ENDIF
//next moves
IF newSL>0 AND newSL-close>=trailingstep*pipsize THEN
newSL = newSL-trailingstep*pipsize
ENDIF
ENDIF
//stop order to exit the positions
IF newSL>0 THEN
SELL AT newSL STOP
EXITSHORT AT newSL STOP
ENDIF
//************************************************************************
SET STOP ploss 78//78
SET TARGET pPROFIT 136//98
You should not change those numbers. If any only the ratio in steps of 5 for every 15000 gain. You will at some point blow your account because you will be gambling with almost everything every time. a small negative P/L will result in a margin call and your positions will be automatic closed. I don’t understand fully the money management code as it’s not linear (equity vs risk), but yes when you win 3 times it will adjust for more contracts. Problem is if you run this code with only 1000 euro to start with (account=1000) you will be almost gambling with 7,8% every time you trade ONE contract with a SL at 78. two position will double your gambling risk.
so if you change the risk factor from 100000 to 100 and maxposition to 1000, you will get insane profit, but only in the backtest. 2 lost trades IRL you will blow your account.
Risk = min(round(Ratio*Equity/100000)*1,MaxPositionA)
in fact I would consider lower the risk like this, however it’s up to you what you want to gamble with, so you can play with the numbers as you see the difference.
MaxPositionA=100
Account=5000
Ratio=1
Equity = (Strategyprofit+account)

Risk = min(round(Ratio*Equity/100000)*1,MaxPositionA)

Losses = positionperf(1)<0 and positionperf(2)<0 and positionperf(3)<0
streak = positionperf(1)>0 and positionperf(2)>0 and positionperf(3)>0

if losses then
PositionSize  =max(ABS(round(max(1+Risk-2,Risk-2))),1)
elsif not losses then
PositionSize  =max(ABS(round(max(2+Risk,Risk))),2)
endif
if streak then
PositionSize  = max(abs(round(max(3+risk,risk))),2)
Endif
If i whant the code to.buy after two losses do i just take away the last postionperf on each line on.loss and streak and the last risk on each line on positionsize?
google have a max loss in a row of two.according my.backtest last 9 months
I’m not sure I understand you- you alway buy 😛 but from you orginal post you want to buy extra contract if loose 2 times? But still you are “
curve Fitting” you don’t know if this will be the case in the future. I’s better to play it safe.
anyway I think it will be this
MaxPositionA=100
Account=5000
Ratio=1
Equity = (Strategyprofit+account)

Risk = min(round(Ratio*Equity/100000)*1,MaxPositionA)

Losses = positionperf(1)<0 and positionperf(2)<0
streak = positionperf(1)>0 and positionperf(2)>0 and positionperf(3)>0

if losses then
PositionSize  =max(abs(round(max(5+risk,risk))),2)
elsif not losses then
PositionSize  =max(ABS(round(max(2+Risk,Risk))),2)
endif
if streak then
PositionSize  = max(abs(round(max(3+risk,risk))),2)
Endif
Nicolas also made another MM code, that keeps betting more when you win. you can try it out
Capital = 10000
Risk = 0.01
StopLoss = 10 // Could be our variable XREM Calculate contracts
equity = Capital + StrategyProfit
maxrisk = round(equity*Risk)
PositionSize = abs(round((maxrisk/StopLoss)/PointValue)*pipsize)
Thanks alot.
You just did what i tought I had too do.
But still wonder is streak the same in.the code you wrote that if win 3 in a row you buy 3 contracts.
If looses 2 in a row i buy 5 contracts and
Elsif not looses it will buy standard 2 contracts?
Sorry for all the questions.
It have been to great help
Hi Kenneth 🙂
well the intended and initial code was to add more contracts if you win 3 times in a row. actually for 5 contracts. if you loose 3 times in a row it will down scale to 1 contract and or else use 3 contracts. But I think that was a bit risky if you only had a 1000 Euro account to begin with, so I change it a bit. But really you can change the code for what ever fits your riskprofile. then you wanted to add more if you loose 2 times, so I change the “losses” variable to only have 2 periods. it is easy spotted if you compare the “streak” variable. Then I took the equation from the ” if streak then” test and added a 5, so you would have more contracts if you loose 2 times in a row( this equation was the original from the “if streak then” test) The contracts would be increased along with your gain which is your “Equity” variable. How ever I found out that this process was not linear. I will add a excel spreadsheet that will show you the curve for risk vs equity. and you can also play with the numbers and see how many contracts vs. equity you will get. It will also give you an idea of how much you are risking- and to be honest It is really a lot you would risk unless you start out with a 30000 euro account. So in this process of finding out the risk management code, I must say that if I was to trade with live money I would start out with 1 fixed contract to see where it would take me, and then I would consider using the code Nicholas made, because here you have to earn you right to add more contract, where this is not the case here.
Cheers Kasper