






Dax M5 - Ichimoku strategy with 3 timeframes
Hello,
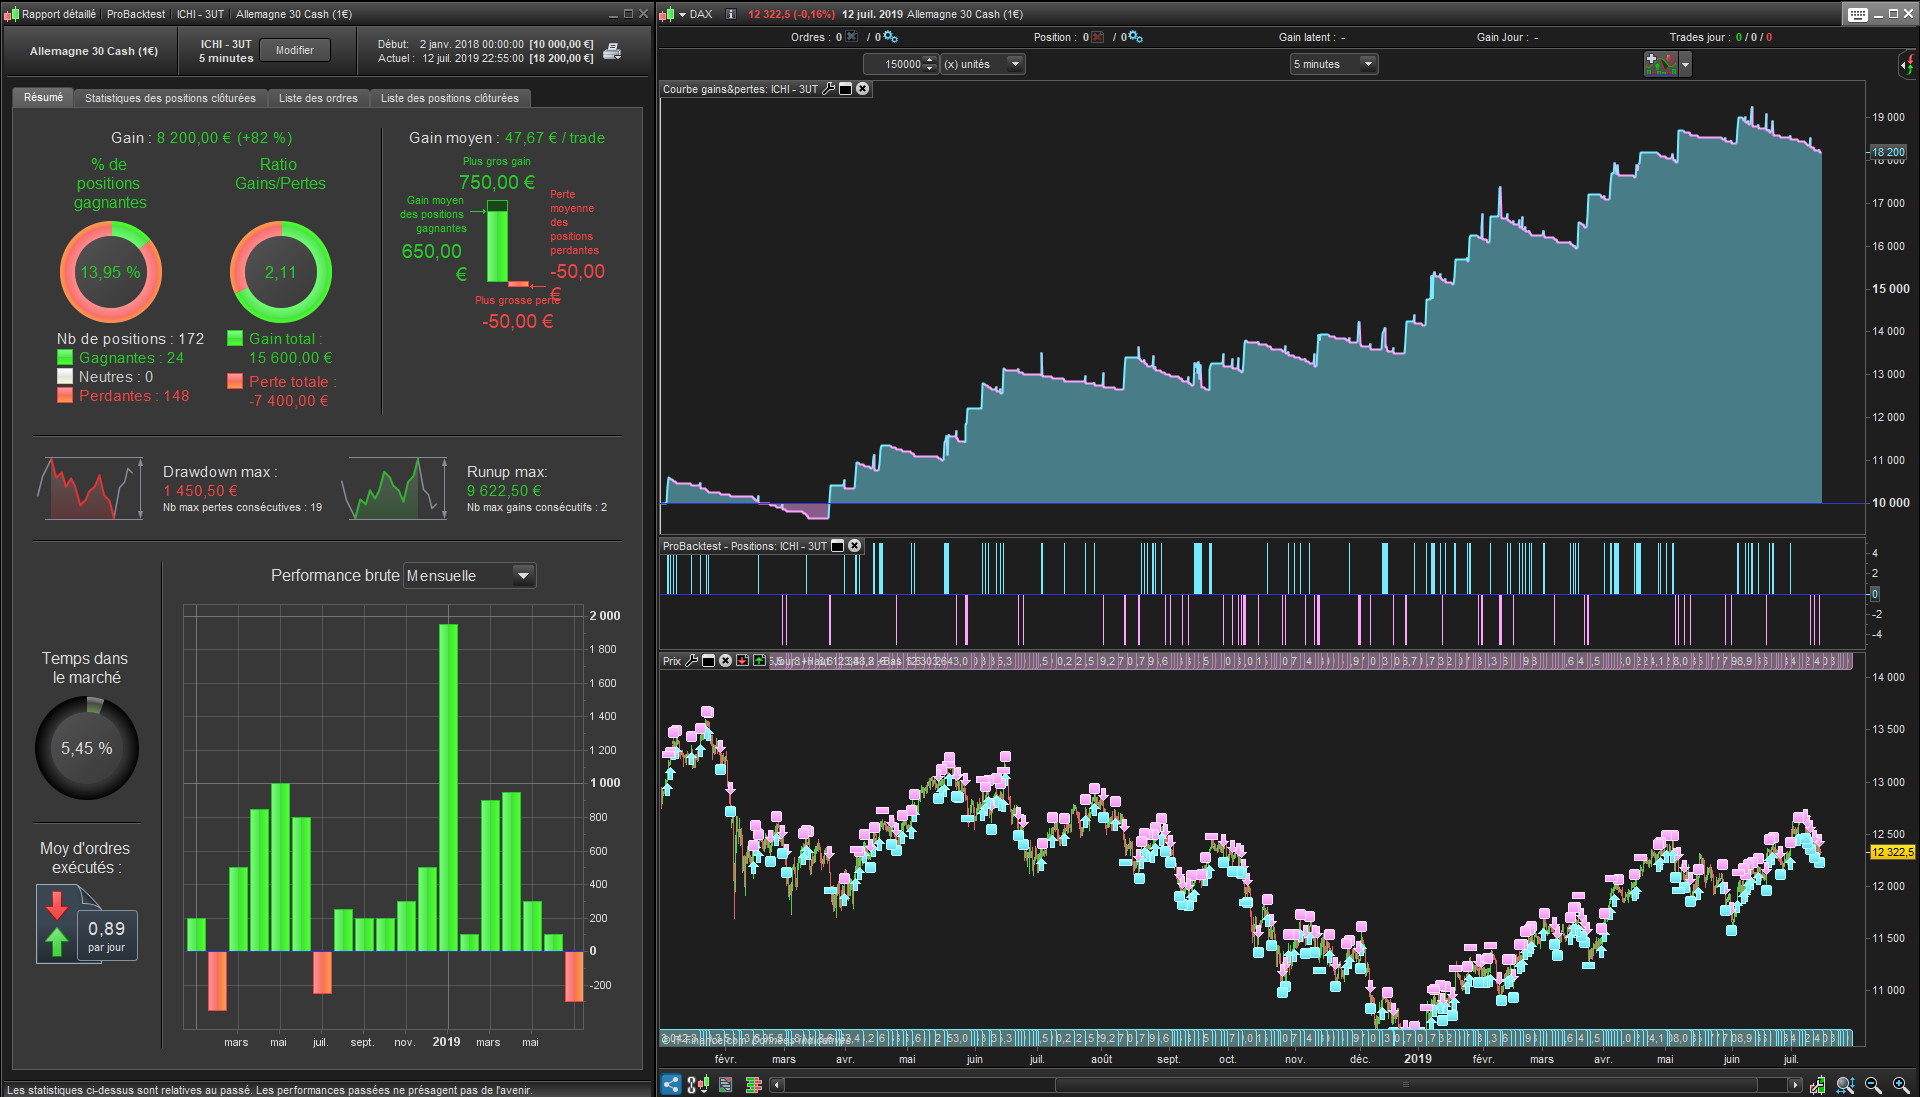
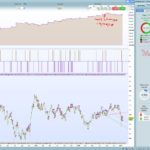
I share my first strategy. Ichimoku is fashionable actually. So I tried to parameter a strategy on the Dax in m5 with a filter on UT, m15 and H1.
Taking losses and letting go of your winnings is the idea for TP and SL management.
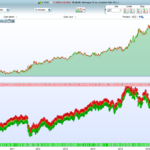
The leverage is 5×1 € and a spread of 2. Test from January 2018 to now.
Good test and thank you for your feedback.
(google traduction, je suis français)
DEFPARAM CumulateOrders = false
DEFPARAM Preloadbars = 3000

// TAILLE DES POSITIONS

n = 5

// HORAIRES DE TRADING
TimeAchat = time >= 080500 and time < 152500
TimeVente = time >= 080500 and time < 152500


TIMEFRAME(60 minutes)

// INDICATEURS
Tenkansen1 = (highest[9](high)+lowest[9](low))/2
Kijunsen1 = (highest[26](high)+lowest[26](low))/2
SSpanA1 = (tenkansen1[26]+kijunsen1[26])/2
SSpanB1 = (highest[52](high[26])+lowest[52](low[26]))/2
Chikou1 = close

//////////////
// POSITION KUMO

// ACHAT
ca1m60 = (close > SSpanA1 and SSpanA1 > SSpanB1) or (close > SSpanB1 and SSpanB1 > SSpanA1)

// VENTE
cv1m60 = (close < SSpanA1 and SSpanA1 < SSpanB1) or (close < SSpanB1 and SSpanB1 < SSpanA1)

///////////////

// POSITION CHIKOU

// ACHAT
ca2m60 = Chikou1 > SSpanA1[26] and Chikou1 > SSpanB1[26]

// VENTE
cv2m60 = Chikou1 < SSpanA1[26] and Chikou1 < SSpanB1[26]

//////////////

TIMEFRAME(15 minutes)

// INDICATEURS
Tenkansen2 = (highest[9](high)+lowest[9](low))/2
Kijunsen2 = (highest[26](high)+lowest[26](low))/2
SSpanA2 = (tenkansen2[26]+kijunsen2[26])/2
SSpanB2 = (highest[52](high[26])+lowest[52](low[26]))/2
chikou2 = close

//////////////
// POSITION KUMO

// ACHAT
ca1m15 = (close > SSpanA2 and SSpanA2 > SSpanB2) or (close > SSpanB2 and SSpanB2 > SSpanA2)

// VENTE
cv1m15 = (close < SSpanA2 and SSpanA2 < SSpanB2) or (close < SSpanB2 and SSpanB2 < SSpanA2)

///////////////

// POSITION CHIKOU

// ACHAT
ca2m15 = Chikou2 > SSpanA2[26] and Chikou2 > SSpanB2[26]

// VENTE
cv2m15 = Chikou2 < SSpanA2[26] and Chikou2 < SSpanB2[26]

//////////////

TIMEFRAME(5 minutes)

IF intradaybarindex=0 then
 toto=0
ENDIF

// INDICATEURS
Tenkansen3 = (highest[9](high)+lowest[9](low))/2
Kijunsen3 = (highest[26](high)+lowest[26](low))/2
SSpanA3 = (tenkansen3[26]+kijunsen3[26])/2
SSpanB3 = (highest[52](high[26])+lowest[52](low[26]))/2


//////////////
// POSITION KUMO

// ACHAT
ca1m5 = (close > SSpanA3 and SSpanA3 > SSpanB3) or (close > SSpanB3 and SSpanB3 > SSpanA3)

// VENTE
cv1m5 = (close < SSpanA3 and SSpanA3 < SSpanB3) or (close < SSpanB3 and SSpanB3 < SSpanA3)

///////////////

// POSITION CHIKOU

// ACHAT
ca2m5 = close>SSpanA3 and close>SSpanB3 and close CROSSES OVER Kijunsen3 and close > Tenkansen3

// VENTE
cv2m5 = close<SSpanA3 and close<SSpanB3 and close CROSSES UNDER Kijunsen3 and close < Tenkansen3

//////////////

achat = (ca1m60 and ca2m60 and ca1m15 and ca2m15 and ca1m5 and ca2m5)
vente = (cv1m60 and cv2m60 and cv1m15 and cv2m15 and cv1m5 and cv2m5)

//////////////

IF achat and TimeAchat and not onmarket and toto=0 THEN
 toto=1
 Buy n shares at market
 SET STOP pLOSS 10
 SET TARGET pPROFIT 120
ENDIF

IF vente and TimeVente and not onmarket and toto=0 THEN
 toto=1
 Sellshort n shares at market
 SET STOP pLOSS 10
 SET TARGET pPROFIT 150
ENDIF

Comments
You must be logged in to post a comment.


So far so good. After a long drawdown it was winning four times in five weeks. Since 24 july, 46 trades, 4 wins, 42 losses. Worst trade was almost 4 times the average I guess because of a weekend gap so could have gone the other way too. 8,7% winrate, 1.18 G/L. It has 15 losers in a row now so statistically it should take one home soon. It was really close to taking another win but instead it went down to a loss. I know Grahal thinks one should help the bots sometimes and maybe here I should have done that. In anyway, it looks good so far to me. I am also running a variant on OMX but that one has a different stop loss approach and is much more in market unfortunately. It is profitable so far though, but needs more time to tell cause it doesn't take trade

Since july 24th it's doing well. Started with a longer drawdown than expected but now it's 12% win rate and 1.77 G/L . It's had 4 of those big winners. I've tried finding other instruments to try it on but no luck so far. I've tried one on OMX30 and although the gain/loss came out similar it's 60% time in market so doesn't feel as neat.
I liked the idea so much I put it early into live and it took 19 straight losses before hitting a win. So far 5% win with G/L of 0.62, but it also has an open position in profit today so if we're lucky it breaks profitable today. Looking at back tests I managed to set it live right after a win and before the regular drawdown which turned out longer than previous ones. I like the strategy so I have faith and will let it run for now.

Immagini https://ibb.co/52sBK5j https://ibb.co/0DTVjcB https://ibb.co/02HKRs0
Hello everyone, I allowed myself to change TP and SL and the results are really good on 200k bars. IF achat and Time Chat and not onmarket and toto = 0 THEN toto = 1 Buy n shares at market SET STOP pLOSS 62 SET TARGET pPROFIT 150 ENDIF IF vente and TimeVente and not onmarket and toto = 0 THEN toto = 1 Sellshort n shares at market SET STOP pLOSS 16 SET TARGET pPROFIT 274 ENDIF Check it out.





Any hints for us, on which variables we should be optimising ? As of November 2020, the current settings make big losses, Thanks