





DAX Donchian breakout Aktivator 1 hour
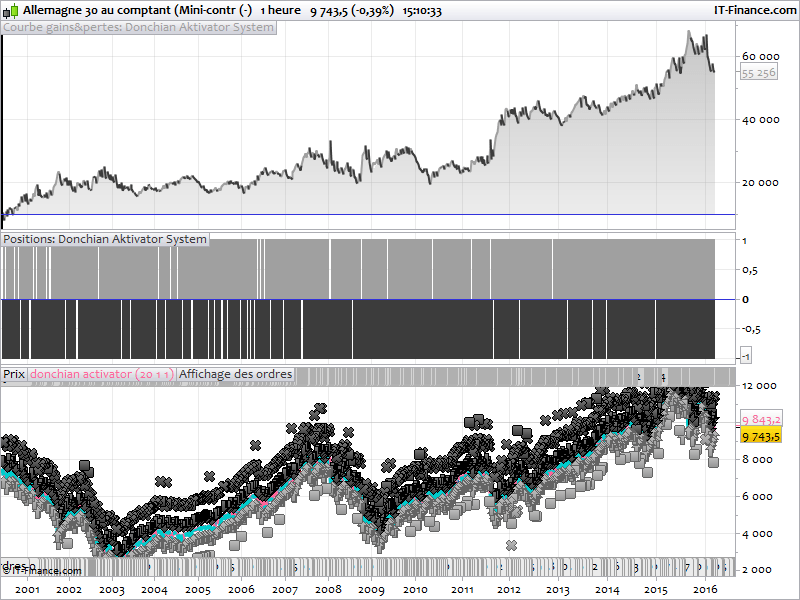
This automatic trading strategy on DAX GER30 is made of the indicator “Donchian Channel Activator Factor” available in the Library here : http://www.prorealcode.com/prorealtime-indicators/donchian-channel-activator-factor/
This system is a simple one, based on breakout of the recent highest or lowest on a 1 hour timeframe. Each trade has a stoploss made of the difference from the current close to last indicator value (upper or lower channel).
Test were made with 1 point spread, on mini-DAX CFD from ProRealTime-Trading.
//parameters
pd = 20
Factor = 1
ot = 1

//indicators
hi = HIGHEST[pd](high)[ot]
lo = LOWEST[pd](low)[ot]
DUpper=hi+Factor*AverageTrueRange[pd](close)
DLower=lo-Factor*AverageTrueRange[pd](close)

// case BUY
IF NOT LongOnMarket AND Close>hi AND Close[1]<hi THEN
  BUY 1 CONTRACTS AT MARKET
  stoploss = close-DLower
ENDIF

// exit BUY position
If LongOnMarket AND Close<lo THEN
  SELL AT MARKET
ENDIF

//case SELL
IF NOT ShortOnMarket AND Close<lo AND Close[1]>lo THEN
  SELLSHORT 1 CONTRACTS AT MARKET
  stoploss = DUpper-close
ENDIF

// exit SELL position
IF ShortOnMarket AND Close>hi THEN
  EXITSHORT AT MARKET
ENDIF

SET STOP LOSS stoploss
Comments
You must be logged in to post a comment.
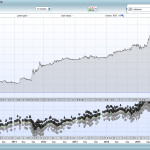
FR/Bonjour Steftonio, non pas de frais overnight calculé sur la durée du backtest, c'est une bonne remarque. Le backtest est réalisé sur 15 ans parce qu'il démontre que si cette stratégie intraday ne ruine pas le compte durant toute cette période (hors frais annexes donc), c'est parce qu'elle semble avoir du sens et qu'elle mérite qu'on s'y attarde : un breakout des derniers plus haut/plus bas semblent avoir fonctionné durant 15 ans (!). Les codes de la library sont fournis "as is / telle quelle" et ne sont pas un encouragement à les trader les yeux fermés, que ce soit un indicateur ou une stratégie. Bref j'ai trouvé une stratégie "sympa" que j'ai partagé, "go on next one!" Merci de ton inscription. EN/ Hello Steftonio, not overnight fee calculated on the duration of the backtest, it's a good point. The backtest is conducted over 15 years because it demonstrates that if the intraday strategy does not ruin the account during this period (excluding charges so), it is because it seems to make sense and deserves that 'further attention: a recent breakout above / below seem to have worked for 15 years (!). the library of codes are provided "as is / as is" and are not an encouragement to the trader eyes closed, either an indicator or strategy. In short I found a "nice" strategy that I shared, "we go next one!" Thank you for your registration.

Bonjour,
merci à Nicolas de proposer ces systèmes de trading sous PRT. Une question : est-ce-que le backtest prend en compte les frais overnight et si oui de quelle manière?
Ne penses-tu pas que les frais overnight ne peuvent pas annihiler les résultats du backtest sur d'aussi longues périodes (ici depuis 15 ans!!)?
Any reason why in 2016 this system is doing very bad respect the previous years?