

Weight averaged ADXR strategy

Viewing 11 posts - 1 through 11 (of 11 total)
  • Author
    Posts
  • #51604 quote
    gabrigabri
    Participant
    Master

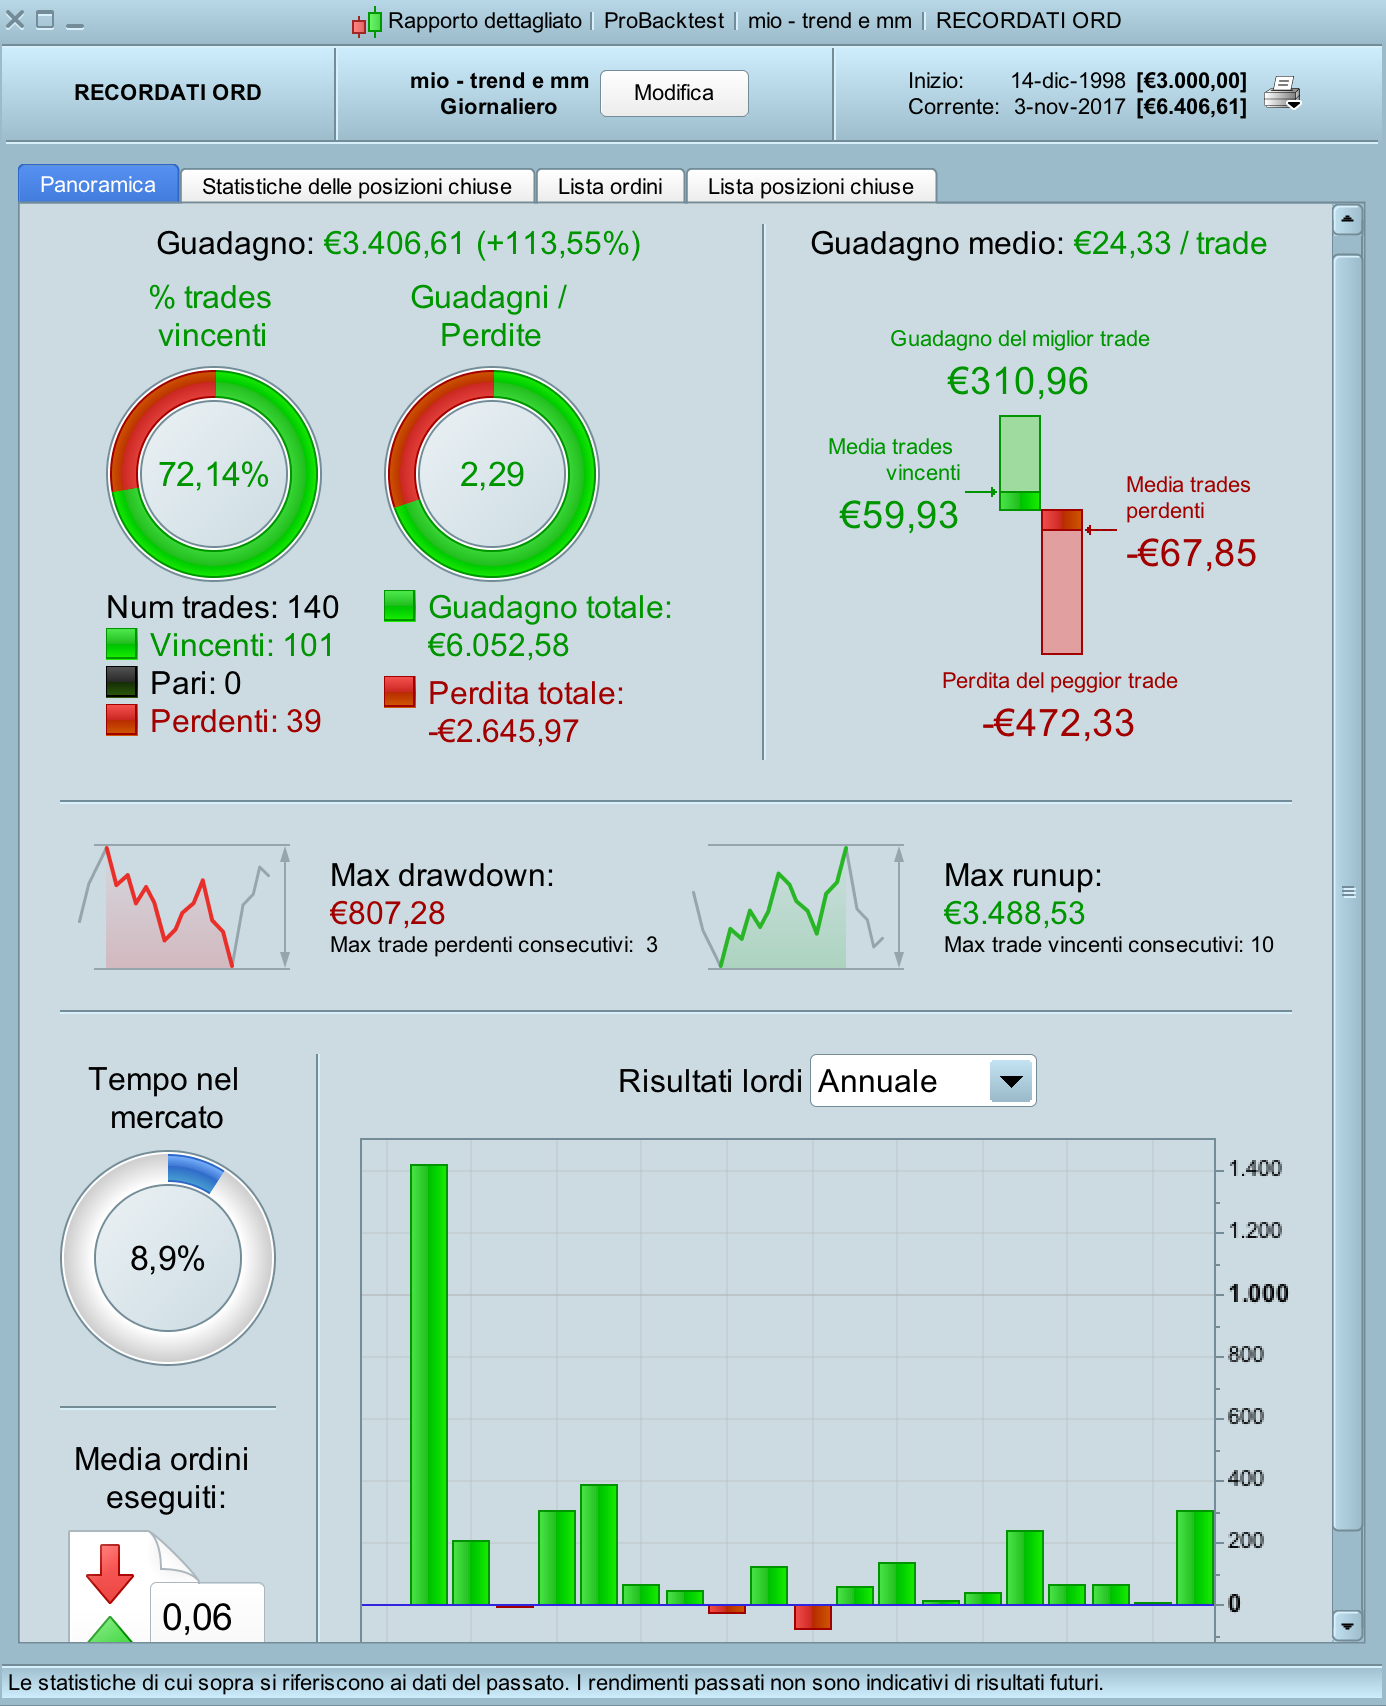
    This strategy is based on the modified version of the Directional Movement indicator I posted here. The strategy has to be backtested but it always gives above 70% of winning trades with a decent gain/loss ratio. The average gain per trade can be improved by changing the stop loss and the ADXR threshold.

    Blue skies.

    //tipomm=2
    //x=5 - I normally use a number between 5 and 10
    DEFPARAM CumulateOrders = False 
    
    // Entering long
    ignored, ignored, mioDI, ignored, mioADXR, ignored = CALL "PRT - ADX e DI"[14, 2]
    c1 = (mioADXR > 50)
    c2 = (mioDI > 0)
    
    IF c1 AND c2 THEN
    BUY 3000 CASH AT average[x,tipomm](low) limit
    ENDIF
    
    // Exiting long
    
    IF longonmarket THEN
    SELL AT average[x,tipomm](high) limit
    ENDIF
    set stop %loss 15
    Nicolas thanked this post
    trend-e-mm-1509956523c48pl.png trend-e-mm-1509956523c48pl.png PRT-ADX-e-DI-1.itf
    #51631 quote
    NicolasNicolas
    Keymaster
    Legend
    Hi Gabri, thanks for your contribution for the benefit of everyone here! About this specific strategy, I’d like to know a little more: _ what instrument, spread and / or fees? _ what timeframe? _ optimized settings: did you try WFA?
    #51652 quote
    gabrigabri
    Participant
    Master
    Nicolas, I use stocks (italian, german and french), daily timeframe and no spread on the strategy I posted. I used this system for several months in real trading (manual) and got always more than 70% winning trades and better gain/loss ratios than the one published. I didn’t WFA.   Gabri
    #51655 quote
    NicolasNicolas
    Keymaster
    Legend
    Fine!, but how do you define what stocks should be a good candidate to be traded by the strategy?
    #51666 quote
    gabrigabri
    Participant
    Master
    I pick stocks with high CSI or ADXR. I take this data from the indicator I posted.
    #51667 quote
    NicolasNicolas
    Keymaster
    Legend
    I made some backtests and I found it works way better with a major trend filter, since this is a long only strategy with a sorta ‘mean reversion’ theory, what do you think? (trading only if Close>Average[100-200] ..).
    #51673 quote
    gabrigabri
    Participant
    Master
    Nicolas, I was using it just for small and short trades and I am sure that there are better way to use it. Every input is more than welcome. How would you code it with your system?
    #51682 quote
    NicolasNicolas
    Keymaster
    Legend
    I coded it this way: (trendperiod is an optimized variable), a 100 days period is a good compromise between performance and trades quantity..
    DEFPARAM CumulateOrders = False
    
    tipomm=2
    x=5 //I normally use a number between 5 and 10
    
    
    // Entering long
    ignored, ignored, mioDI, ignored, mioADXR, ignored = CALL "Mio - ADX e DI"[14, 2]
    c1 = (mioADXR > 50)
    c2 = (mioDI > 0)
    c3 = close>average[trendperiod](close)
    
    IF c1 AND c2 and c3 THEN
    BUY 3000 CASH AT average[x,tipomm](low) limit
    ENDIF
    
    // Exiting long
    
    IF longonmarket THEN
    SELL AT average[x,tipomm](high) limit
    ENDIF
    set stop %loss 15
    #51728 quote
    gabrigabri
    Participant
    Master
    Nicolas, I think your addition it’s quite interesting but I personally think that launching a screener first (CSI or ADXR) and then running the code on the first 10-15 stocks of the list (building a portfolio) has better results. I quickly tested your version on a portfolio and seems to be carrying lower profits. I like the fact though that you have better gain per trade. Gabriele
    #51729 quote
    NicolasNicolas
    Keymaster
    Legend
    Ok 👌 What about the rebalancing of the portfolio made with this kind of stocks pick?
    #51732 quote
    gabrigabri
    Participant
    Master
    Good question. I don’t use too much this system anymore but I used to rebalance weekly. I always keep between 20 to 35 stocks in a short trading portfolio. When I sell I am not rushed to find a new stock to replace the old. I just run this screener (or some other screener focused on short term trading) once a week and if I find a good stock I add it.
Viewing 11 posts - 1 through 11 (of 11 total)
  • You must be logged in to reply to this topic.
ProRealAI ProRealAI New

Stuck on this ProBuilder code?

Describe what this topic is trying to build, in plain English, and ProRealAI writes the ProRealTime™ indicator, screener or system for you.

Available in 7 languages
Try ProRealAI

Weight averaged ADXR strategy


ProOrder: Automated Strategies & Backtesting

New Reply
Author
author-avatar
gabri @gabri Participant
Summary

This topic contains 10 replies,
has 2 voices, and was last updated by gabrigabri
8 years, 10 months ago.

Topic Details
Forum: ProOrder: Automated Strategies & Backtesting
Language: English
Started: 11/06/2017
Status: Active
Attachments: 2 files
ProRealCode ProRealCode
Loading...
