where in the code does it calculate the ‘positionsize’ for which PositionSizeLong and PositionSizeShort are derived?
At line 7 you can have positionsize = any value you like. With MM= 0 it won’t change.
// VECTORIAL MM - DJ 3m
DEFPARAM CumulateOrders = false
DEFPARAM Preloadbars = 50000
//Money Management
MM = 0 // = 0 for optimization
if MM = 0 then
positionsize=.5
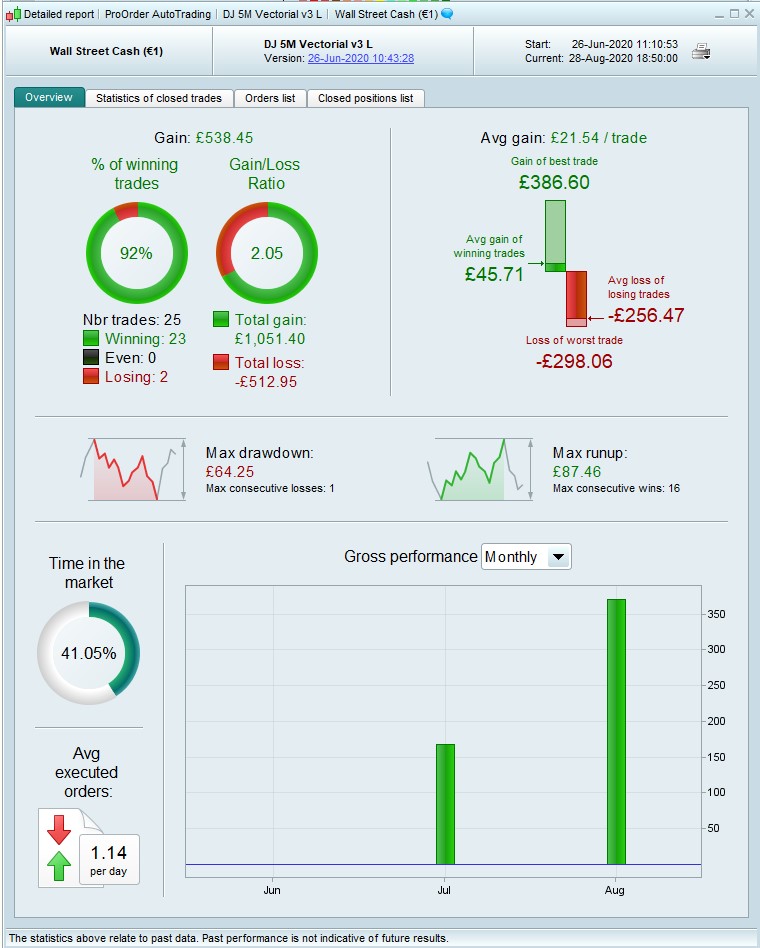
I have been running a 5m long version of this over the past couple of months. It’s basically a merger between Vectorial and MoD, so far fairly consistent with the back test.
DEFPARAM CumulateOrders = false
DEFPARAM Preloadbars = 50000
//Money Management
MM = 1 // = 0 for optimization
if MM = 0 then
positionsize=.5
ENDIF
if MM = 1 then
ONCE startpositionsize = .5
ONCE factor = 10 // factor of 10 means margin will increase/decrease @ 10% of strategy profit; factor 20 = 5% etc
ONCE margin = (close*.005) // tier 1 margin value of 1 contract in instrument currency; change decimal according to available leverage
ONCE margin2 = (close*.01)// tier 2 margin value of 1 contract in instrument currency; change decimal according to available leverage
ONCE tier1 = 55 // IG first tier margin limit
ONCE maxpositionsize = 550 //  IG tier 2 margin limit
ONCE minpositionsize = .2 // enter minimum position allowed
IF Not OnMarket THEN
positionsize = startpositionsize + Strategyprofit/(factor*margin)
ENDIF
IF Not OnMarket THEN
IF startpositionsize + Strategyprofit/(factor*margin) > tier1 then
positionsize = (((startpositionsize + (Strategyprofit/(factor*margin))-tier1)*(factor*margin))/(factor*margin2)) + tier1 //incorporating tier 2 margin
ENDIF
IF Not OnMarket THEN
if startpositionsize + Strategyprofit/(factor*margin) < minpositionsize THEN
positionsize = minpositionsize //keeps positionsize from going below allowed minimum
ENDIF
IF (((startpositionsize + (Strategyprofit/(factor*margin))-tier1)*(factor*margin))/(factor*margin2)) + tier1 > maxpositionsize then
positionsize = maxpositionsize// keeps positionsize from going above IG tier 2 margin limit
ENDIF
ENDIF
ENDIF
ENDIF

Ctime = time >= 010000 and time <= 230000

TIMEFRAME(2 hours)
Period= 240
inner = 2*weightedaverage[round( Period/2)](typicalprice)-weightedaverage[Period](typicalprice)
HULLa = weightedaverage[round(sqrt(Period))](inner)
c9 = HULLa > HULLa[1]
//c2 = HULLa < HULLa[1]

TIMEFRAME(15 minutes)
mx1 = average[16,1](close)
c7 = mx1 > mx1[1]
//c8 = mx1 < mx1[1]

TIMEFRAME(10 minutes)
mx2 = average[15,0](close)
c5 = mx2 > mx2[1]
//c6 = mx2 < mx2[1]

//Stochastic RSI | indicator
lengthRSI = 10//RSI period
lengthStoch = 16//Stochastic period
smoothK = 16 //Smooth signal of stochastic RSI
smoothD = 3 //Smooth signal of smoothed stochastic RSI
myRSI = RSI[lengthRSI](close)
MinRSI = lowest[lengthStoch](myrsi)
MaxRSI = highest[lengthStoch](myrsi)
StochRSI = (myRSI-MinRSI) / (MaxRSI-MinRSI)
K = average[smoothK](stochrsi)*100
D = average[smoothD](K)
c3 = K>D
//c4 = K<D

TIMEFRAME(default)
indicator4 = SuperTrend[1,7]
c1 = (close > indicator4)
//c2 = (close < indicator4)

//VECTEUR = CALCUL DE L'ANGLE
ONCE PeriodeA = 5
ONCE nbChandelierA= 42
MMA = Exponentialaverage[PeriodeA](close)
ADJASUROPPO = (MMA-MMA[nbchandelierA]*pipsize) / nbChandelierA
ANGLE = (ATAN(ADJASUROPPO)) //FONCTION ARC TANGENTE
CondBuy1 = ANGLE >= 31
//CondSell1 = ANGLE <= - 25


//VECTEUR = CALCUL DE LA PENTE ET SA MOYENNE MOBILE
ONCE PeriodeB = 24
ONCE nbChandelierB= 50
lag = 4
MMB = Exponentialaverage[PeriodeB](close)
pente = (MMB-MMB[nbchandelierB]*pipsize) / nbchandelierB
trigger = Exponentialaverage[PeriodeB+lag](pente)
CondBuy2 = (pente > trigger) AND (pente < 0)
//CondSell2 = (pente CROSSES UNDER trigger) AND (pente > -1)


//ENTREES EN POSITION
CONDBUY = CondBuy1 and CondBuy2 and Ctime and c1 and c3 and c5 and c7 and c9
//CONDSELL = CondSell1 and CondSell2 and Ctime and c2 and c4 and c6 and c8


//POSITION LONGUE
IF CONDBUY THEN
buy positionsize contract at market
SET STOP %LOSS 1.7
SET TARGET %PROFIT 2.1
ENDIF

//POSITION COURTE
//IF CONDSELL THEN
//Sellshort positionsize contract at market
//SET STOP %LOSS sls
//SET TARGET %PROFIT tps
//ENDIF

//Break even
once breakeven = 1//1 on - 0 off

breakevenPercent = .22
PointsToKeep = 2
startBreakeven = tradeprice(1)*(breakevenpercent/100)

//reset the breakevenLevel when no trade are on market
if breakeven>0 then
IF NOT ONMARKET THEN
breakevenLevel=0
ENDIF
// --- BUY SIDE ---
//test if the price have moved favourably of "startBreakeven" points already
IF LONGONMARKET AND close-tradeprice(1)>=startBreakeven*pipsize THEN
//calculate the breakevenLevel
breakevenLevel = tradeprice(1)+PointsToKeep*pipsize
ENDIF

//place the new stop orders on market at breakevenLevel
IF breakevenLevel>0 THEN
SELL AT breakevenLevel STOP
ENDIF
// --- end of BUY SIDE ---

IF SHORTONMARKET AND tradeprice(1)-close>startBreakeven*pipsize THEN
//calculate the breakevenLevel
breakevenLevel = tradeprice(1)-PointsToKeep*pipsize
ENDIF
//place the new stop orders on market at breakevenLevel
IF breakevenLevel>0 THEN
EXITSHORT AT breakevenLevel STOP
ENDIF
endif

//****************************************************************************************
// trailing atr stop II
once trailingstoptype     = 1    // trailing stop - 0 off, 1 on

once tsincrements = 0         // set to 0 to ignore tsincrements
once tsminatrdist = 2

once tsatrperiod    = 14         // ts atr parameter
once tsminstop      = 12         // ts minimum stop distance

once tssensitivity        = 0    // [0]close;[1]high/low

if trailingstoptype then
if barindex=tradeindex then
trailingstoplong     = 9   // ts atr distance
trailingstopshort    = 9  // ts atr distance
else
if longonmarket then
if tsnewsl>0 then
if trailingstoplong>tsminatrdist then
if tsnewsl>tsnewsl[1] then
trailingstoplong=trailingstoplong
else
trailingstoplong=trailingstoplong-tsincrements
endif
else
trailingstoplong=tsminatrdist
endif
endif
endif
if shortonmarket then
if tsnewsl>0 then
if trailingstopshort>tsminatrdist then
if tsnewsl<tsnewsl[1] then
trailingstopshort=trailingstopshort
else
trailingstopshort=trailingstopshort-tsincrements
endif
else
trailingstopshort=tsminatrdist
endif
endif
endif
endif

tsatr=averagetruerange[tsatrperiod]((close/10)*pipsize)/1000
//tsatr=averagetruerange[tsatrperiod]((close/1)*pipsize) // (forex)
tgl=round(tsatr*trailingstoplong)
tgs=round(tsatr*trailingstopshort)
if not onmarket or ((longonmarket and shortonmarket[1]) or (longonmarket[1] and shortonmarket)) then
tsmaxprice=0
tsminprice=close
tsnewsl=0
endif
if tssensitivity then
tssensitivitylong=high
tssensitivityshort=low
else
tssensitivitylong=close
tssensitivityshort=close
endif
if longonmarket then
tsmaxprice=max(tsmaxprice,tssensitivitylong)
if tsmaxprice-tradeprice(1)>=tgl*pointsize then
if tsmaxprice-tradeprice(1)>=tsminstop then
tsnewsl=tsmaxprice-tgl*pointsize
else
tsnewsl=tsmaxprice-tsminstop*pointsize
endif
endif
endif
if shortonmarket then
tsminprice=min(tsminprice,tssensitivityshort)
if tradeprice(1)-tsminprice>=tgs*pointsize then
if tradeprice(1)-tsminprice>=tsminstop then
tsnewsl=tsminprice+tgs*pointsize
else
tsnewsl=tsminprice+tsminstop*pointsize
endif
endif
endif
if longonmarket then
if tsnewsl>0 then
sell at tsnewsl stop
endif
if tsnewsl>0 then
if low crosses under tsnewsl then
sell at market // when stop is rejected
endif
endif
endif
if shortonmarket then
if tsnewsl>0 then
exitshort at tsnewsl stop
endif
if tsnewsl>0 then
if high crosses over tsnewsl then
exitshort at market // when stop is rejected
endif
endif
endif
Welcome back nonetheless 🙂
@nonetheless
Welcome back 🙂
I put Your last code above in PRT but my backtest is different from Yours. I also needed to add an “endif” in the end. I’m running version 10.3
Have I done something wrong?
Hello nonetheless
Hope you are well. Many thanks for your reply. I just tried your suggestion with the code you posted above and it worked. I will try to incorporate this back into the version of the Vectorial code I had downloaded preciously.
Thanks
S
my backtest is different from Yours
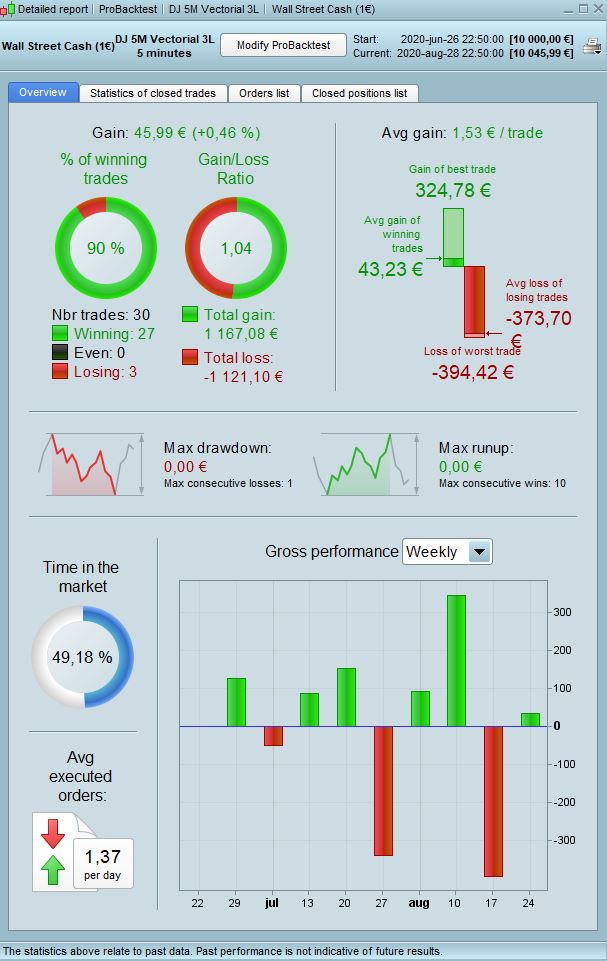
hi Artemois, live forward tests will always vary from the back test for multiple reasons. Also, I think mine was stopped and restarted some time in August so the MM will have reset. But when I run a back test for those 2 months, I see v similar performance ~91%
and yes, it does need another endif – got lost in the copy/paste
Also, please note that i didnt do any WF or VRT for this; the straight back test looked good and I was curious about the basic concept so I put it on demo for a couple of months, that’s all. I’m sure it can be improved
Hi Nonetheless
My bad, I didn’t understand it was Your actual result but thought it was the backtest 😉
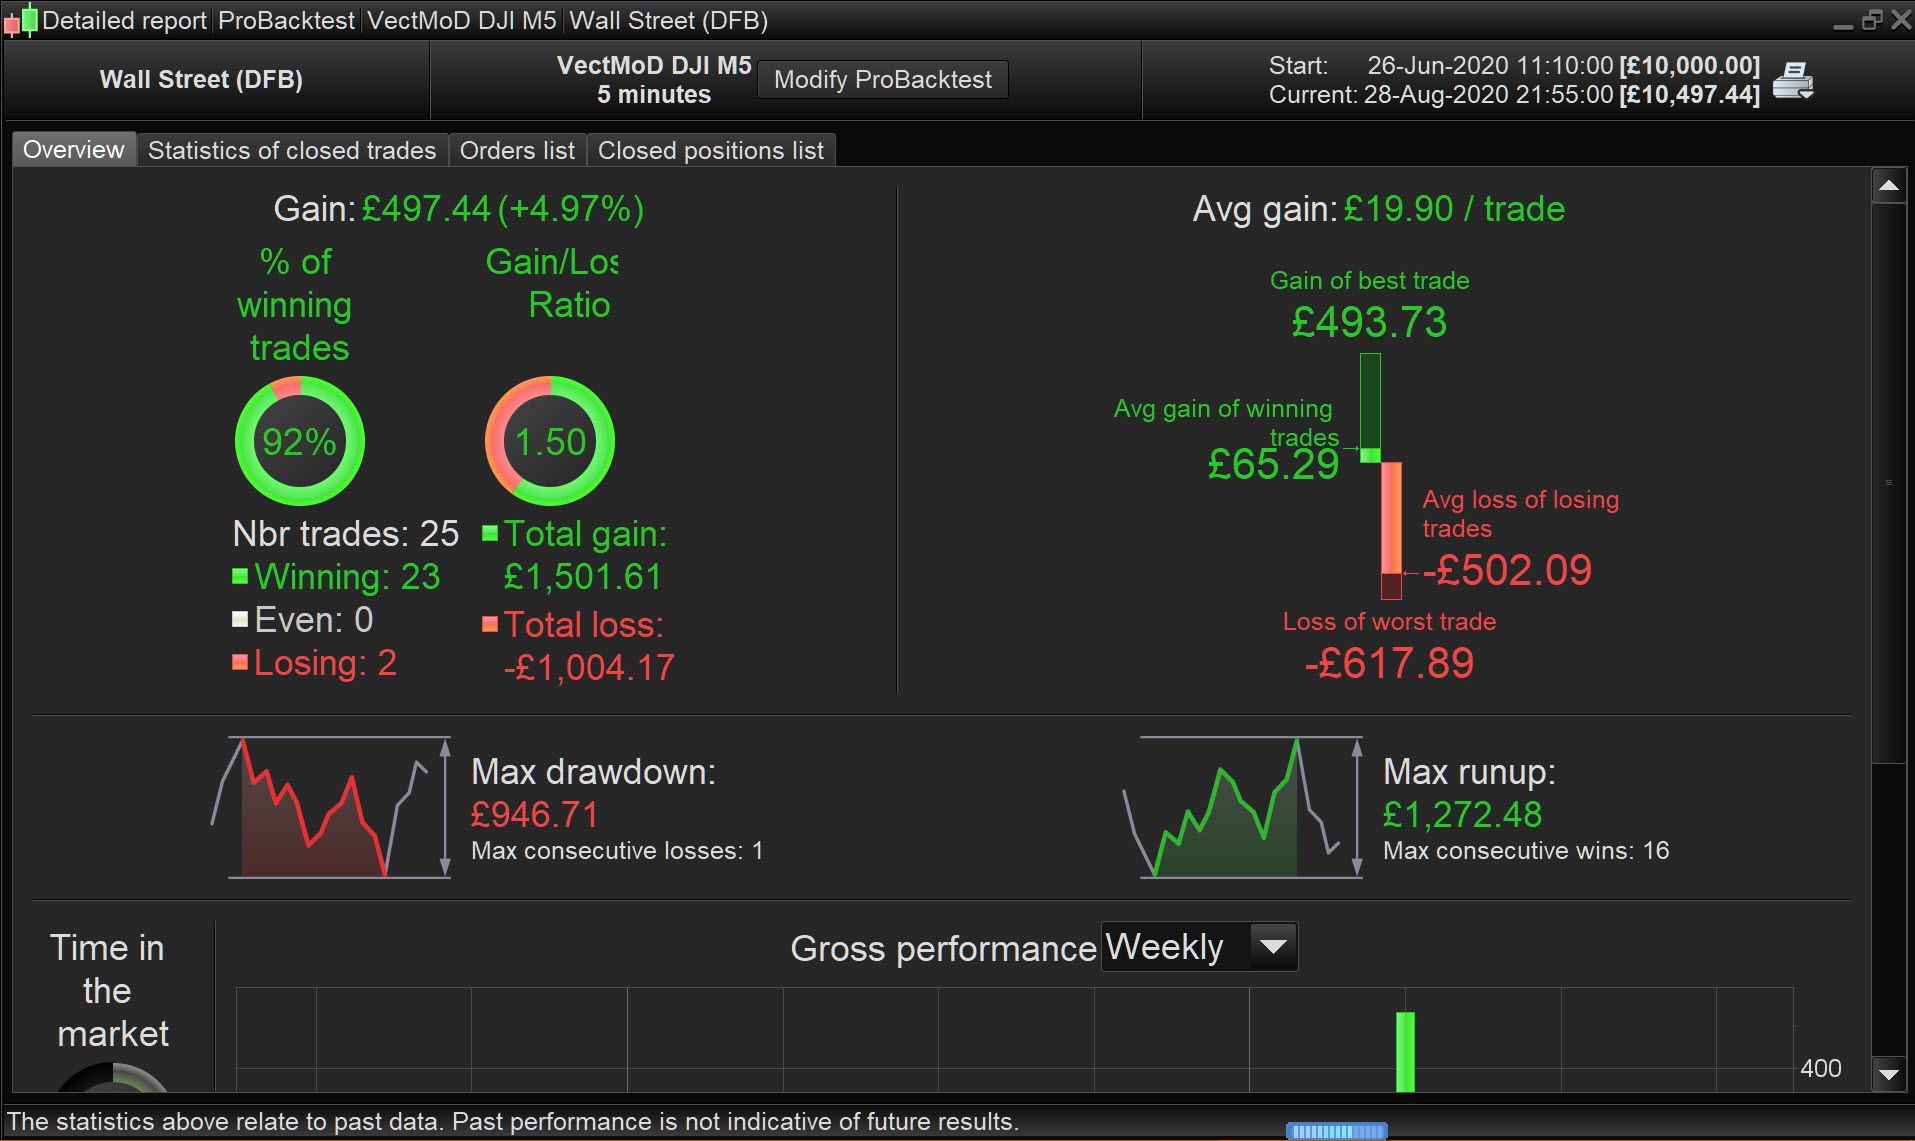
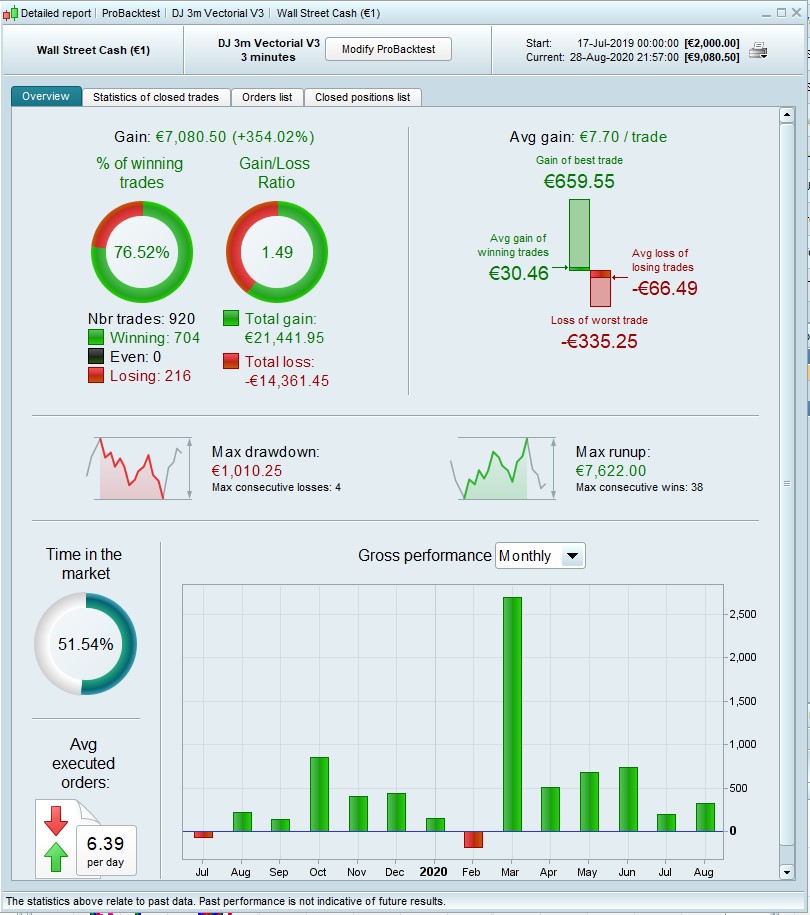
Below is a backtest for the same dates.
I got same backtest result as Artemois … different / reduced by a factor of 15 ish from Nonetheless Pro-Order results.
Big difference … something must be wrong?
This is well weird … I ran Nonetheless code above again 2 mins ago and got completely different results than I was getting last night!
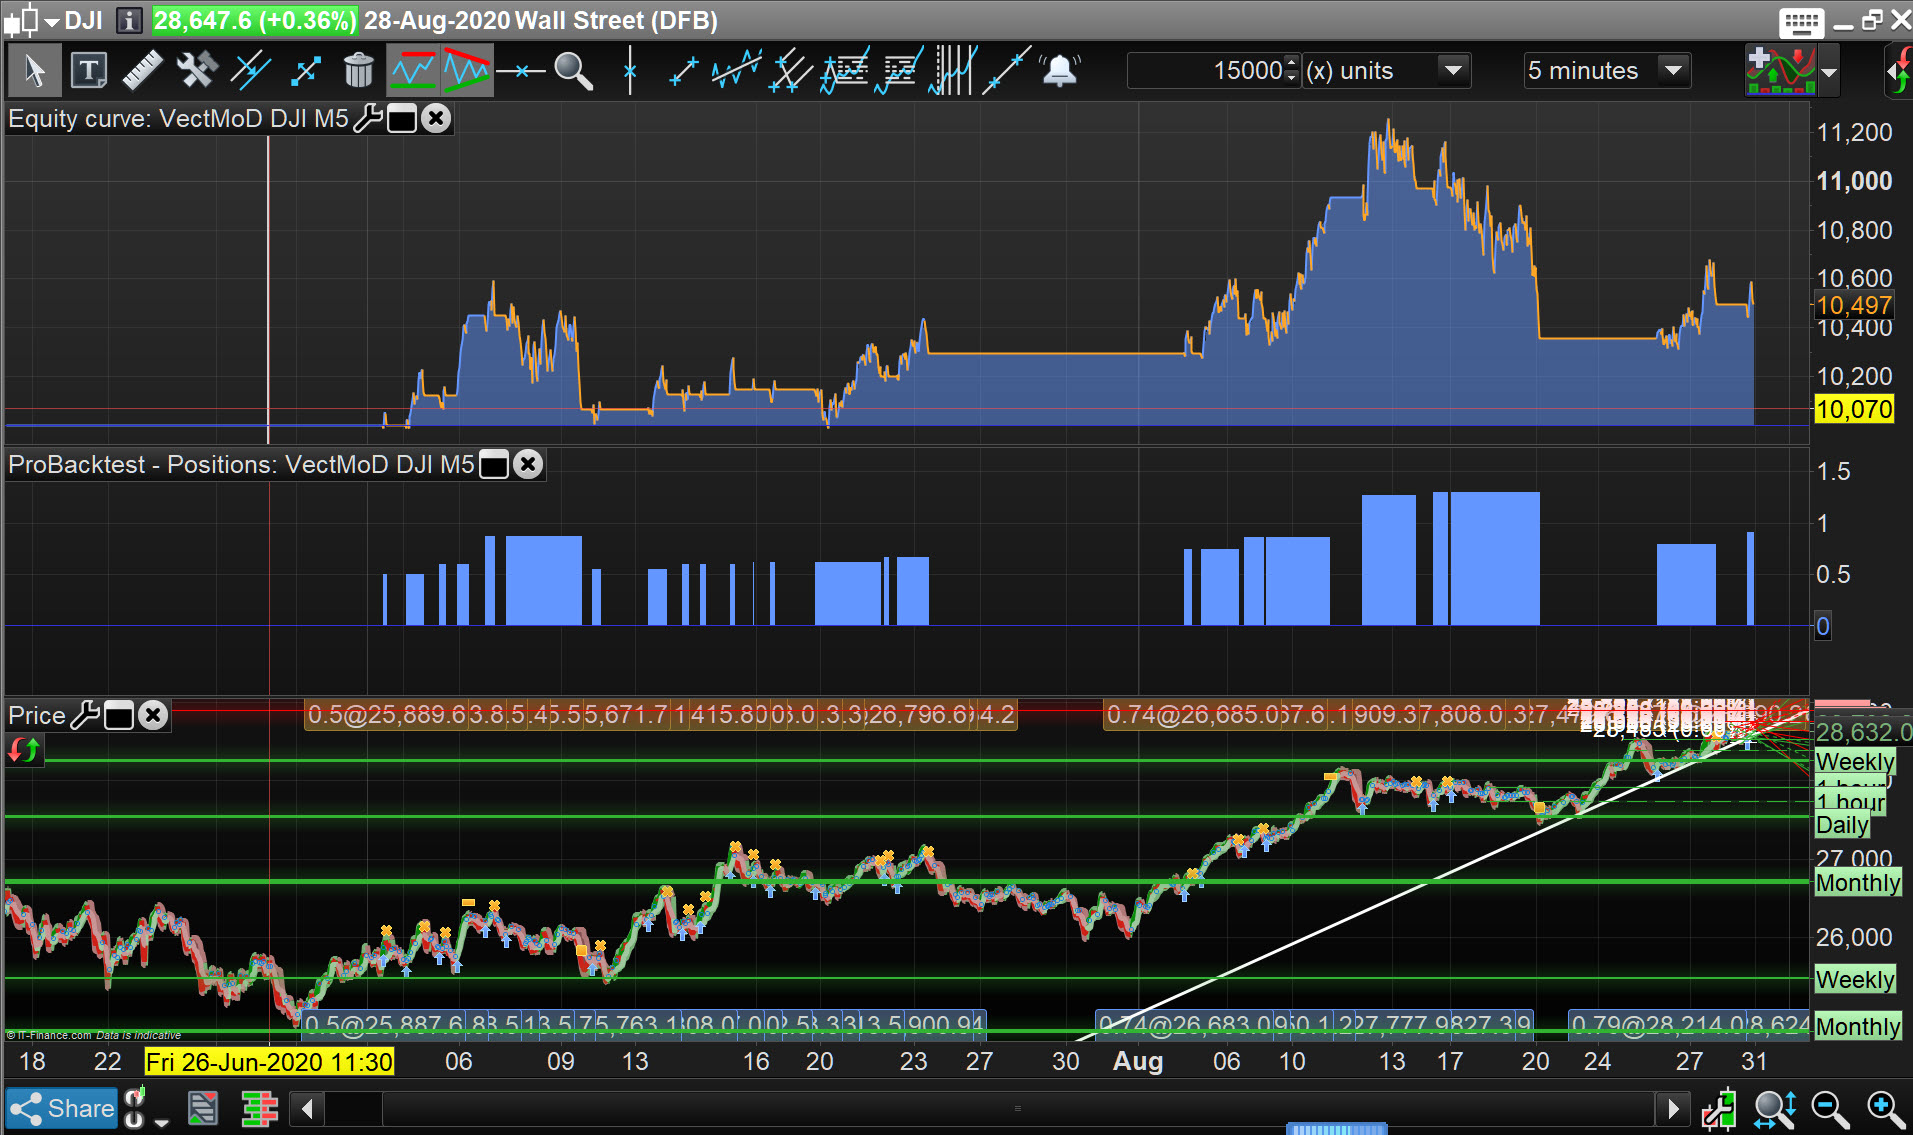
Nearer / more comparable with None’s now … see attached. I still get far more drawdown though … mine dd at £947 vs None’s dd at £64
What do you get this morning @Artemois ??
I’m putting attached on Forward Test on Monday … MM turned off and Period = 55 at Line 37.
Above is all I explored, I’m sure there would be other beneficial changes?
It be great if we had a Short version or Long and Short in same System?
Thank You for sharing Nonetheless!
Hi Grahal
I get the same results today as yesterday
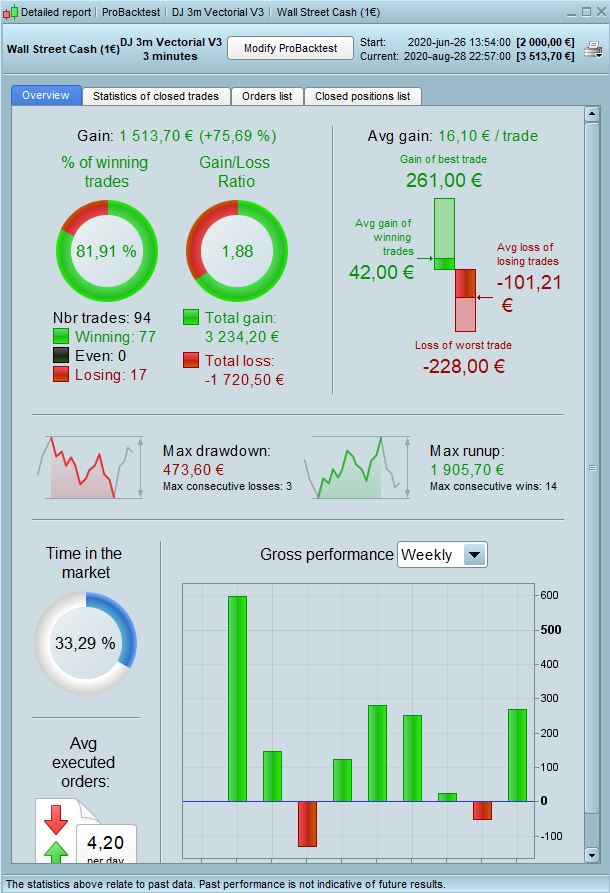
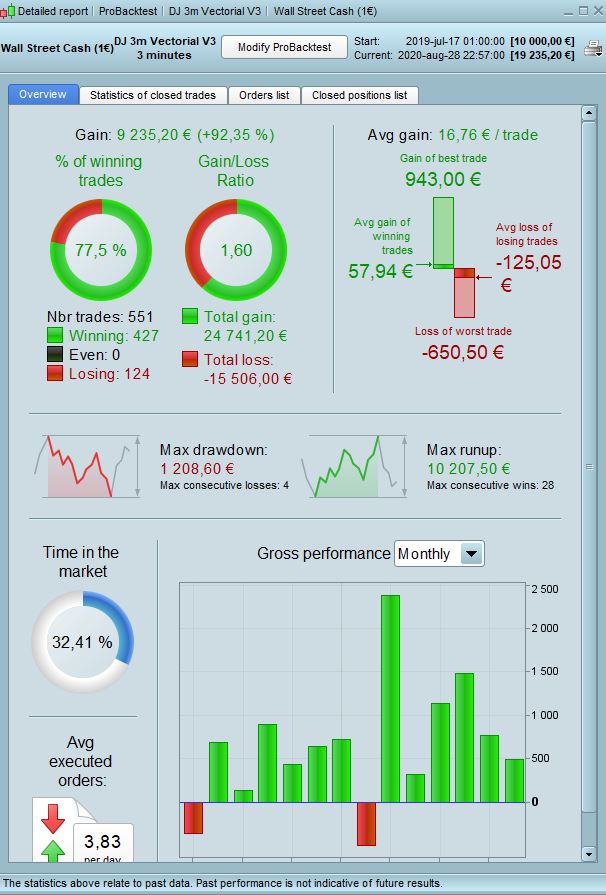
I made a backtest on the DJ 3m Vectorial V3 for the same period and it has been more succesfull.
I also made one of 200 kpts
I find them both interesting!
Thank You @Nonetheless for sharing, it is very interesting as a beginner to se what the more experienced people are doing.
Hi Grahal, how’s it going?
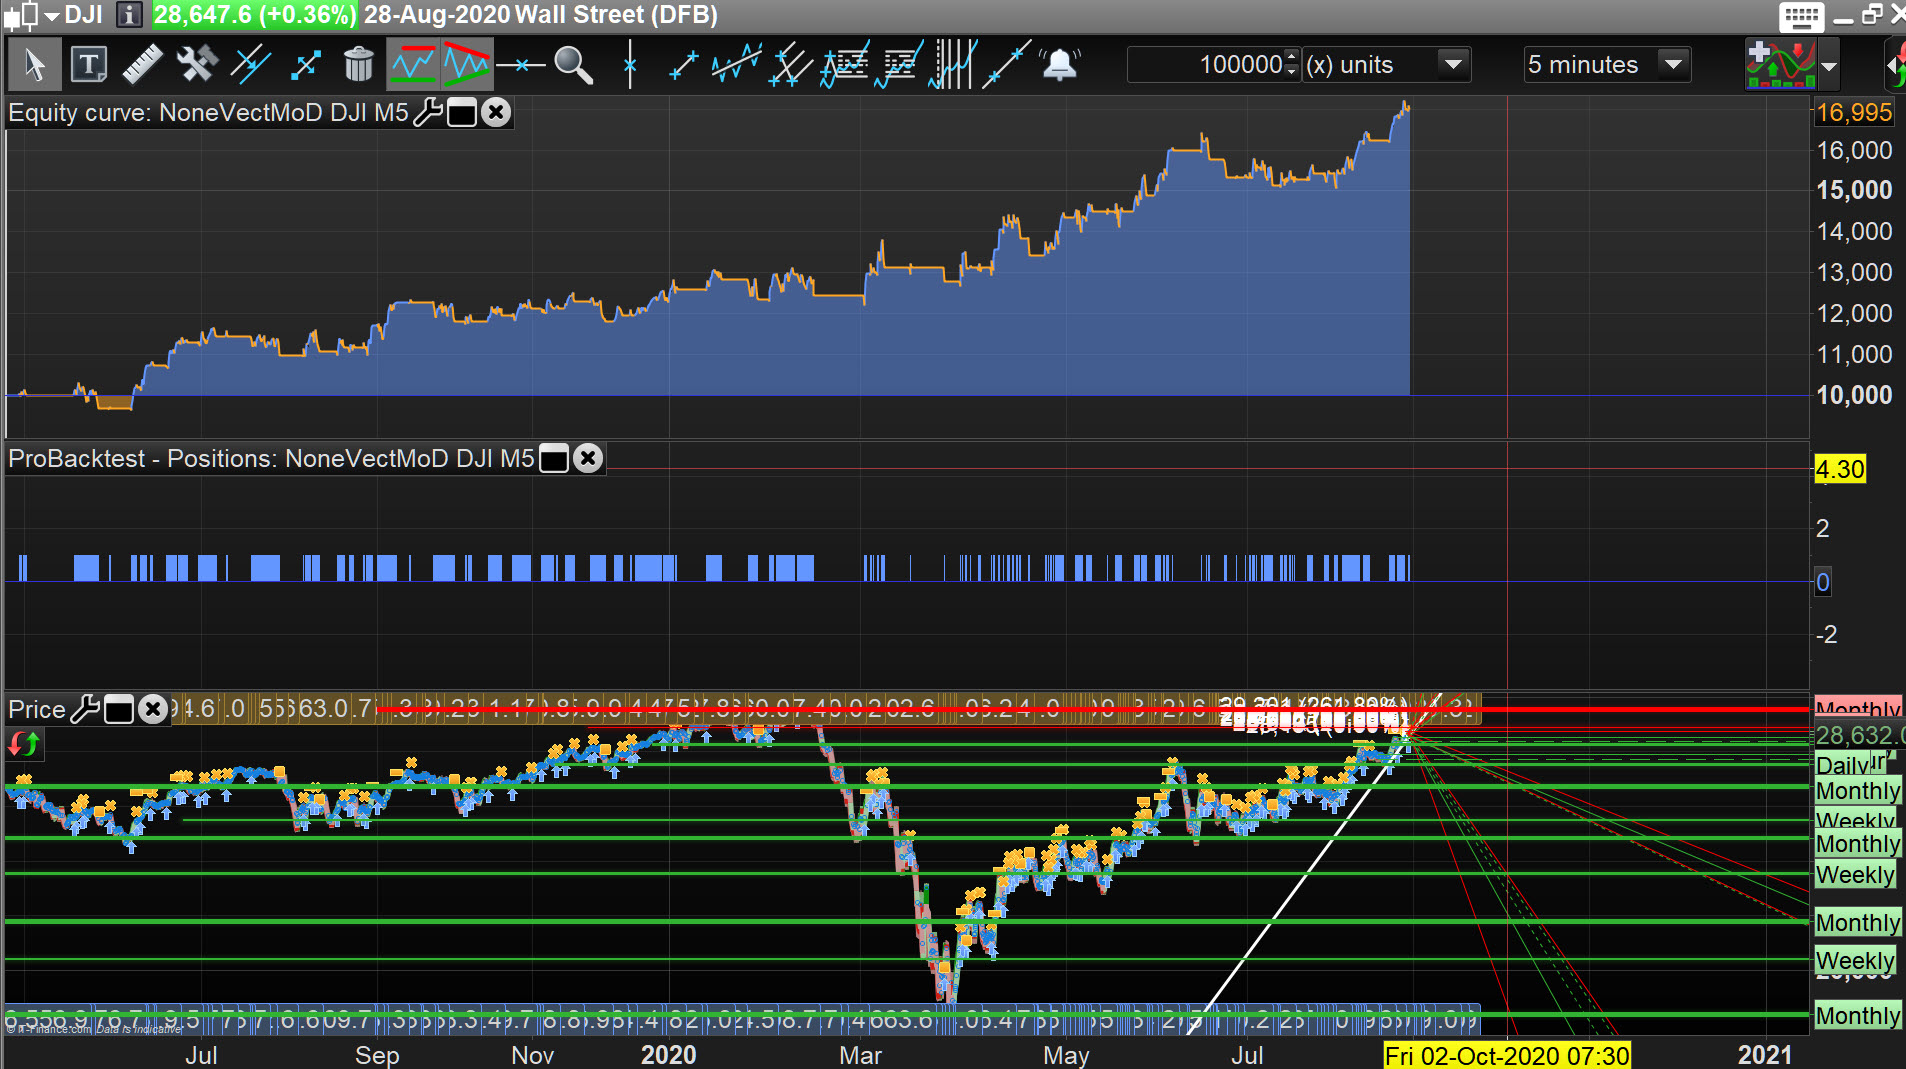
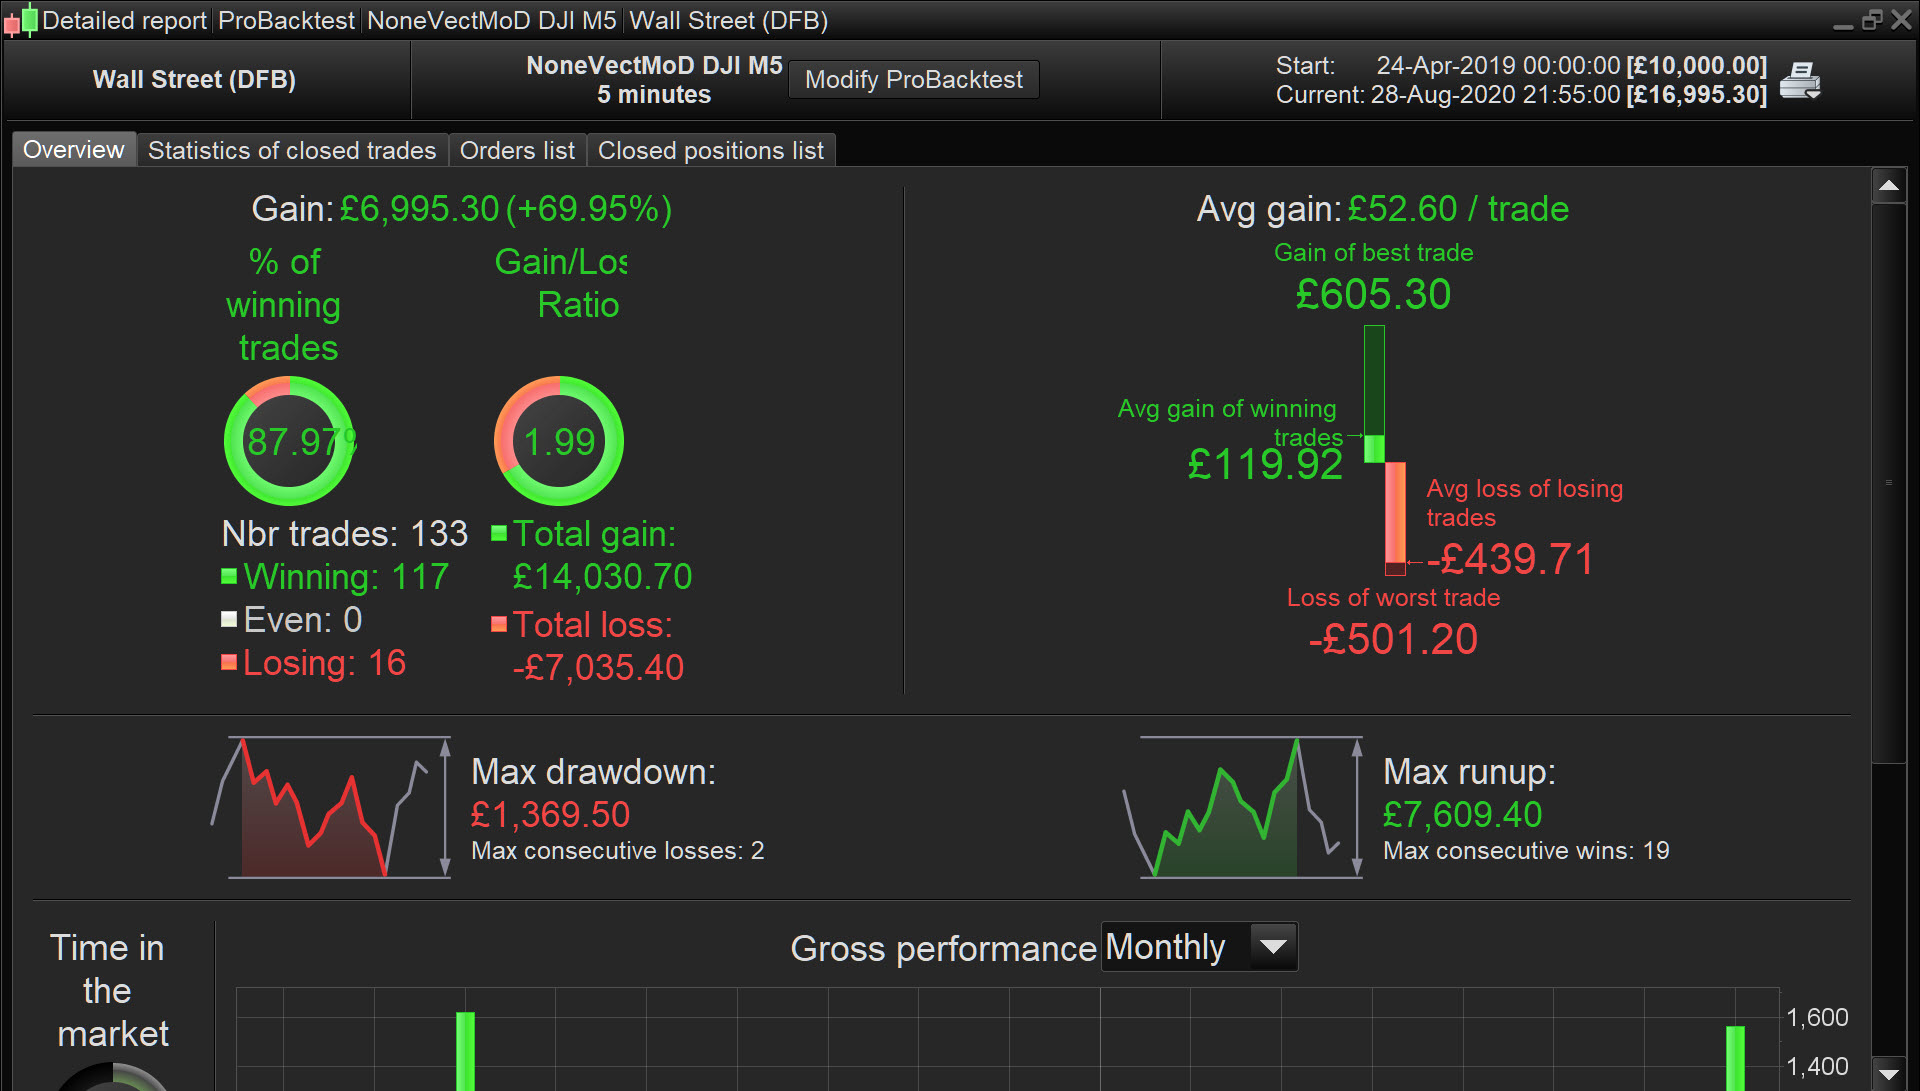
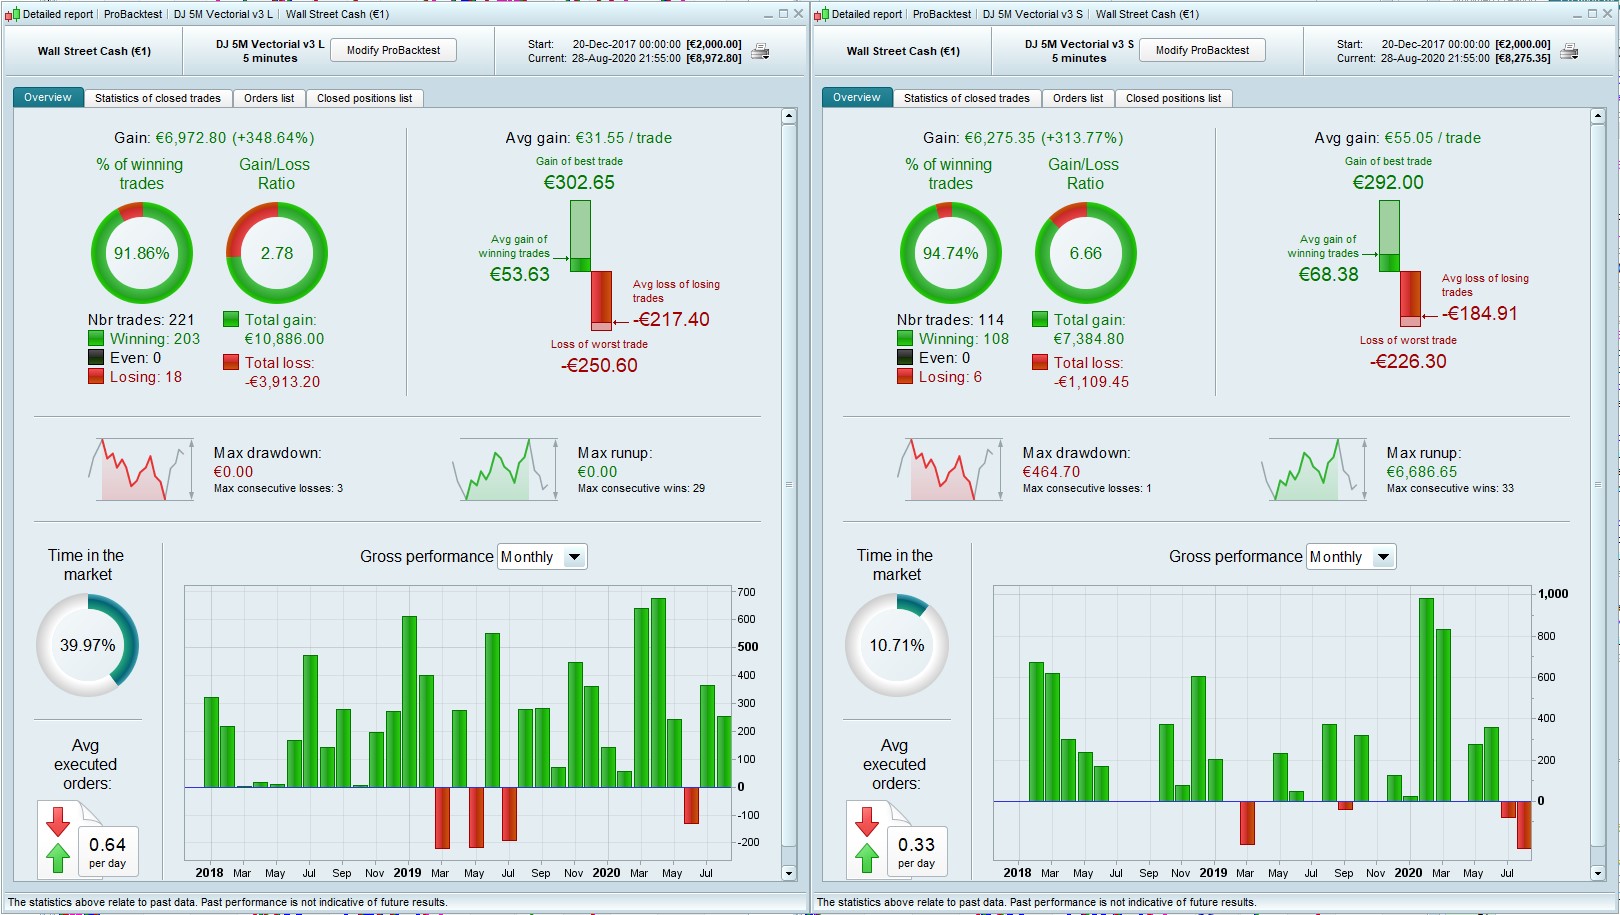
No idea why you got such varying results from this. I have attached the itf, just in case something got corrupted in the copy/paste. Also the 200k back tests for long and short, with a comparison look at the 3m v3. Obviously the latter is only 13 months, as opposed to 32.
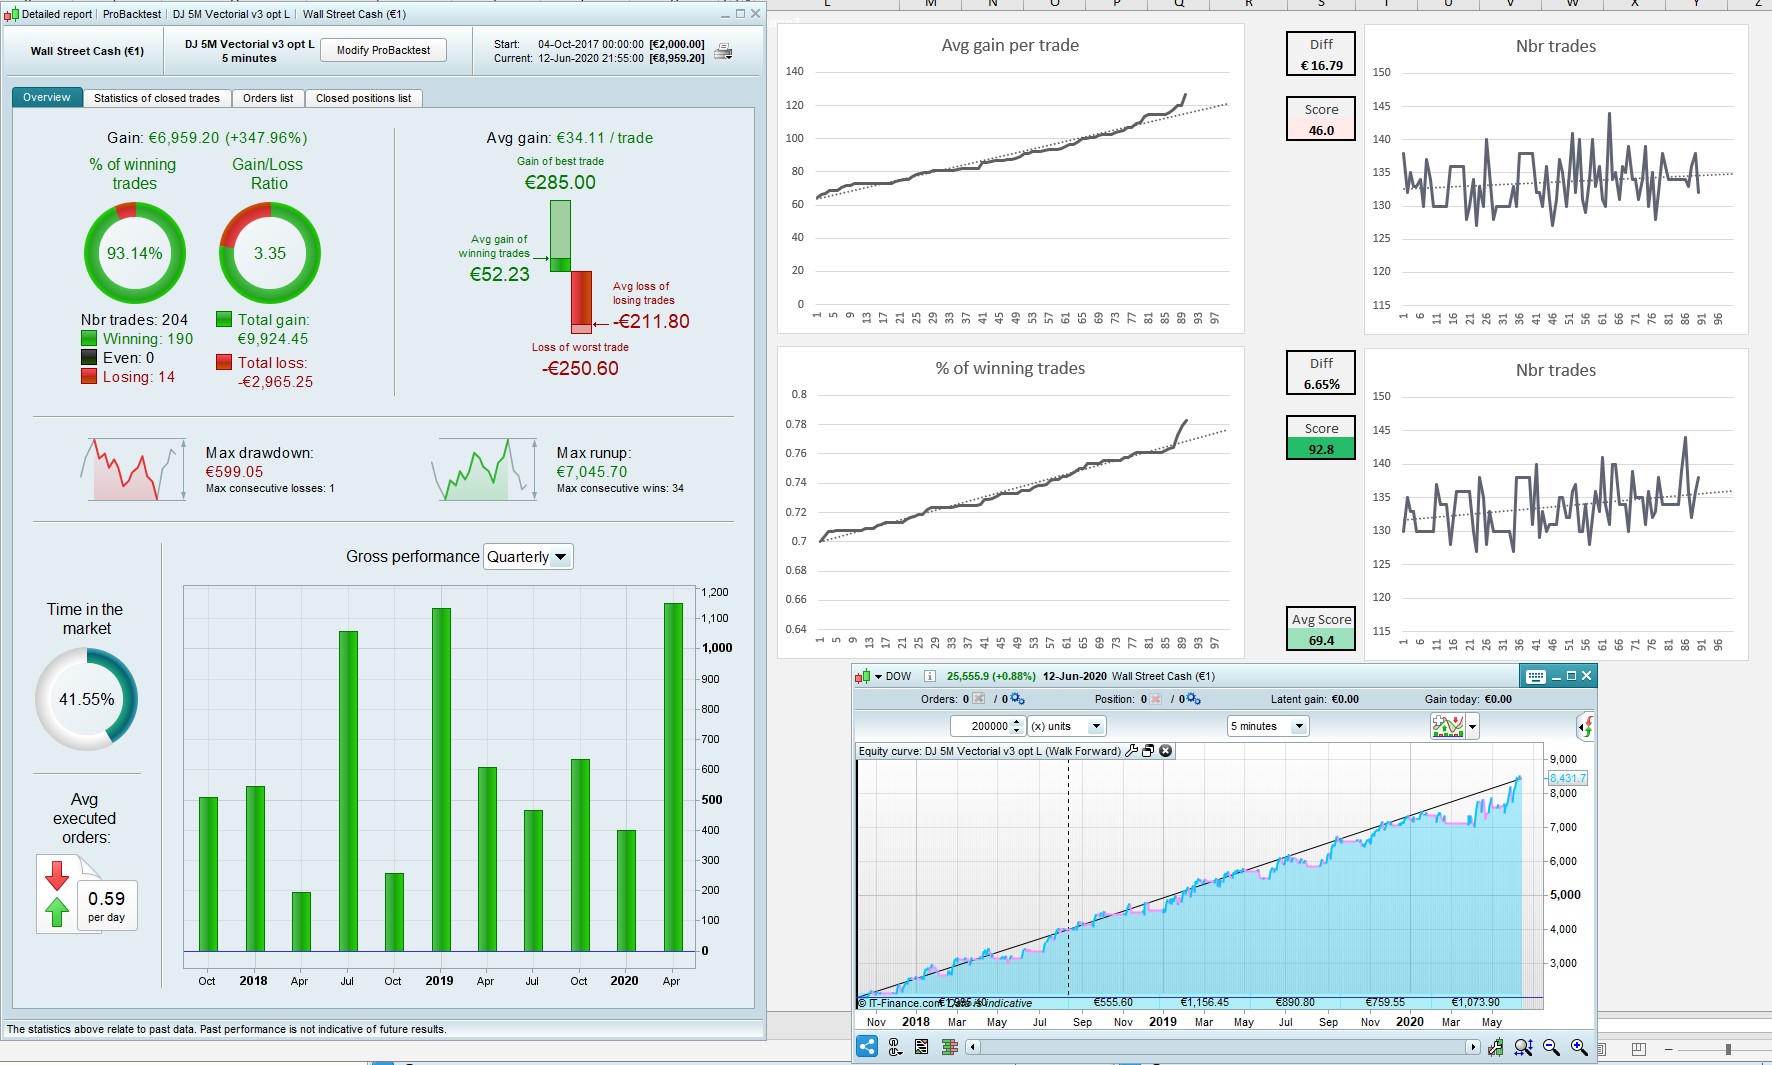
I also found some tests that I did back in the spring of the 5m long version … seems to check out. But as I said, I really did this out of curiosity to try marrying Balmora’s Vectorial with MoD … and then I kinda forgot about it.
Both the Vectorial and the MOD are very interesting codes. MOD has a slightly bigger problem with DD but apart from that it has potential. This, and especially the 3 min version is good.
Is there a chance of any further development ?
Ciao Balmora74 vedo che il tuo sistema anche su timeframe ad 1 minuto funziona bene ottimizzato, tu cosa ne pensi?
Hi Balmora74 I see that your system even on 1 minute timeframe works well optimized, what do you think?