Bonjour a tous
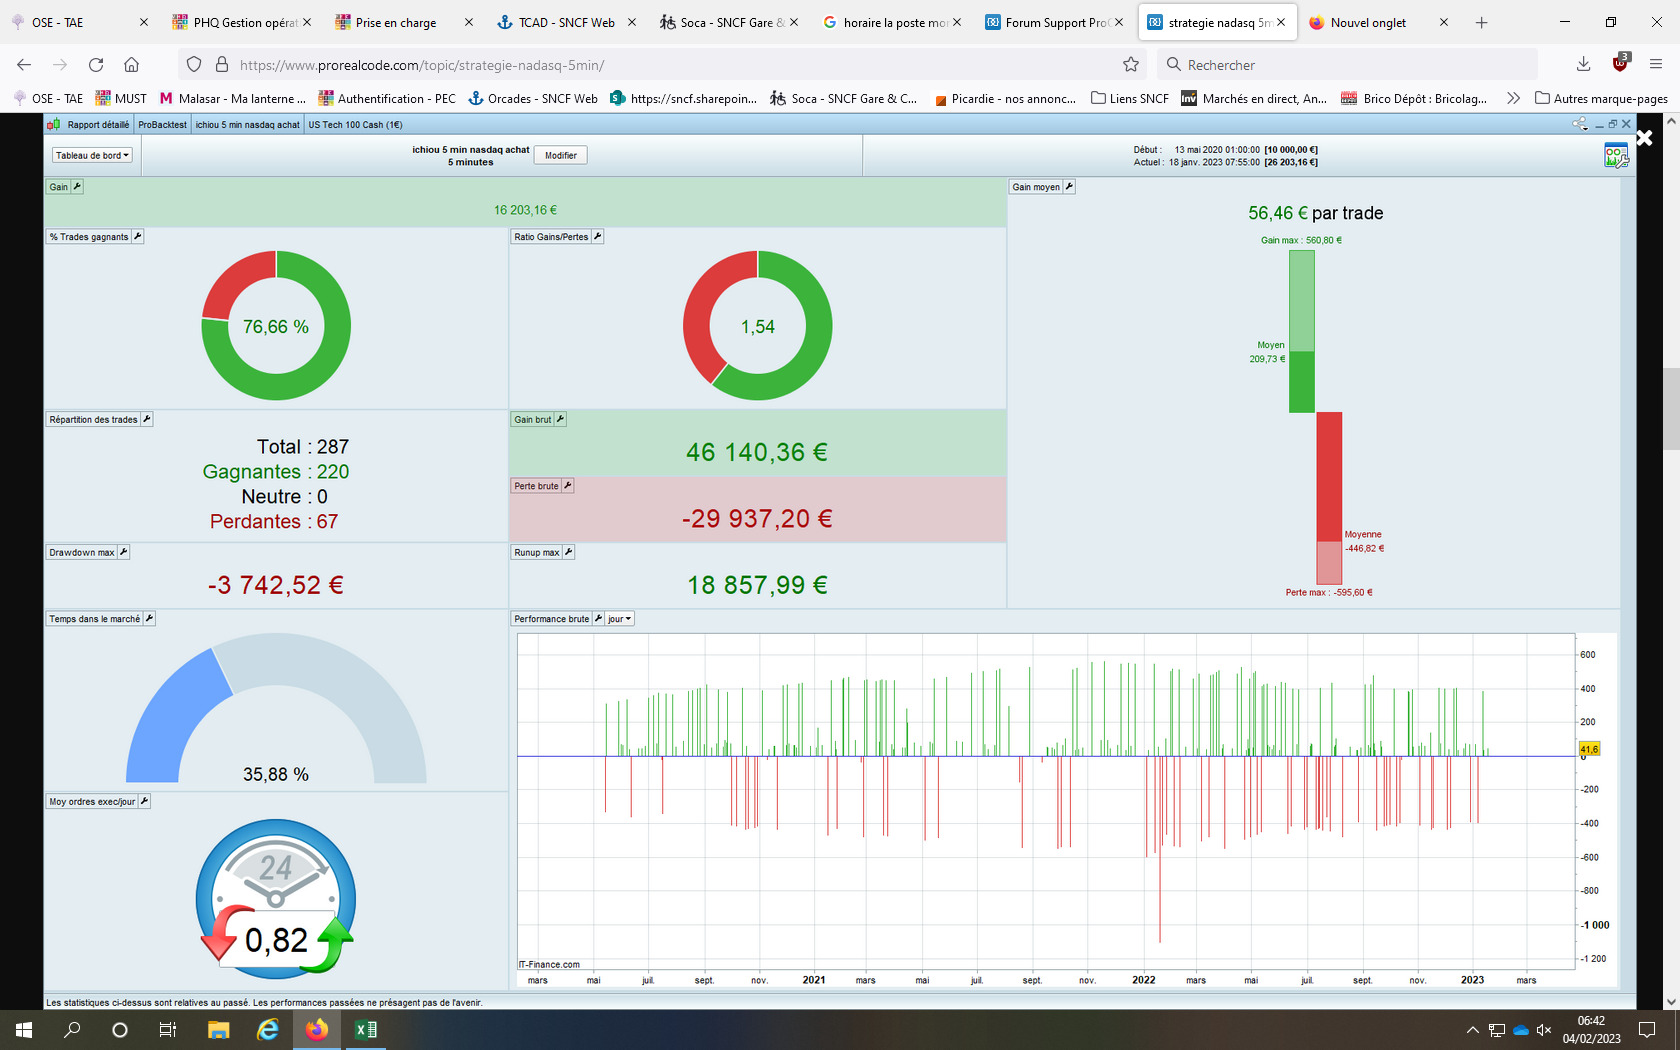
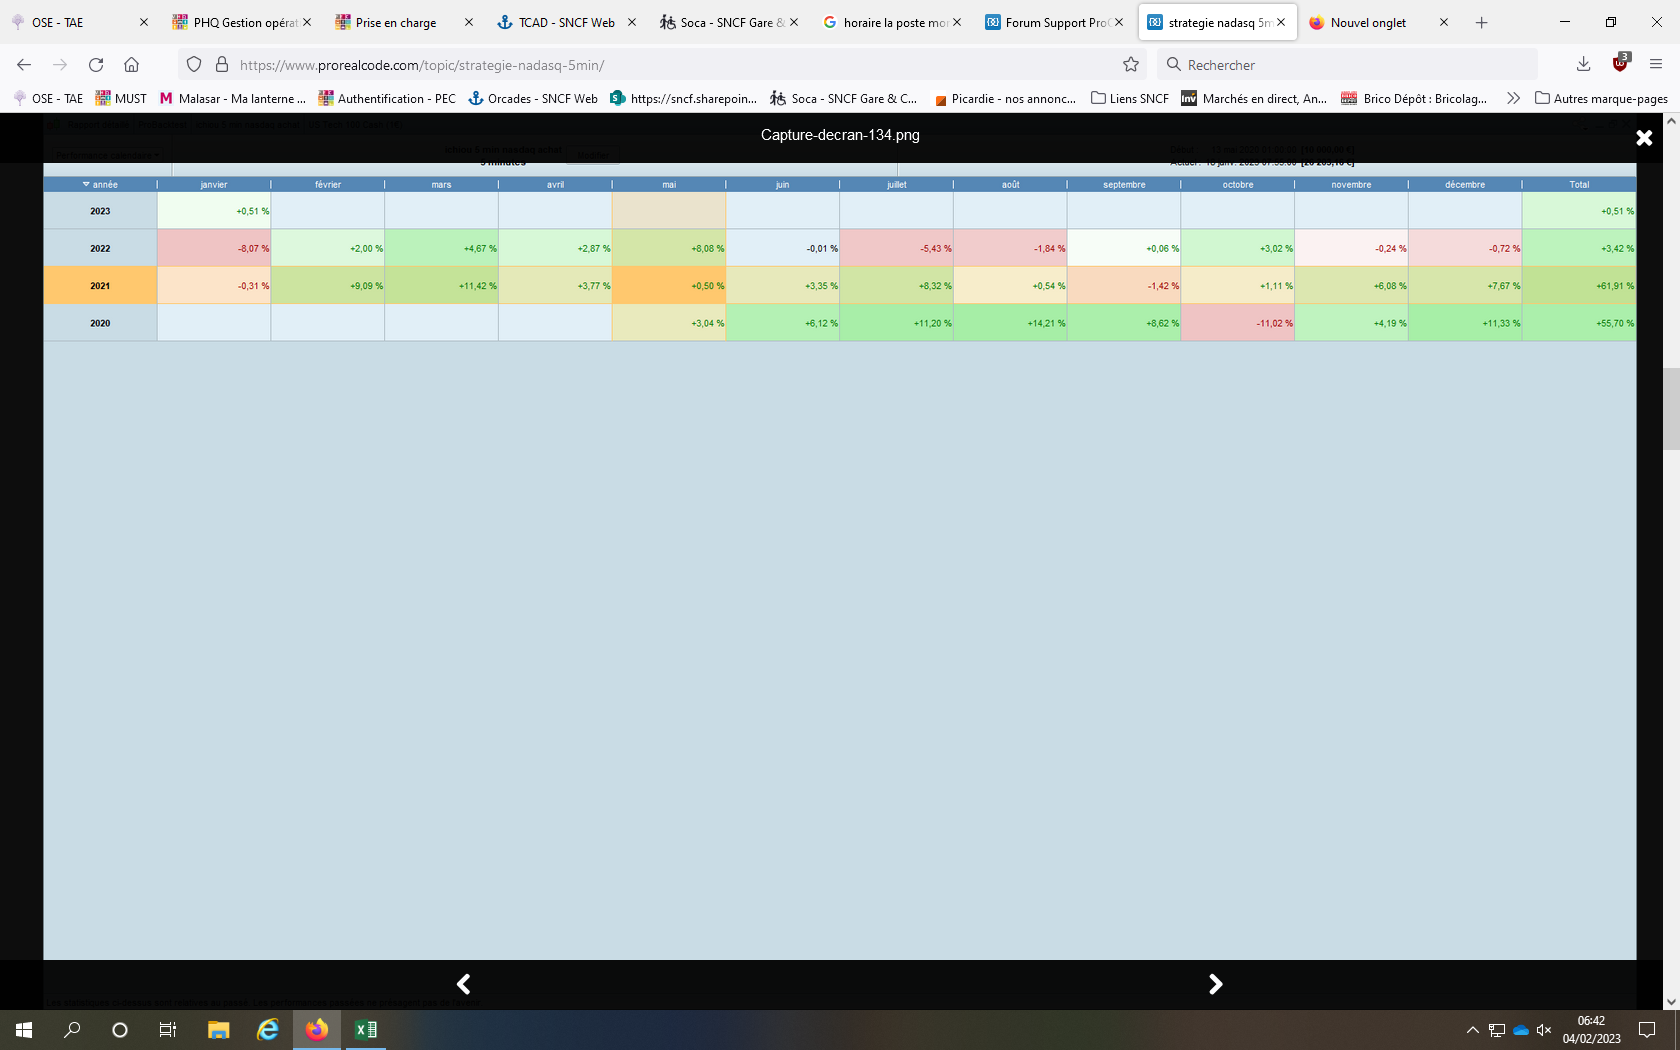
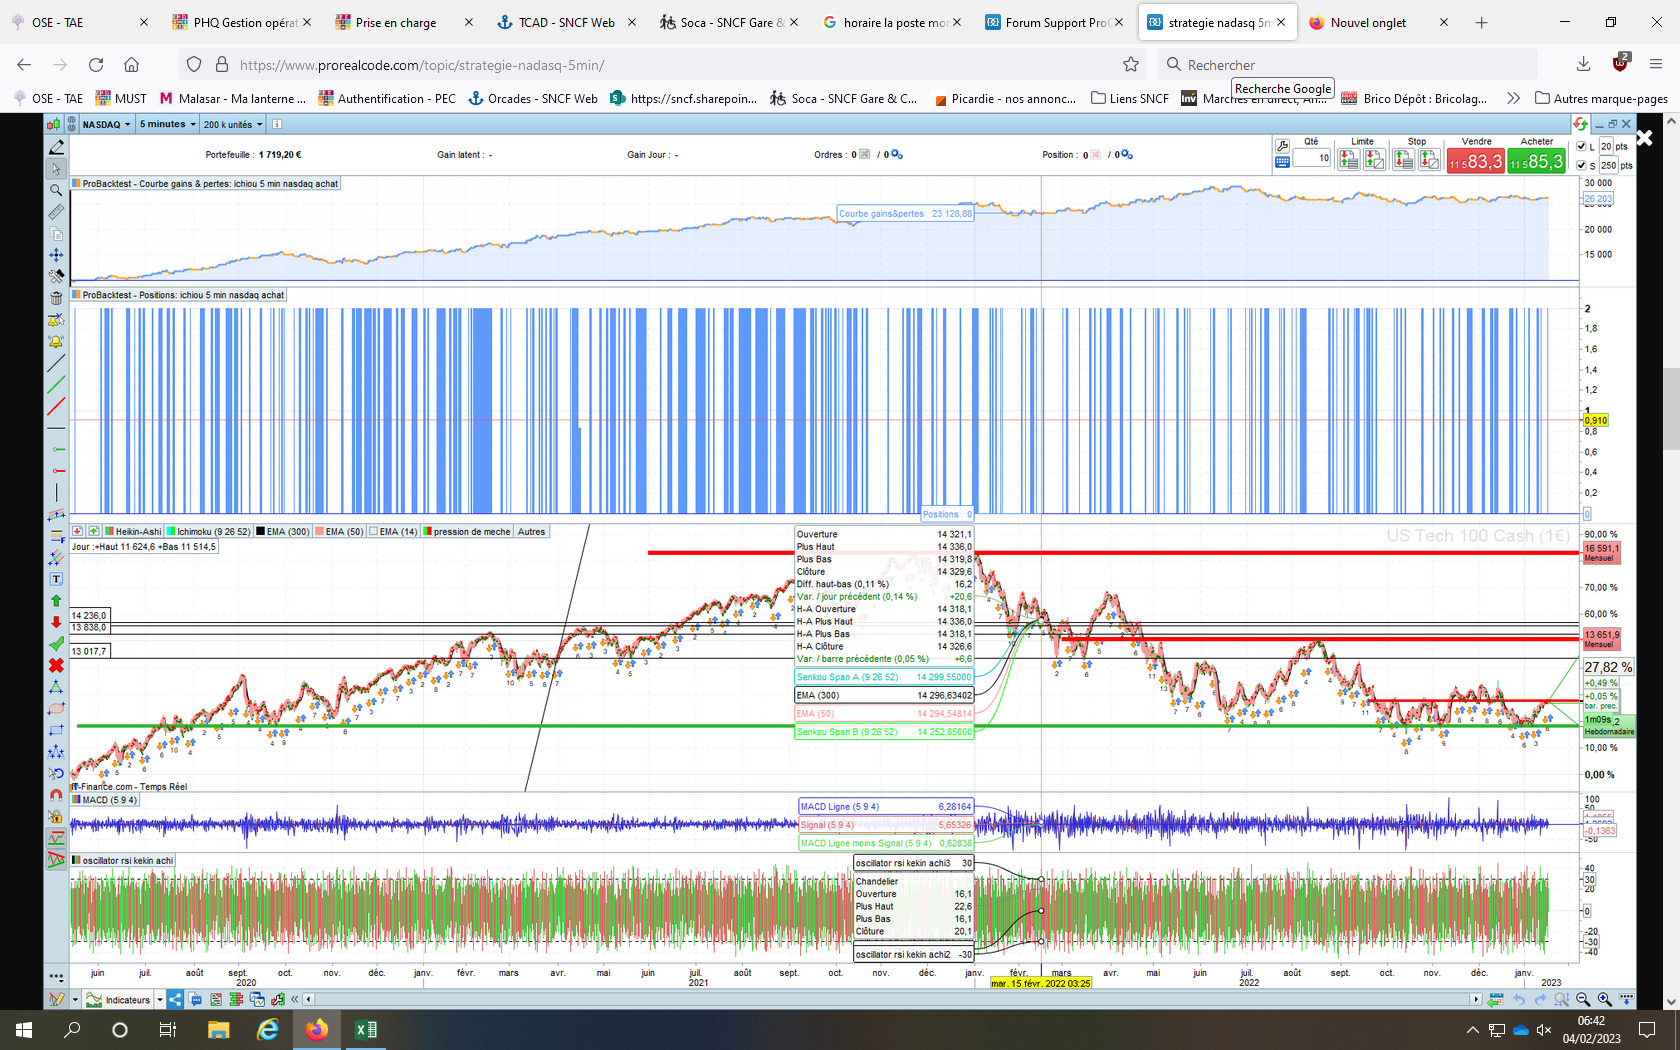
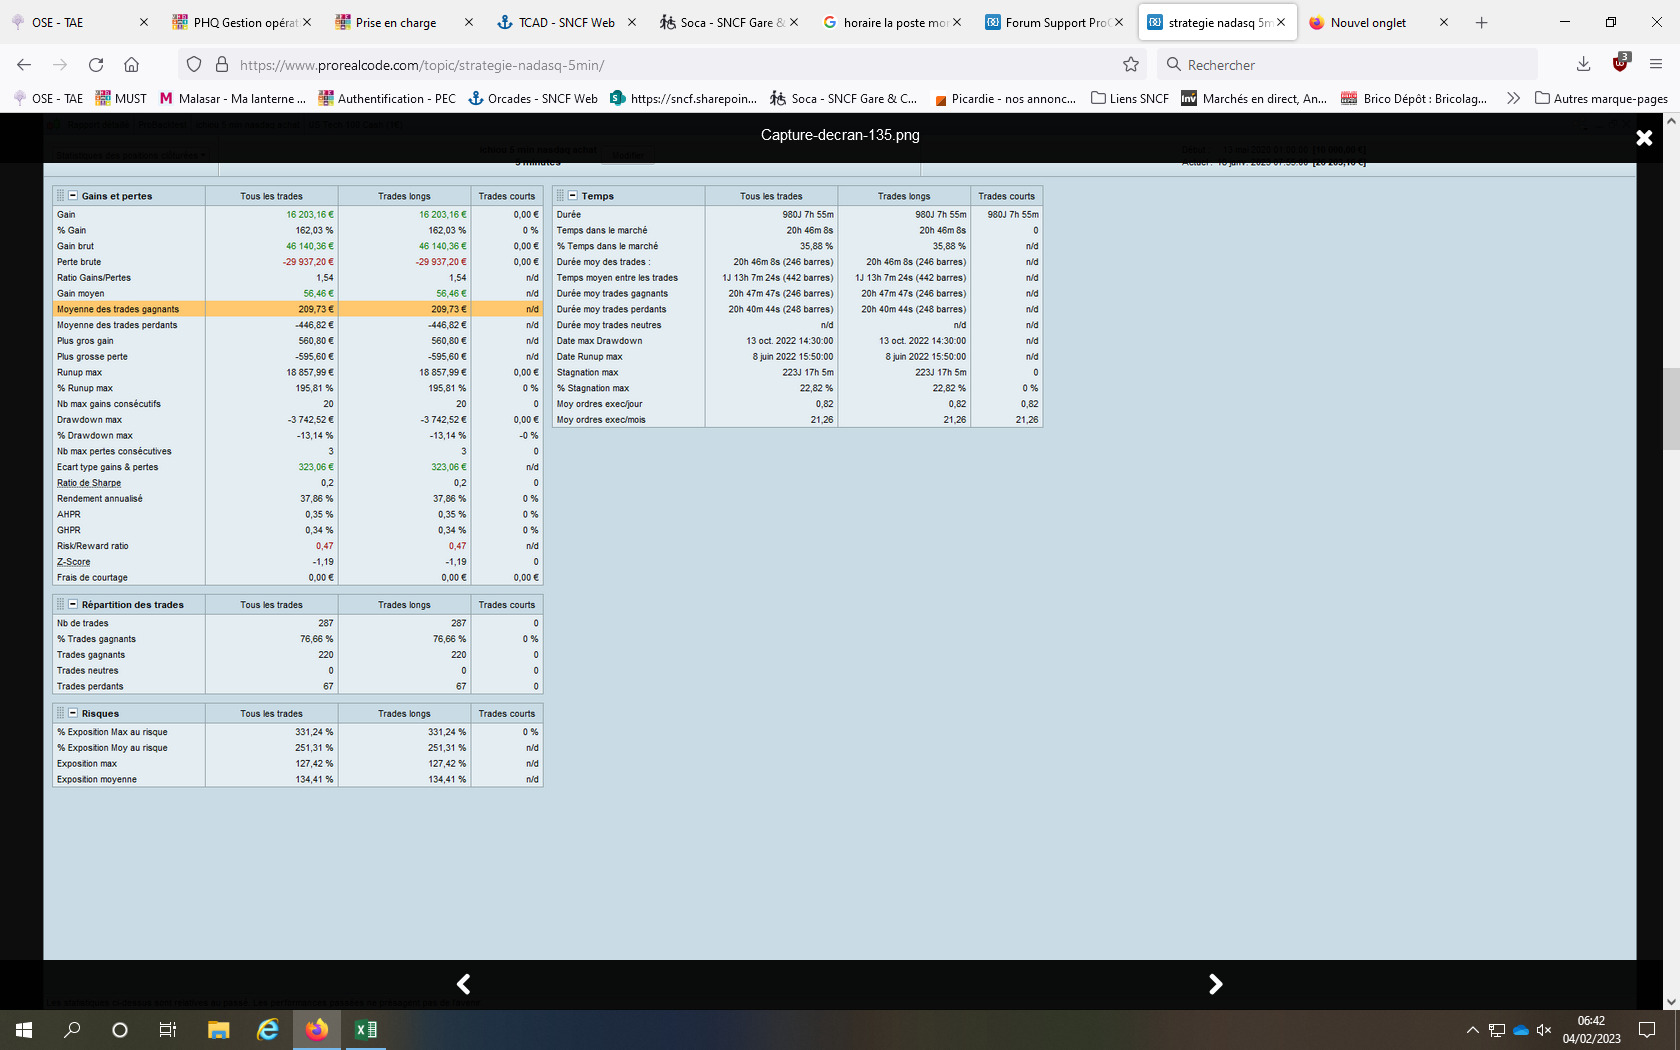
Je remonte mon algo nadasq 5 minutes à l’achat uniquement.
Je cherche à l’améliorer.
Je ne peux remonter sur 3 ans avec ma version prt.
Si cela peut intéresser quelqu’un et travailler un peu dessus et me dire ce qu’il en pense.
Break even intégré de Nicolas et Robberto
// Définition des paramètres du code
DEFPARAM CumulateOrders = false // pas de cumul de positions
DEFPARAM Preloadbars = 1000000

capital= 50000

// Empêche le système de placer des ordres pour entrer sur le marché ou augmenter la taille d'une position avant l'heure spécifiée
noEntryBeforeTime = 150000
timeEnterBefore = time >= noEntryBeforeTime

// Empêche le système de placer des ordres pour entrer sur le marché ou augmenter la taille d'une position après l'heure spécifiée
noEntryAfterTime = 223000
timeEnterAfter = time < noEntryAfterTime

// Empêche le système de placer de nouveaux ordres sur les jours de la semaine spécifiés
daysForbiddenEntry = OpenDayOfWeek = 6 OR OpenDayOfWeek = 0

// Conditions pour ouvrir une position acheteuse
indicator1 = SenkouSpanA[9,26,52]
c1 = (close CROSSES OVER indicator1)
indicator2 = SenkouSpanB[9,26,52]
c2 = (close CROSSES OVER indicator2)
c3 = (close > DOpen(0)[1])
IF (c1 AND c2 ) AND timeEnterBefore AND timeEnterAfter AND not daysForbiddenEntry THEN
BUY 2 CONTRACT AT MARKET
partial=0
ENDIF
// sortie partielle
if longonmarket and positionperf>1.71/100 and partial=0 then
sell countofposition/1.7 contract at market
partial = 1
endif
if summation[1680](longonmarket)=1680 then
sell at market
endif
if summation[1000](shortonmarket)=1000 then
exitshort at market
endif

// Stops et objectifs
set stop %loss 1.8
set target %profit 1.73


IF Not OnMarket THEN
//
// when NOT OnMarket reset values to default values
//
TrailStart    = 65          //30     Start trailing profits from this point
BasePerCent   = 0.000       //20.0%  Profit percentage to keep when setting BerakEven
StepSize      = 1          //10     Pip chunks to increase Percentage
PerCentInc    = 0.000       //10.0%  PerCent increment after each StepSize chunk
BarNumber     = 10          //10     Add further % so that trades don't keep running too long
BarPerCent    = 0.235       //10%    Add this additional percentage every BarNumber bars
RoundTO       = -0.5        //-0.5   rounds always to Lower integer,   +0.4 rounds always to Higher integer,     0 defaults PRT behaviour
PriceDistance = 9 * pipsize //7      minimun distance from current price
y1            = 0           //reset to 0
y2            = 0           //reset to 0
ProfitPerCent = BasePerCent //reset to desired default value
TradeBar      = BarIndex
ELSIF LongOnMarket AND close > (TradePrice + (y1 * pipsize)) THEN                              //LONG positions
//
// compute the value of the Percentage of profits, if any, to lock in for LONG trades
//
x1 = (close - tradeprice) / pipsize                                     //convert price to pips
IF x1 >= TrailStart THEN                                                //    go ahead only if N+ pips
Diff1         = abs(TrailStart - x1)                                 //difference from current profit and TrailStart
Chunks1       = max(0,round((Diff1 / StepSize) + RoundTO))           //number of STEPSIZE chunks
ProfitPerCent = BasePerCent + (BasePerCent * (Chunks1 * PerCentInc)) //compute new size of ProfitPerCent
// compute number of bars elapsed and add an additionl percentage
// (this percentage is different from PerCentInc, since it's a direct percentage, not a Percentage of BasePerCent)
// (if BasePerCent is 20% and this is 10%, the whole percentage will be 30%, not 22%)
BarCount      = BarIndex - TradeBar
IF BarCount MOD BarNumber = 0 THEN
ProfitPerCent = ProfitPerCent + BarPerCent
ENDIF
//
ProfitPerCent = max(ProfitPerCent[1],min(100,ProfitPerCent))         //make sure ProfitPerCent doess not exceed 100%
y1 = max(x1 * ProfitPerCent, y1)                                     //y1 = % of max profit
ENDIF
ELSIF ShortOnMarket AND close < (TradePrice - (y2 * pipsize)) THEN                             //SHORT positions
//
// compute the value of the Percentage of profits, if any, to lock in for SHORT trades
//
x2 = (tradeprice - close) / pipsize                                     //convert price to pips
IF x2 >= TrailStart THEN                                                //      go ahead only if N+ pips
Diff2         = abs(TrailStart - x2)                                 //difference from current profit and TrailStart
Chunks2       = max(0,round((Diff2 / StepSize) + RoundTO))           //number of STEPSIZE chunks
ProfitPerCent = BasePerCent + (BasePerCent * (Chunks2 * PerCentInc)) //compute new size of ProfitPerCent
// compute number of bars elapsed and add an additionl percentage
// (this percentage is different from PerCentInc, since it's a direct percentage, not a Percentage of BasePerCent)
// (if BasePerCent is 20% and this is 10%, the whole percentage will be 30%, not 22%)
BarCount      = BarIndex - TradeBar
IF BarCount MOD BarNumber = 0 THEN
ProfitPerCent = ProfitPerCent + BarPerCent
ENDIF
//
ProfitPerCent = max(ProfitPerCent[1],min(100,ProfitPerCent))         //make sure ProfitPerCent doess not exceed 100%
y2 = max(x2 * ProfitPerCent, y2)                                     //y2 = % of max profit
ENDIF
ENDIF
IF y1 THEN                                                                 //Place pending STOP order when y1 > 0   (LONG positions)
SellPrice = Tradeprice + (y1 * pipsize)                                 //convert pips to price
//
// check the minimun distance between ExitPrice and current price
//
IF abs(close - SellPrice) > PriceDistance THEN
//
// place either a LIMIT or STOP pending order according to current price positioning
//
IF close >= SellPrice THEN
SELL AT SellPrice STOP
ELSE
SELL AT SellPrice LIMIT
ENDIF
ELSE
//
//sell AT MARKET when EXITPRICE does not meet the broker's minimun distance from current price
//
SELL AT Market
ENDIF
ENDIF
IF y2 THEN                                                                 //Place pending STOP order when y2 > 0   (SHORT positions)
ExitPrice = Tradeprice - (y2 * pipsize)                                 //convert pips to price
//
// check the minimun distance between ExitPrice and current price
//
IF abs(close - ExitPrice) > PriceDistance THEN
//
// place either a LIMIT or STOP pending order according to current price positioning
//
IF close <= ExitPrice THEN
EXITSHORT AT ExitPrice STOP
ELSE
EXITSHORT AT ExitPrice LIMIT
ENDIF
ELSE
//
//ExitShort AT MARKET when EXITPRICE does not meet the broker's minimun distance from current price
//
EXITSHORT AT Market
ENDIF