Jan
Participant
Veteran
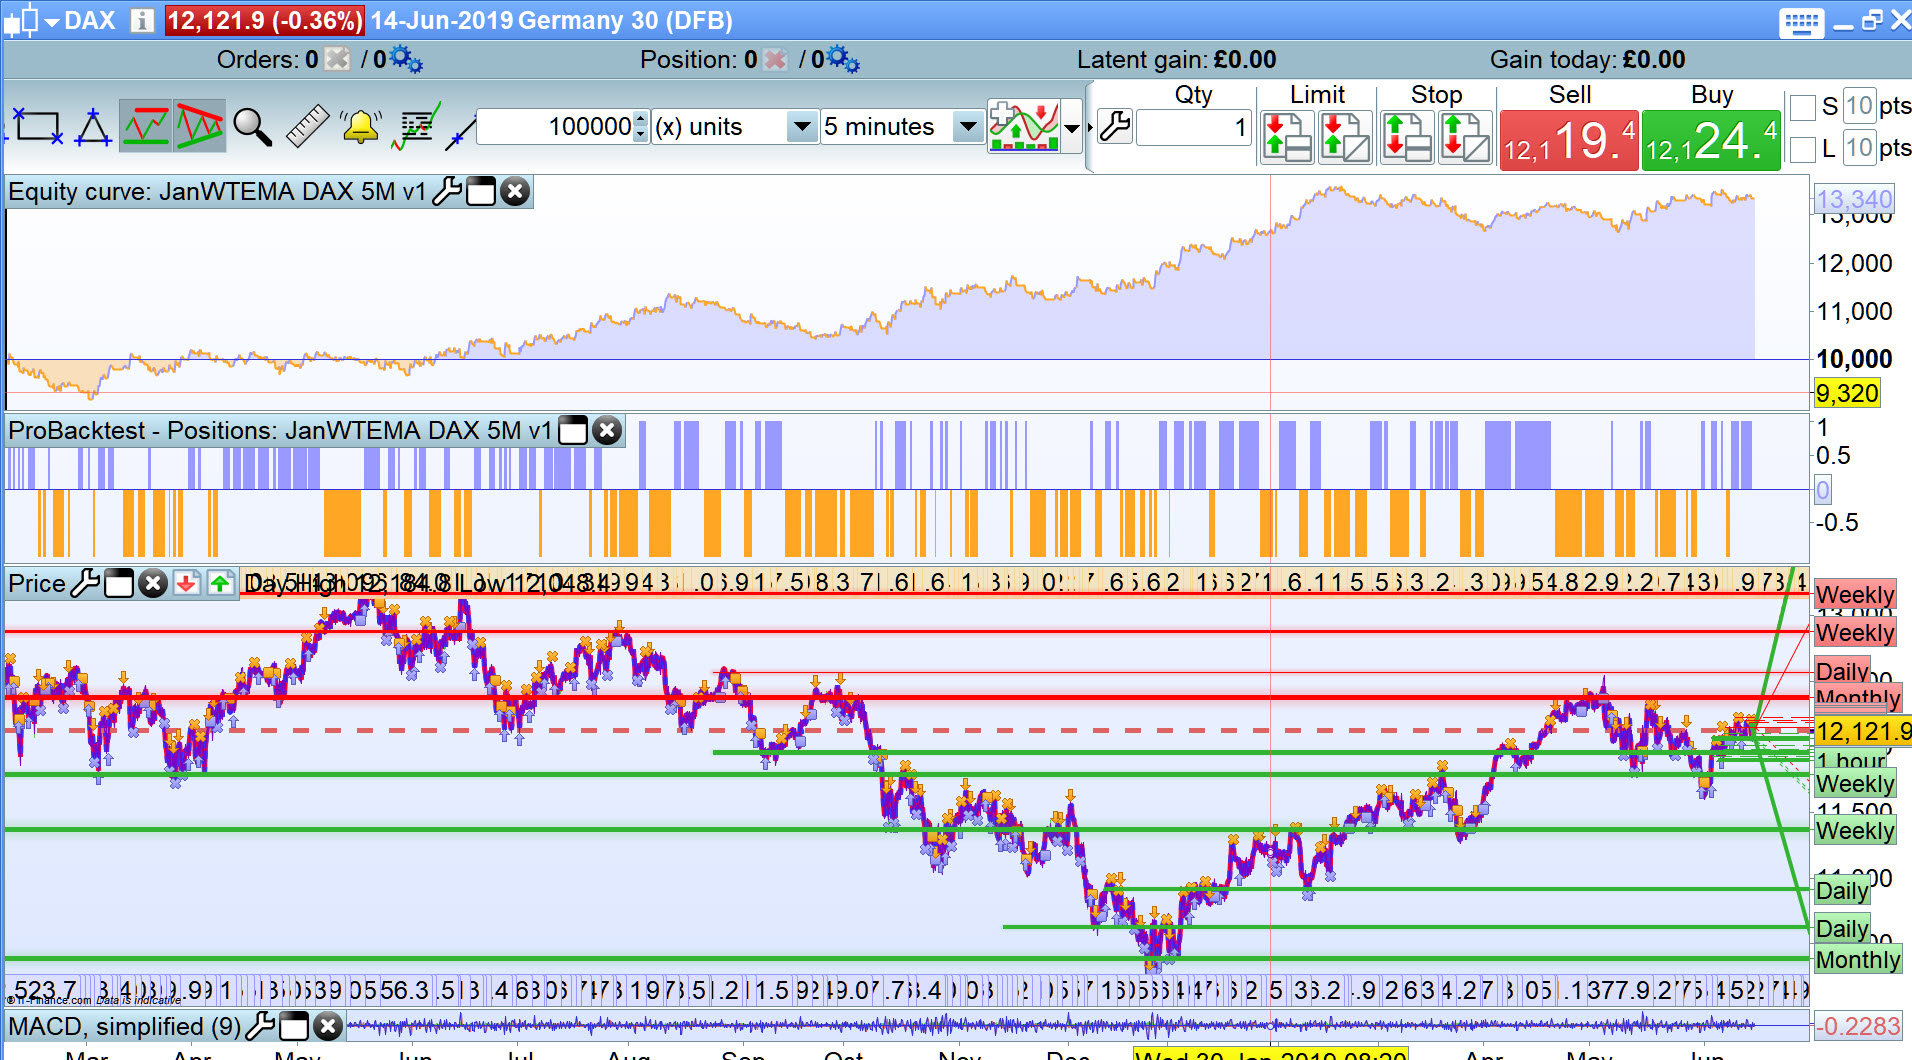
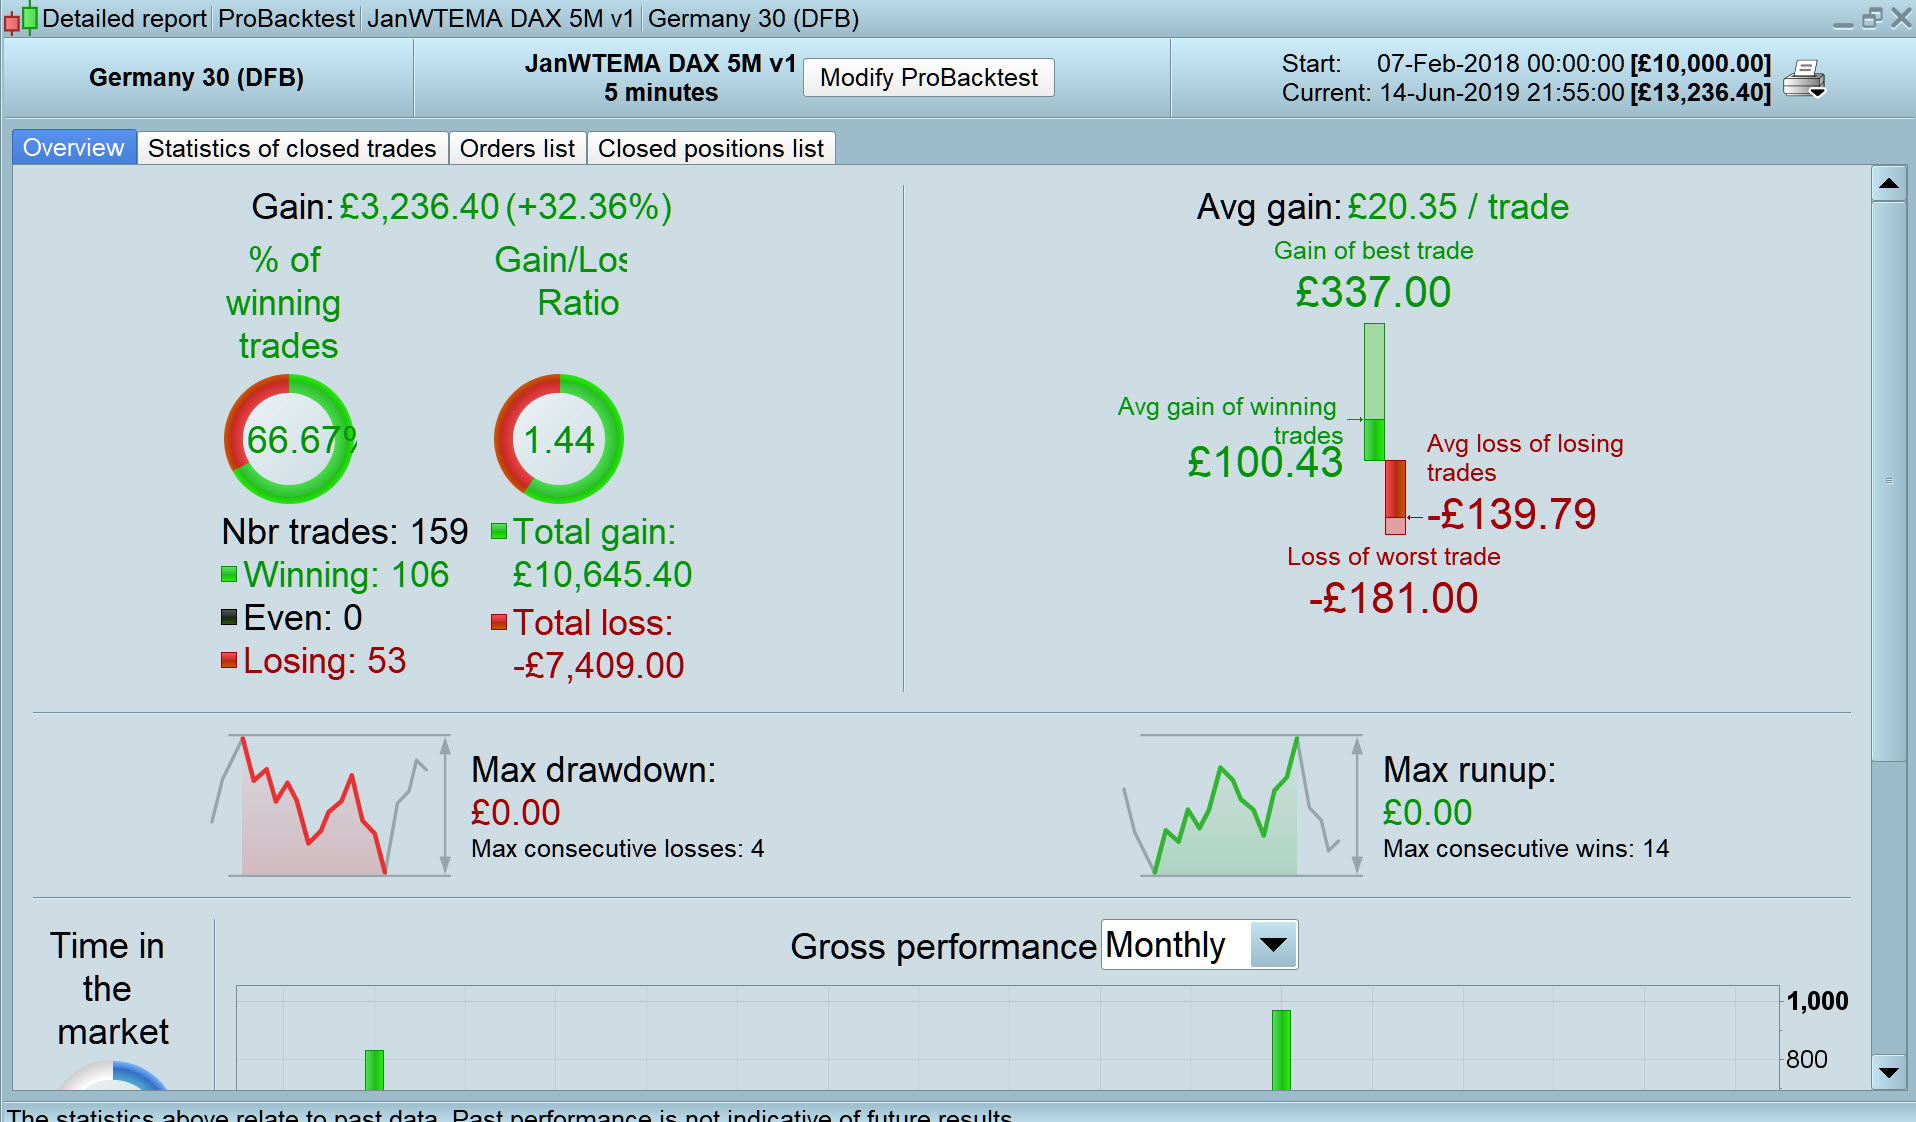
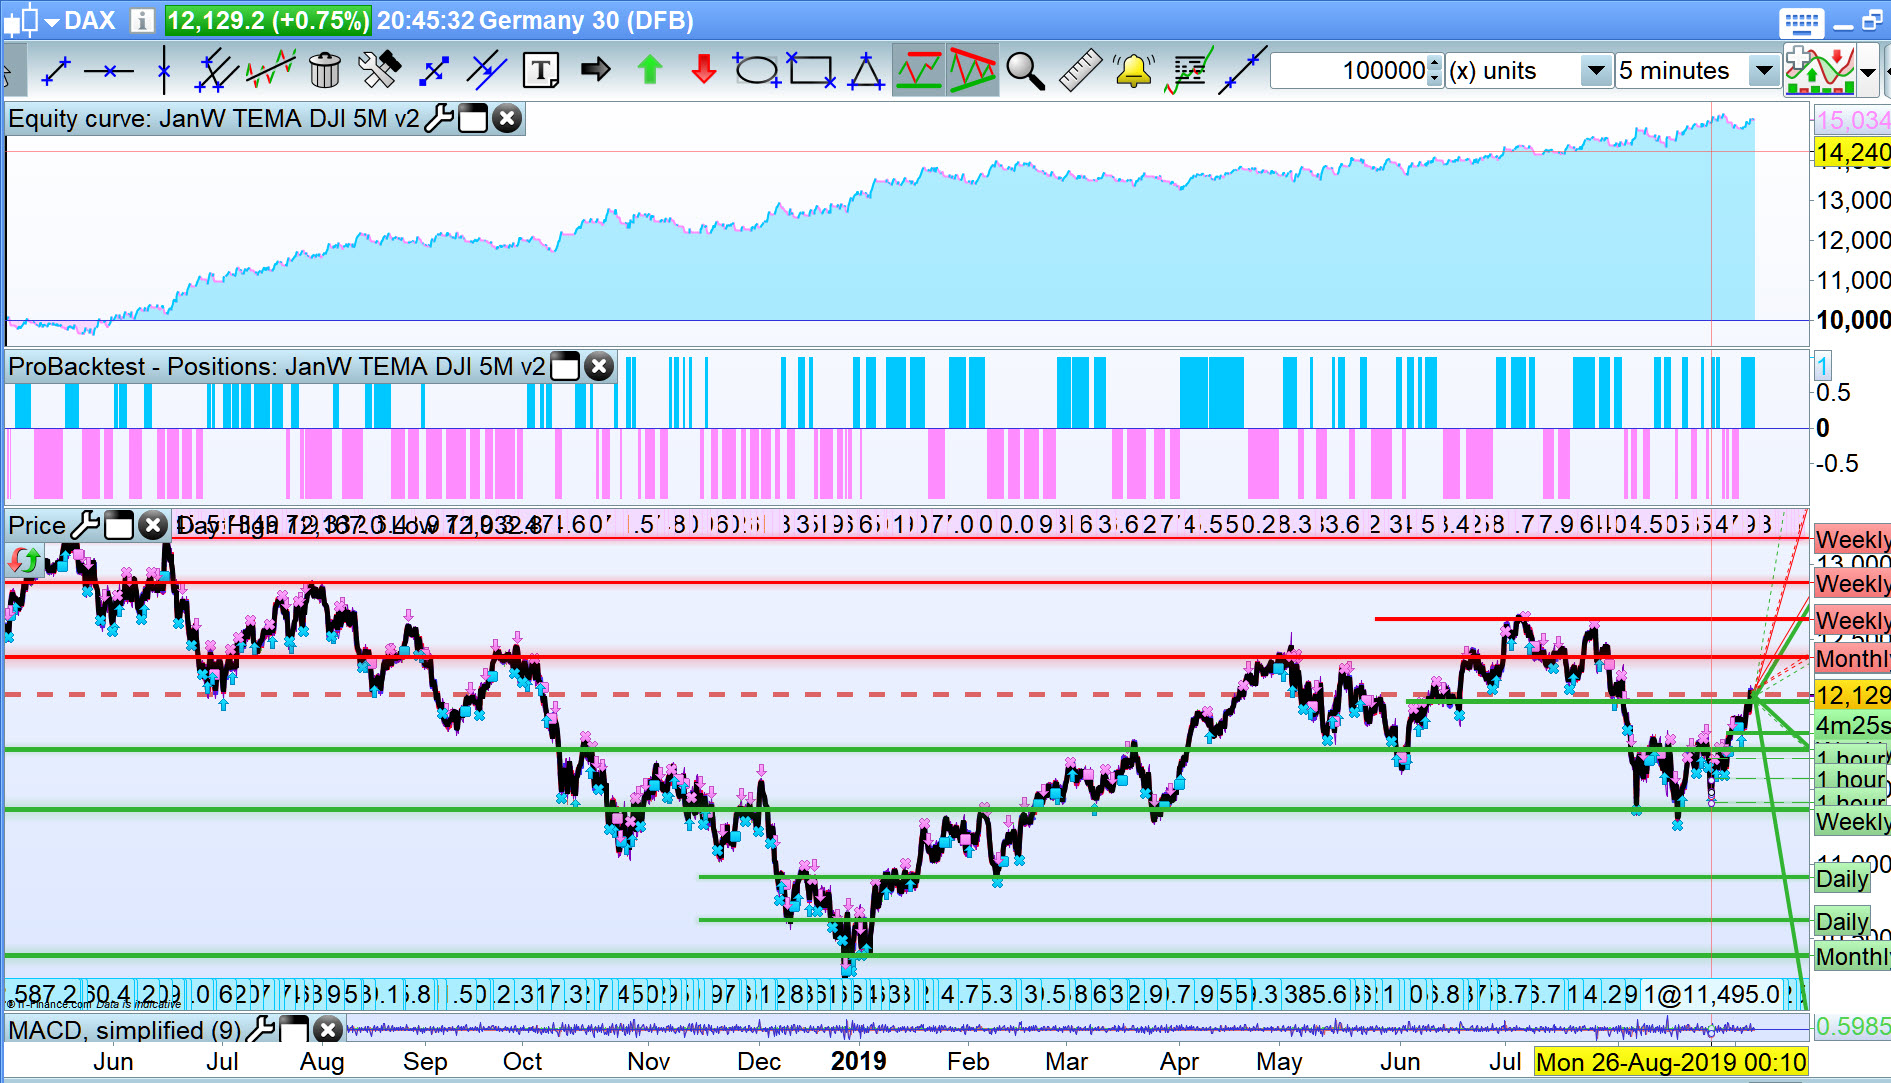
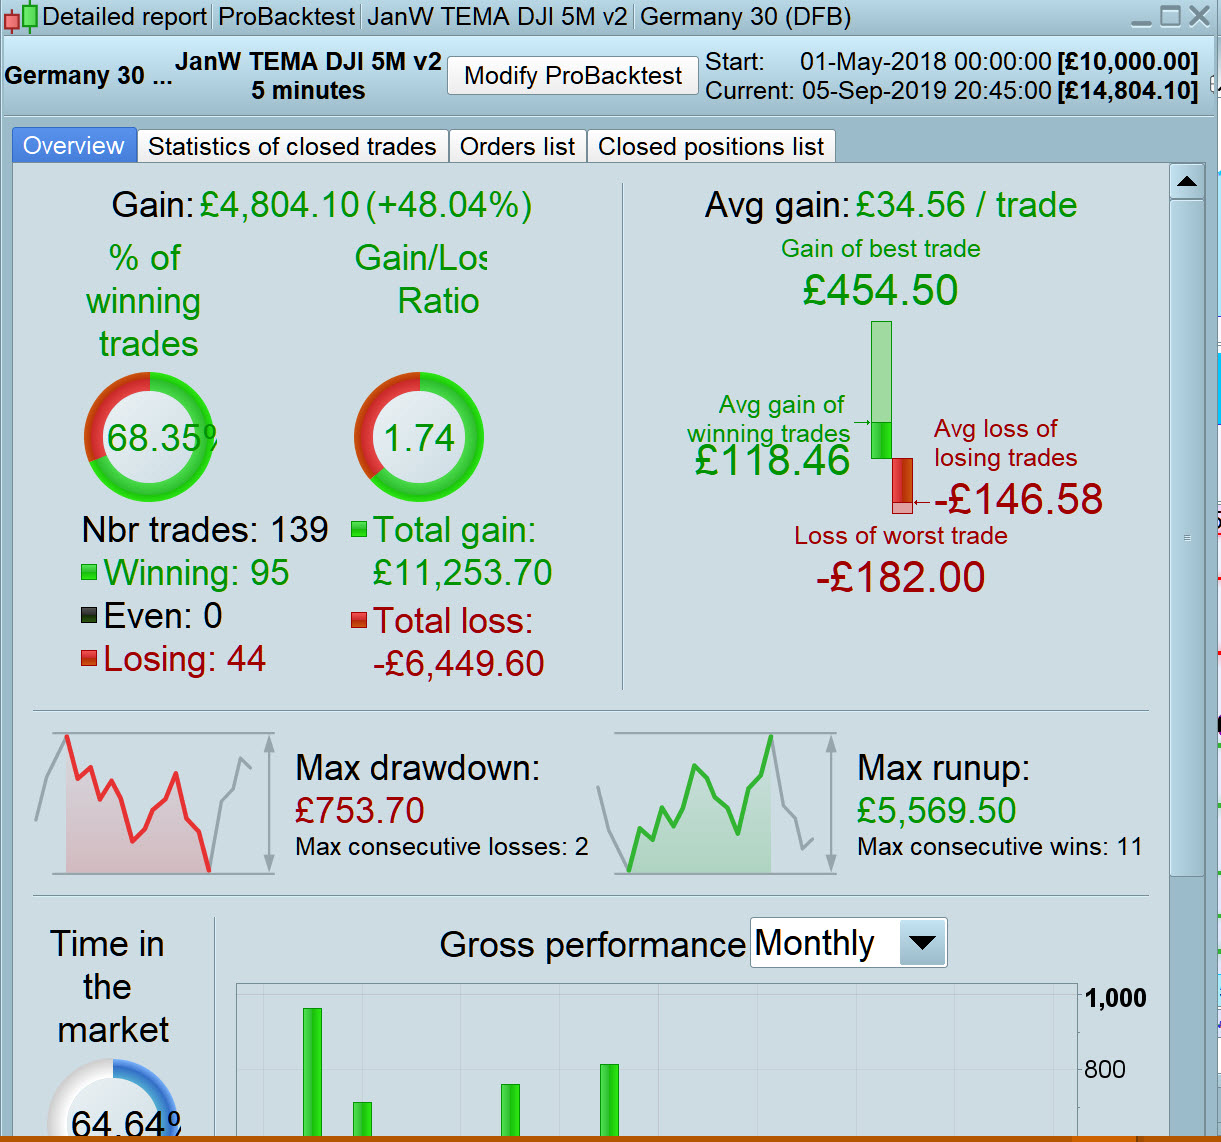
You are invited to comment on the strategy “DI TEMA Trendfollowing strategy on DAX 5 min”
Thank you very much in advance for findings, comments, robustness.
You can find it in the library.
Attached for DAX spread = 2
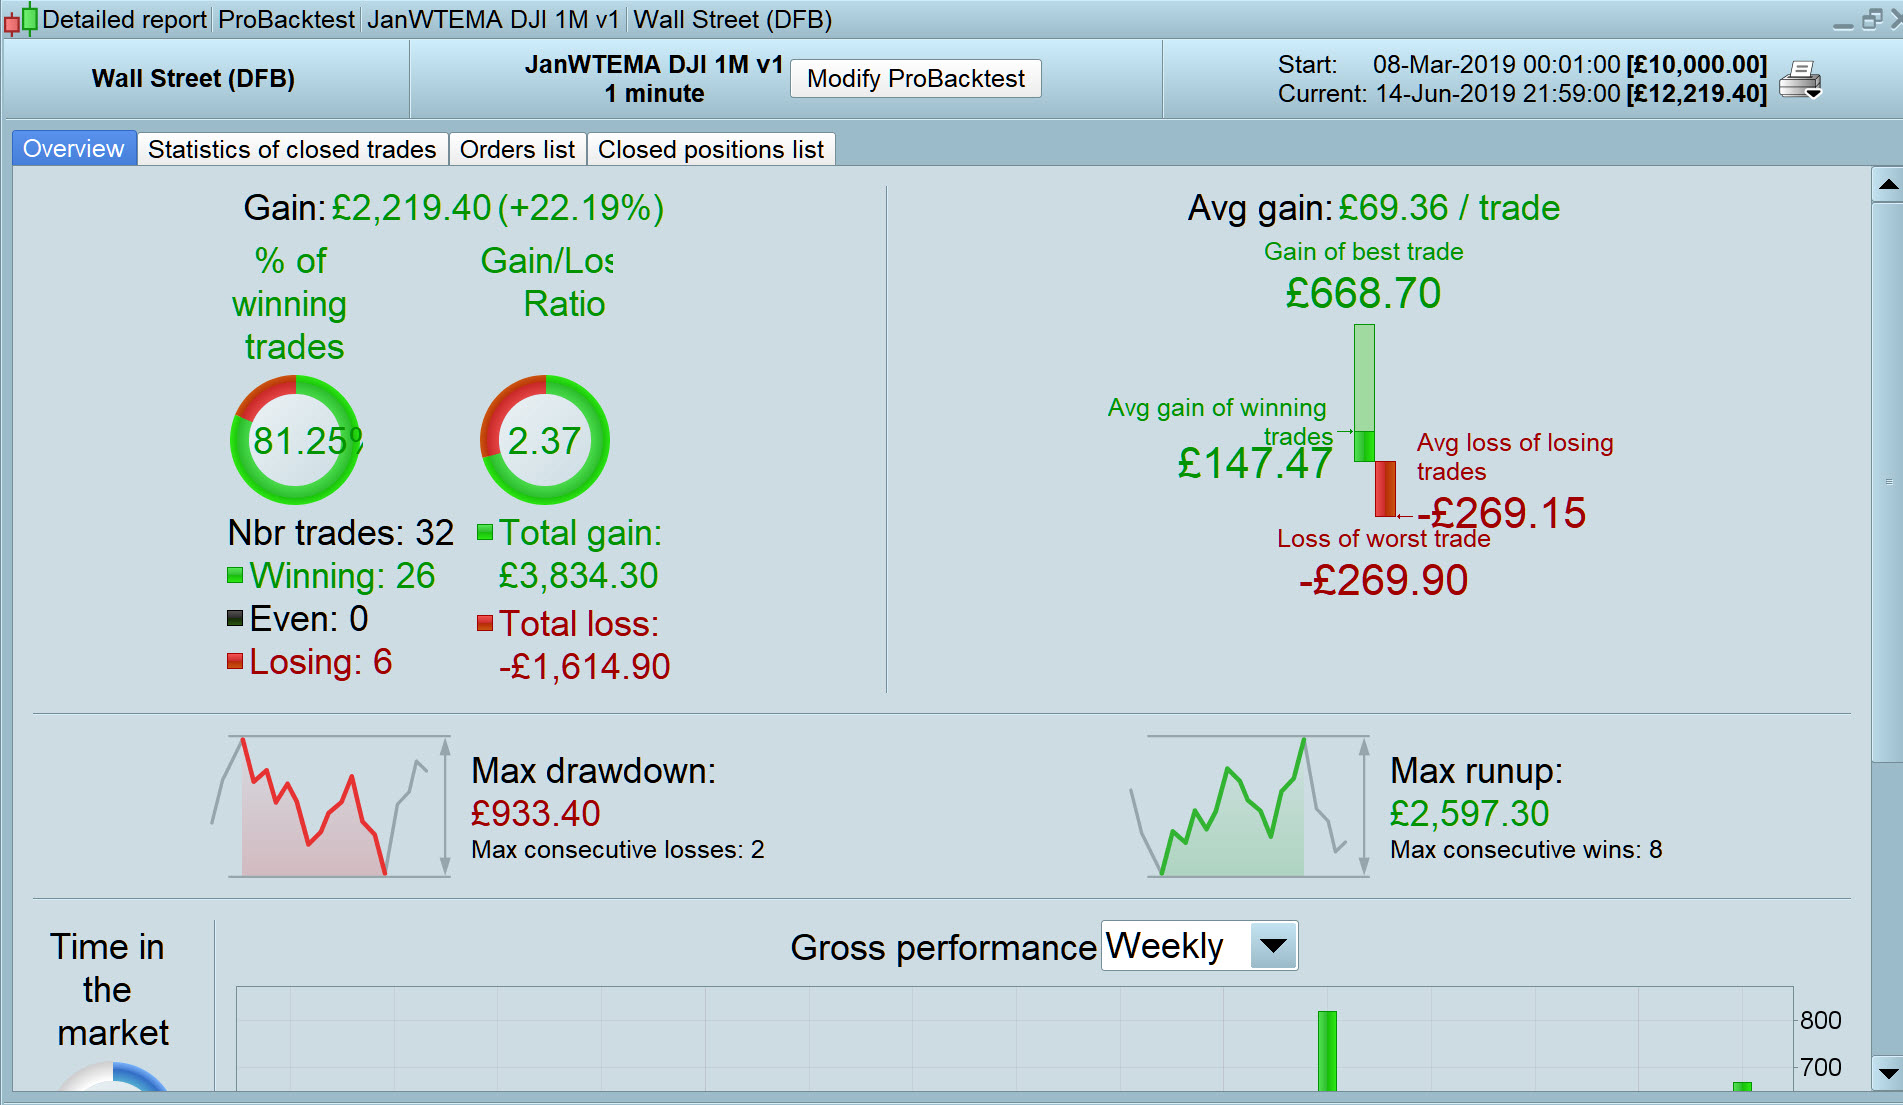
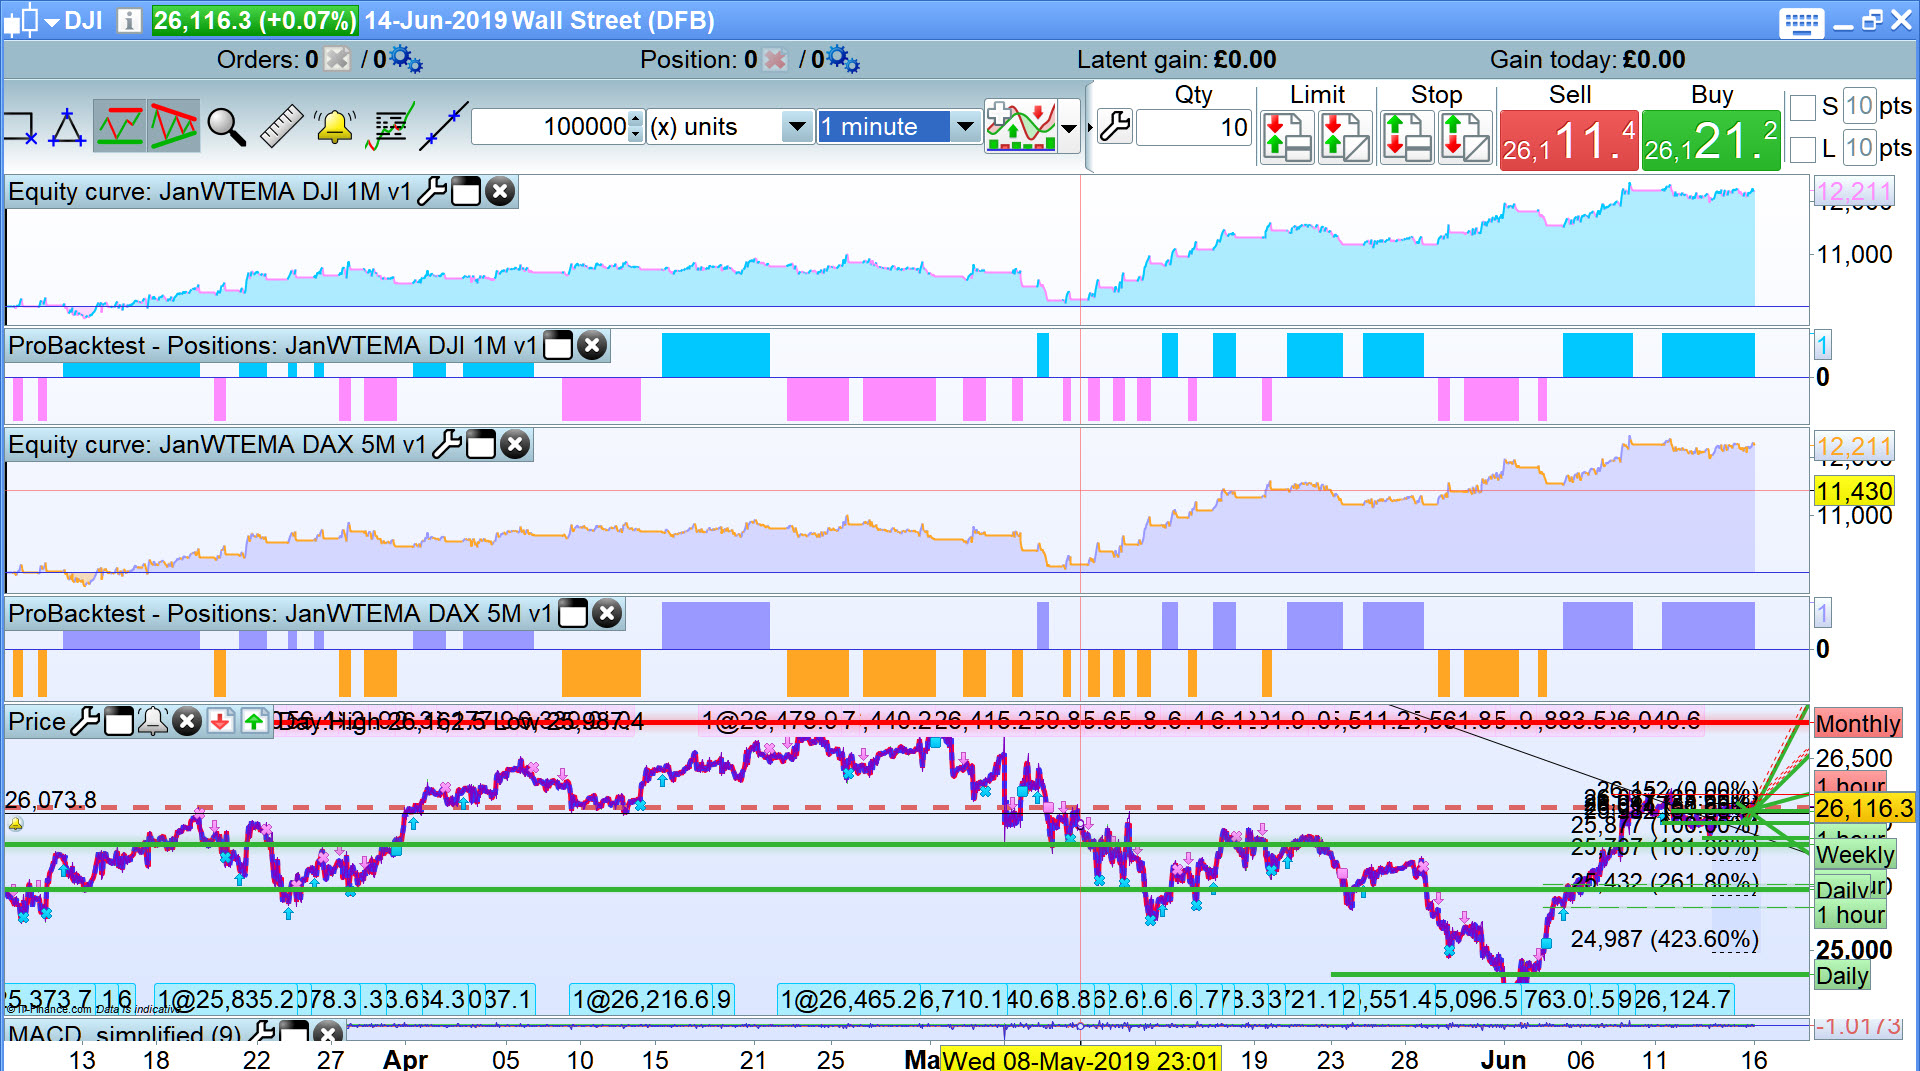
Works even better on DJI 1 min spread = 4
Jan,
thanks for sharing. I played around with time settings but nothing worked.
My results are attached.
/Peter
I’m trying to figure out why leaving out the overnight data makes such a big difference on the outcome as the algo is server side?
I´m using this now with real $ and its working good i use the 30 min chart with settings.
DEFPARAM CumulateOrders = false // Cumulating positions deactivated
//VARIABLES
once SLperc = 105 // Stoploss percentage 105/10000 * Close (150)
once TrailSLPerc = 60 // Trailng Stoploss percentage 85/10000 * Close 60
once Tema2 = 10 // Tema setting for opening long/short positions 10
once DI2 = 7 //DI setting for opening long/short positions 7
once Duration = 12 // number of bars in trade before reducing the trailing stop 12
once Factor = 7/10//factor to reduce trailing stoploss after some time in the trade

once StartE = 74500 //start time for opening positions
once StartL = 103000 //ending time for opening positions (only trading in the morning)
once N = 1 // initieel aantal contracten
OTD = Barindex - TradeIndex(2) > IntradayBarIndex // limits the (opening) trades till 1 per day
kalleklovn – please use the ‘Insert PRT Code’ button to embed code when posting as it makes it much easier for every one to read. I have tidied up your post for you. 🙂
Thanks i´m still new and never really been active on any forums 🙂
@kalleklovn thank you for sharing your settings.
Your share prompted me to look at the 5 min version and I can see that it dropped off in performance after publishing in the library (as so many Systems do).
As seen from attached the drop off just needs a bit of re-opti to get back on track. I found the variables very very responsive!
I’ll try and remember to check the settings regularly! 🙂
Thank you @Jan Wind for sharing this Strategy with us all.
EDIT / PS
The .itf should state DAX (not DJI) … one eye on the TV again, sorry! 🙂
JanParticipant
Veteran
Hello GraHal
“As seen from attached the drop off just needs a bit of re-opti to get back on track. I found the variables very very responsive!
I’ll try and remember to check the settings regularly! 🙂 ”
Do you have any guidelines of re optimizing your auto trading model ? Do you do it every week, and than for 1 year of history for instance ? Or how do you do this ? Re-optimizing implicitly means that you are assuming that the last data gives the best change of predicting future movements. Then a very important question is what is “the best” set of data ?
Kind regards, Jan Wind
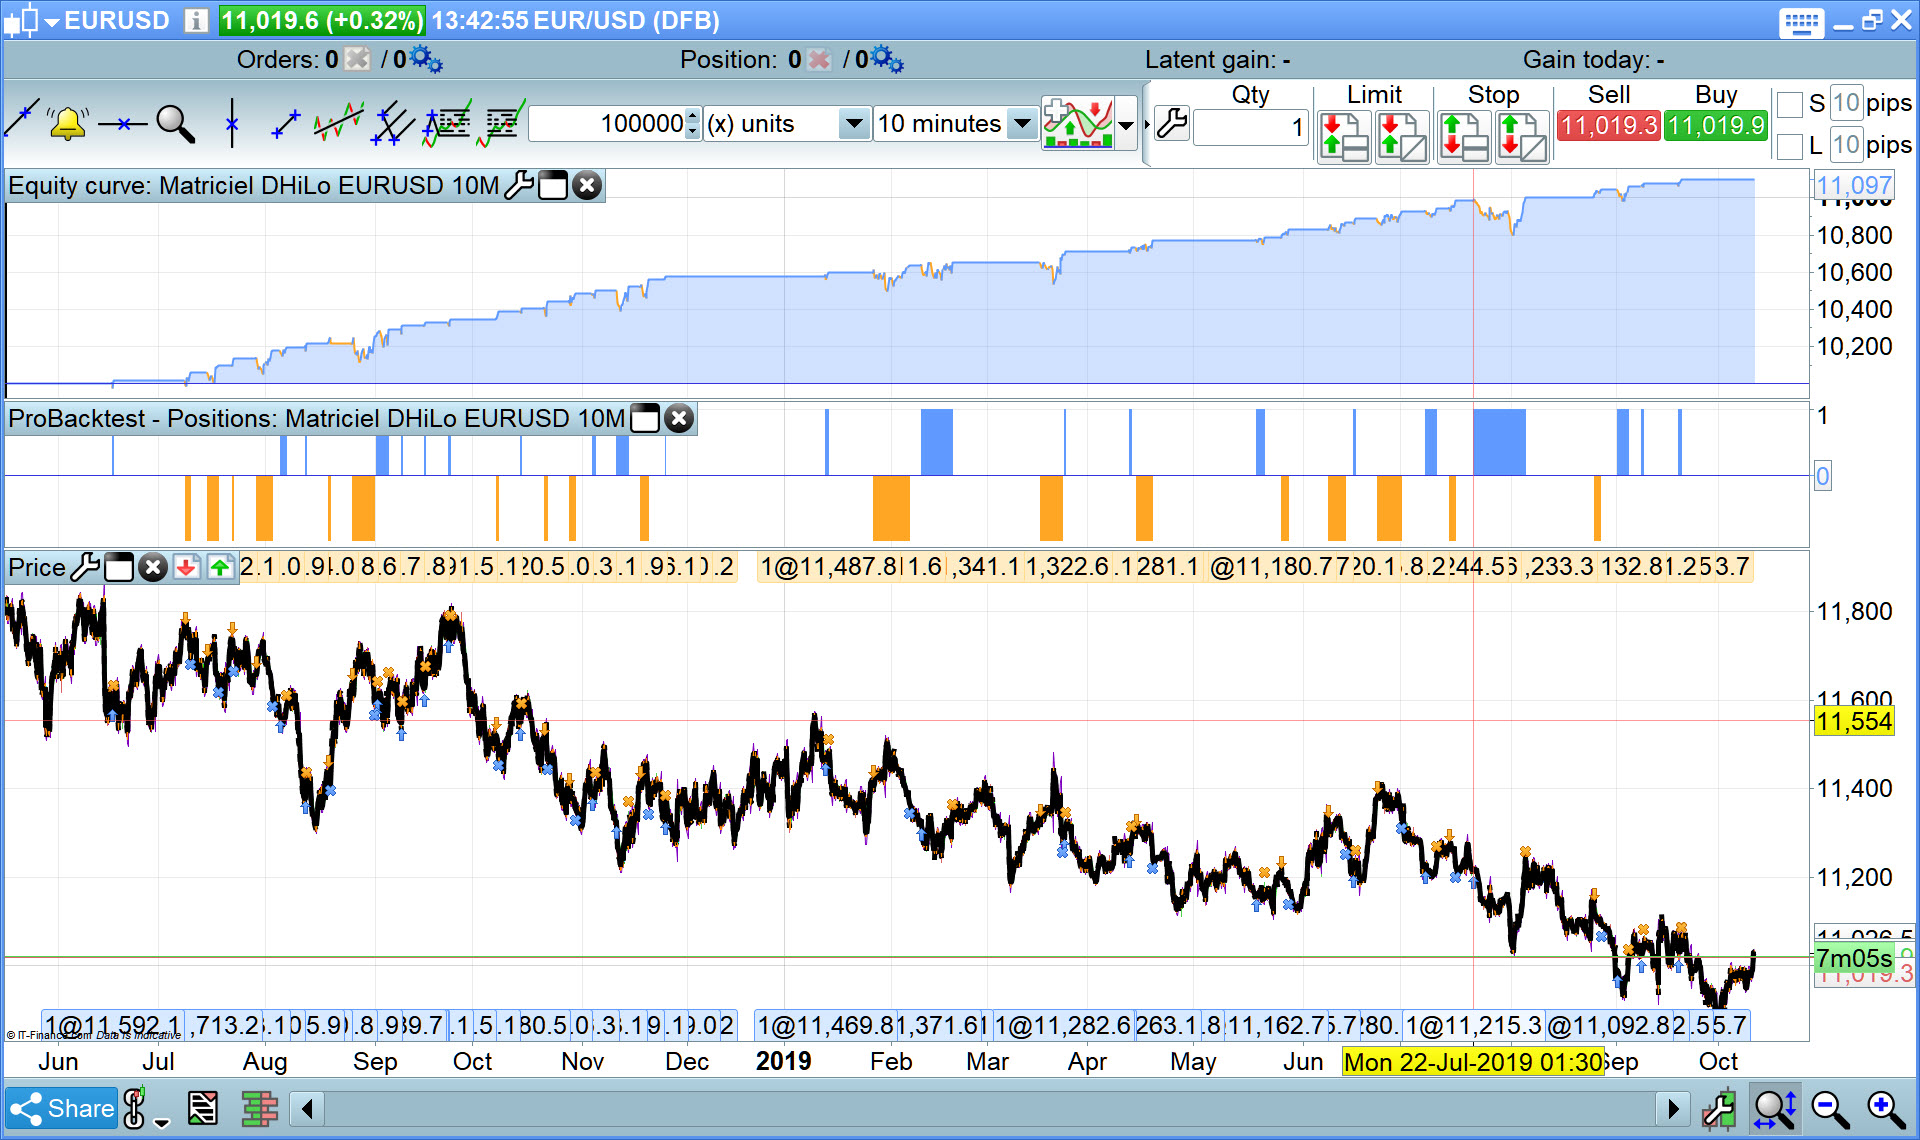
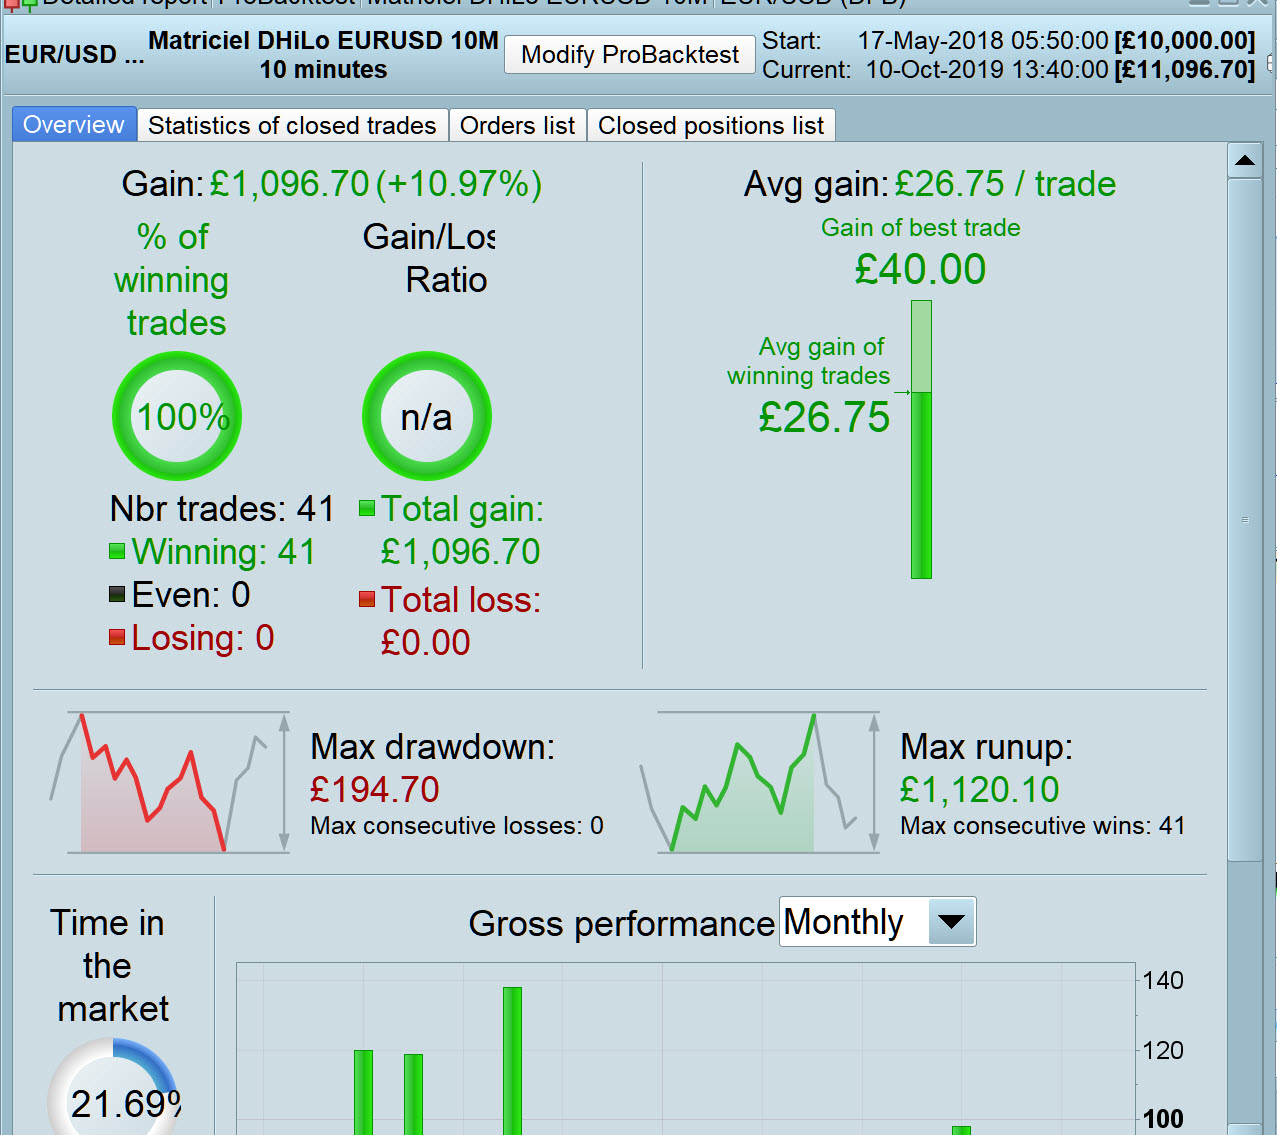
A new strategy for Jan Wind !
Works on EUR/USD 15 minutes timeframe.
DEFPARAM CumulateOrders = True
DEFPARAM PRELOADBARS = 10000

daysForbiddenEntry = OpenDayOfWeek = 6 OR OpenDayOfWeek = 0

Horaire = time >= 000000 and time <= 200000

CloturePartielle = 1// 1 = ON, 0 = OFF
PositionsizeA = 1
PositionsizeV = 1
MAXSHARES = abs(COUNTOFPOSITION) <= 19

IF CloturePartielle THEN
PositionsizeA = 4
PositionsizeV = 3
ENDIF

MM = Average[56,3](totalprice)

Newhighest = max(DHigh(0),DHigh(1))
Newlowest = min(DLow(0),DLow(1))

Milieu = (Newhighest+Newlowest)/2
Surachat = average[10,4]((Newhighest+Milieu)/2)
Survente = average[10,4]((Newlowest+Milieu)/2)

CA = (MM > Surachat) and (close crosses over Milieu)
CV = (MM < Survente) and (close crosses under Milieu)

// Long Entries
IF Horaire AND CA AND MAXSHARES AND not daysForbiddenEntry AND NOT SHORTONMARKET THEN
BUY PositionsizeA CONTRACTS AT MARKET
ENDIF

IF CloturePartielle THEN
IF LONGONMARKET AND COUNTOFLONGSHARES <= 16 THEN
SELL 1 CONTRACTS AT TRADEPRICE + 40*pointsize LIMIT
ENDIF

IF LONGONMARKET AND COUNTOFLONGSHARES <= 4 THEN
SELL 1 CONTRACTS AT TRADEPRICE + 20*pointsize LIMIT
ENDIF

IF LONGONMARKET AND COUNTOFLONGSHARES <= 6 THEN
SELL 1 CONTRACTS AT TRADEPRICE + 18*pointsize LIMIT
ENDIF
ENDIF

IF LONGONMARKET AND summation[35](close < close[6]) = 35 THEN
SELL AT MARKET
ENDIF

// Short Entries
IF Horaire AND CV AND MAXSHARES AND not daysForbiddenEntry AND NOT LONGONMARKET THEN
SELLSHORT PositionsizeV CONTRACTS AT MARKET
ENDIF

IF CloturePartielle THEN
IF SHORTONMARKET AND COUNTOFSHORTSHARES <= 20 THEN
EXITSHORT 1 CONTRACTS AT TRADEPRICE - 78*pointsize LIMIT
ENDIF

IF SHORTONMARKET AND COUNTOFLONGSHARES <= 1 THEN
EXITSHORT 1 CONTRACTS AT TRADEPRICE - 40*pointsize LIMIT
ENDIF
ENDIF

IF SHORTONMARKET AND summation[32](close > close[6]) = 32 THEN
EXITSHORT AT MARKET
ENDIF

//MFE
//trailing stop
trailingstop = 33

//resetting variables when no trades are on market
if not onmarket then
MAXPRICE = 0
MINPRICE = close
priceexit = 0
endif

//case SHORT order
if shortonmarket then
MINPRICE = MIN(MINPRICE,close) //saving the MFE of the current trade
if tradeprice(1)-MINPRICE>=trailingstop*pointsize then //if the MFE is higher than the trailingstop then
priceexit = MINPRICE+trailingstop*pointsize //set the exit price at the MFE + trailing stop price level
endif
endif

//case LONG order
if longonmarket then
MAXPRICE = MAX(MAXPRICE,close) //saving the MFE of the current trade
if MAXPRICE-tradeprice(1)>=trailingstop*pointsize then //if the MFE is higher than the trailingstop then
priceexit = MAXPRICE-trailingstop*pointsize //set the exit price at the MFE - trailing stop price level
endif
endif

//exit on trailing stop price levels
if onmarket and priceexit>0 then
EXITSHORT AT priceexit STOP
SELL AT priceexit STOP
endif

//SET TARGET pPROFIT 46
SET STOP pLOSS 200
Thank you for your excellent work @Matriciel, but as it is a different strategy than this Topic (DI TEMA) would it not be better posted as a separate topic then the Community can easier discuss / comment / improve your strategy?
Not that it needs much improving! 🙂
I reduced to 1 Lot for easier comparison to other Systems, but we can’t do Fwd Test anyway with a strategy that Sells / ExitShort on partial Lot size (as your code does)… it has to be for example Sell at ….
I have enabled tick by tick mode! 🙂
Hi Grahal,
I know this is not the place for this strategy but it was Jan Wind who asked me because I have problems to copy / paste in the subject concerned.