Dax adaptable strategy Breackout/Mean reversion

Viewing 15 posts - 16 through 30 (of 83 total)
  • Author
    Posts
  • #33249 quote
    StantonRStantonR
    Participant
    Senior

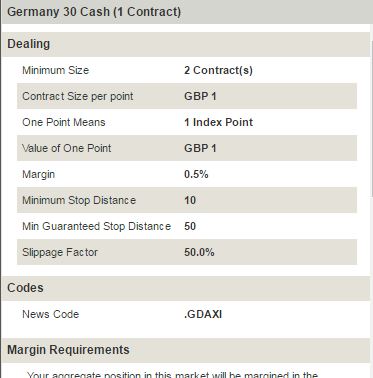
    Please could somebody explain this to me.

    Is this minimum 2 contracts or 1 contract per point.

    Capture2.jpg Capture2.jpg
    #33253 quote
    GraHalGraHal
    Participant
    Master

    I would interpret it as minimum 2 contracts @ £1 per point.

    #33254 quote
    StantonRStantonR
    Participant
    Senior

    It’s strange because I am running a dax strategy live that trades 1 contract but when I trade manually I have to enter minimum 2 contracts. Must be a glitch in ig / pro real time connection. Happy glitch I am not complaining.

    #33310 quote
    Francesco78Francesco78
    Participant
    Master

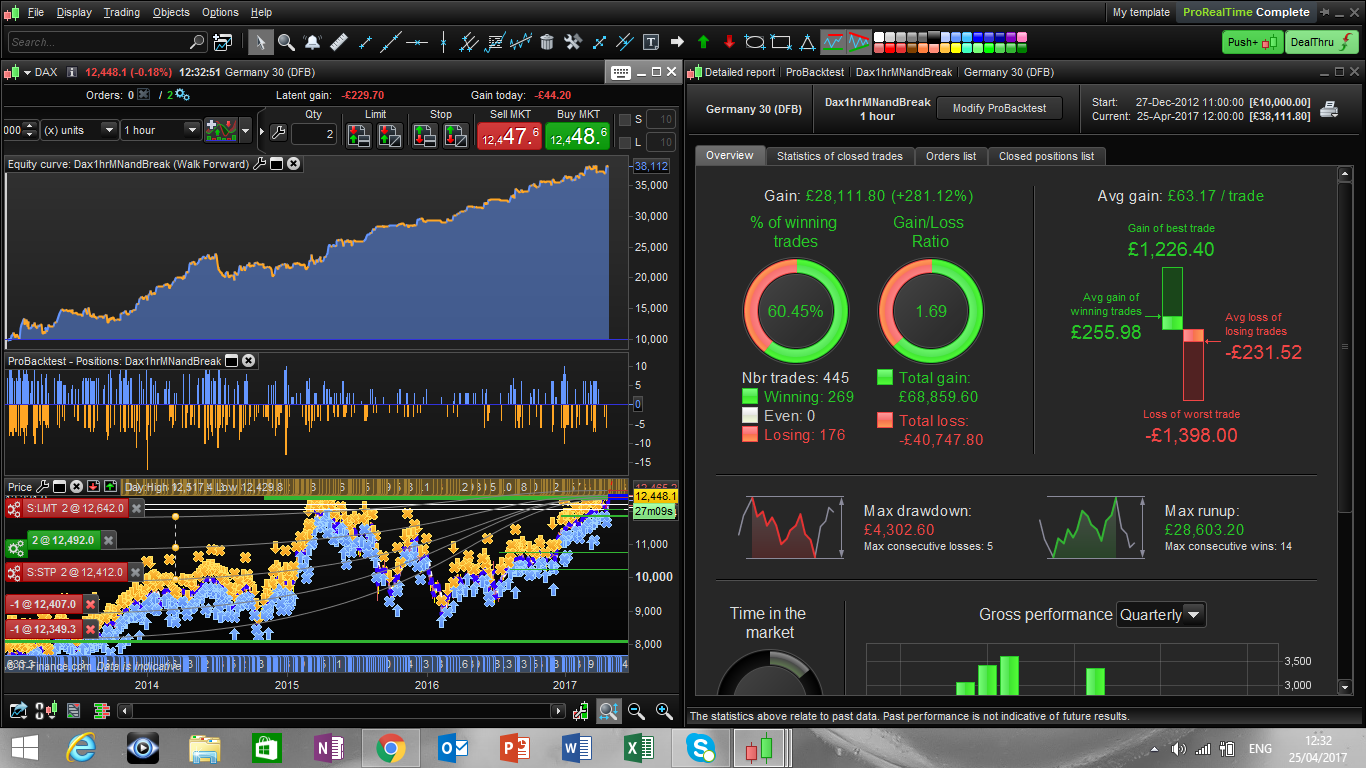
    have done some more work on this code, I noticed that the strategy was poor when ATR (or VOl) was low, so I thought to make a position sizing inversely proportional to the ATR.

    Furthermore I created 2 scenarios,


    1 ATR is bigger than x

    2 ATR is smaller than x


    Now the curve in the 1hr case looks steeper and smoother.


    I attach the results.


    Regards

    GraHal, victormork and Nicolas thanked this post
    Dax1hrMNandBreakv2-1.itf dax_1hr-2.png dax_1hr-2.png
    #33716 quote
    Francesco78Francesco78
    Participant
    Master

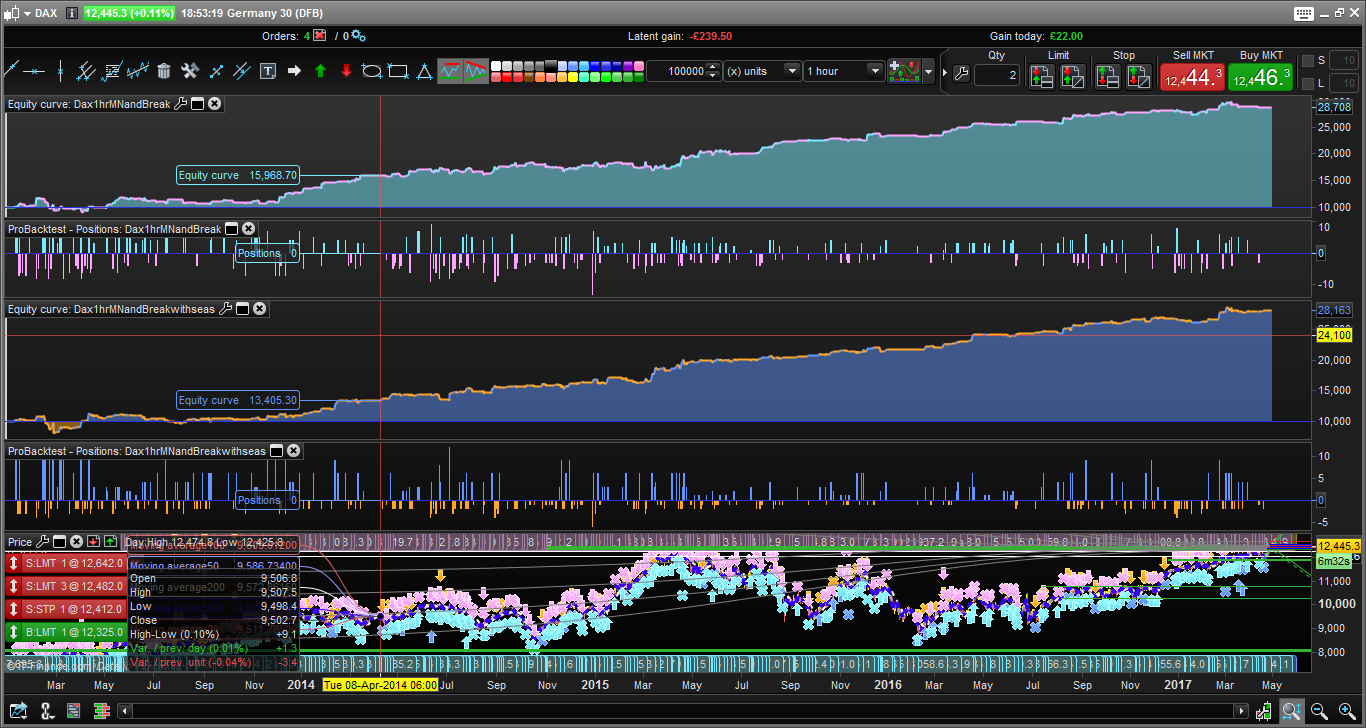
    I have incorporated seasonality factor from Pathfinder Dax

    Here are the results and the code

    Regards

    Francesco

    reb and Nicolas thanked this post
    Dax1hrMNandBreakv2withseas-1.png Dax1hrMNandBreakv2withseas-1.png Dax1hrMNandBreakwithseas.itf
    #33725 quote
    NicolasNicolas
    Keymaster
    Legend

    Thank you Francesco, new ideas are always refreshing!

    #34291 quote
    Cosmic1Cosmic1
    Participant
    Senior

    Hey Francesco, following on from our discussion on your strategies page.

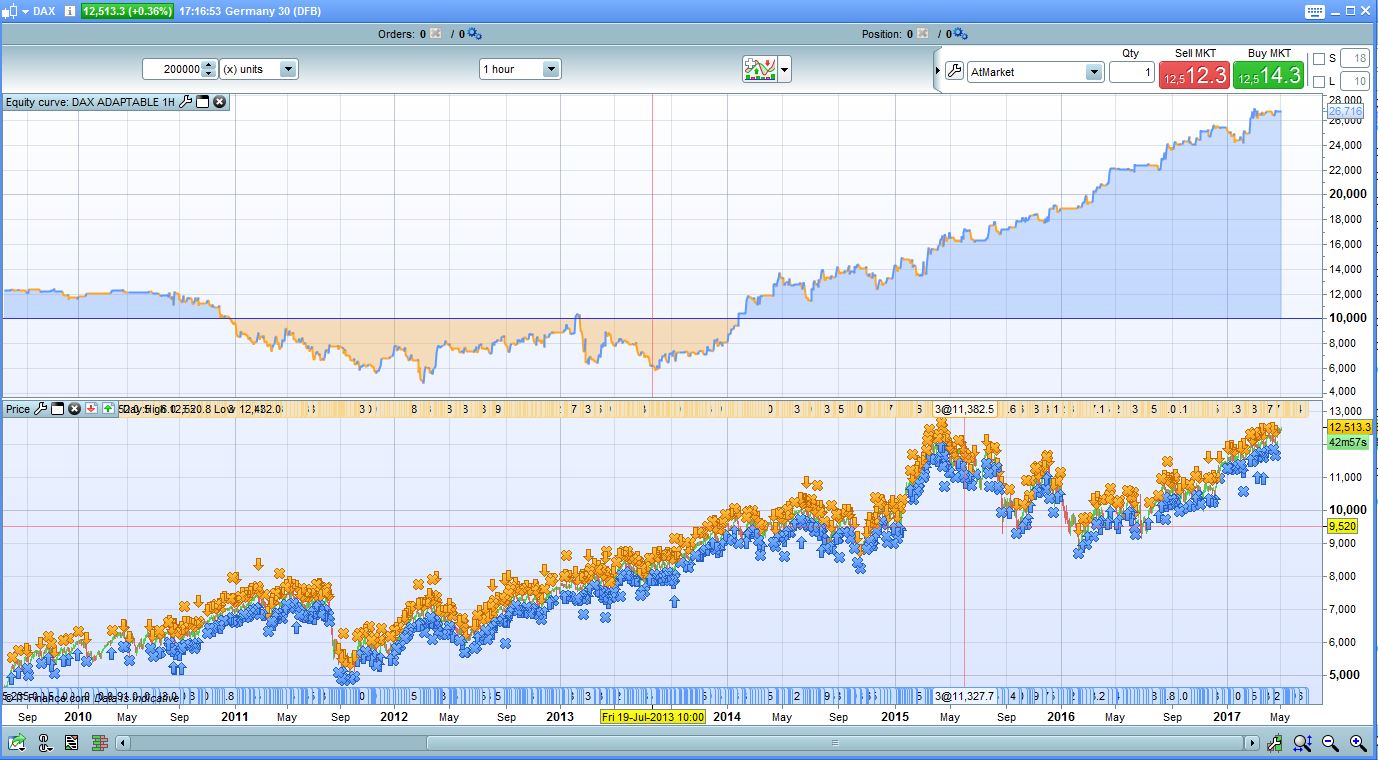
    I tried the code you pasted on 200k units but the same story as 30min. Classic curve fitted picture. I’m not a fan of the seasonal code, especially splitting the months in to two parts but will keep it in there for testing.

    I will try to make some time to run an IN/OUT sample on your variables on 200k and let you know the results soon.

    Henrik thanked this post
    adaptable.jpg adaptable.jpg
    #34294 quote
    Francesco78Francesco78
    Participant
    Master

    Thanks a lot Cosmic1 for your follow up. Very kind of you to do the test on 200k bars.

    There are a few variables in the code so I was expecting curve fitting to a higher then necessary degree.

    I hope further discussion could help in finding ideas that decrease the amount of fine tuning and maybe we could come up with a more general framework.

    Regards.

    Francesco

    #34305 quote
    NicolasNicolas
    Keymaster
    Legend

    Avoid overfitting:

    Develop, code and tune your idea on 70% of the history. If it looks ok, do a final backtest on the last 30% of the history. IS/OOS should be your best companion 🙂

    EDIT: By looking twice on the screenshot Cosmic1 provided, the final look of the equity curve depends a lot of when you start the backtest. Your strategy didn’t loose so much in the past, so please don’t throw this idea to garbage! 🙂

    Francesco78 thanked this post
    #34348 quote
    Cosmic1Cosmic1
    Participant
    Senior

    I agree 70/30 IN/OUT sample is your best friend.

    I also agree not to bin it as some modifications could work here. It’s certainly worth a try.

    I tried a quick IN/OUT on adxval, atrmin, m, and n. This did not work too well but I have to admit this is a quick and dirty test before jumping in to the code to fully understand everything about it.

    Francesco, you will have a better understanding on what will and wont work. Can you try on 100k units but IN/OUT sample? Let me know if anything works for you? Then I can run a similar approach to 200k…

    Francesco78 thanked this post
    #34349 quote
    Francesco78Francesco78
    Participant
    Master

    Absolutely Cosmic1, will work on it tomorrow afternoon. At your disposal for any question about the code.

    Best

    Francesco

    Cosmic1 thanked this post
    #34418 quote
    Francesco78Francesco78
    Participant
    Master

    Cosmic1,

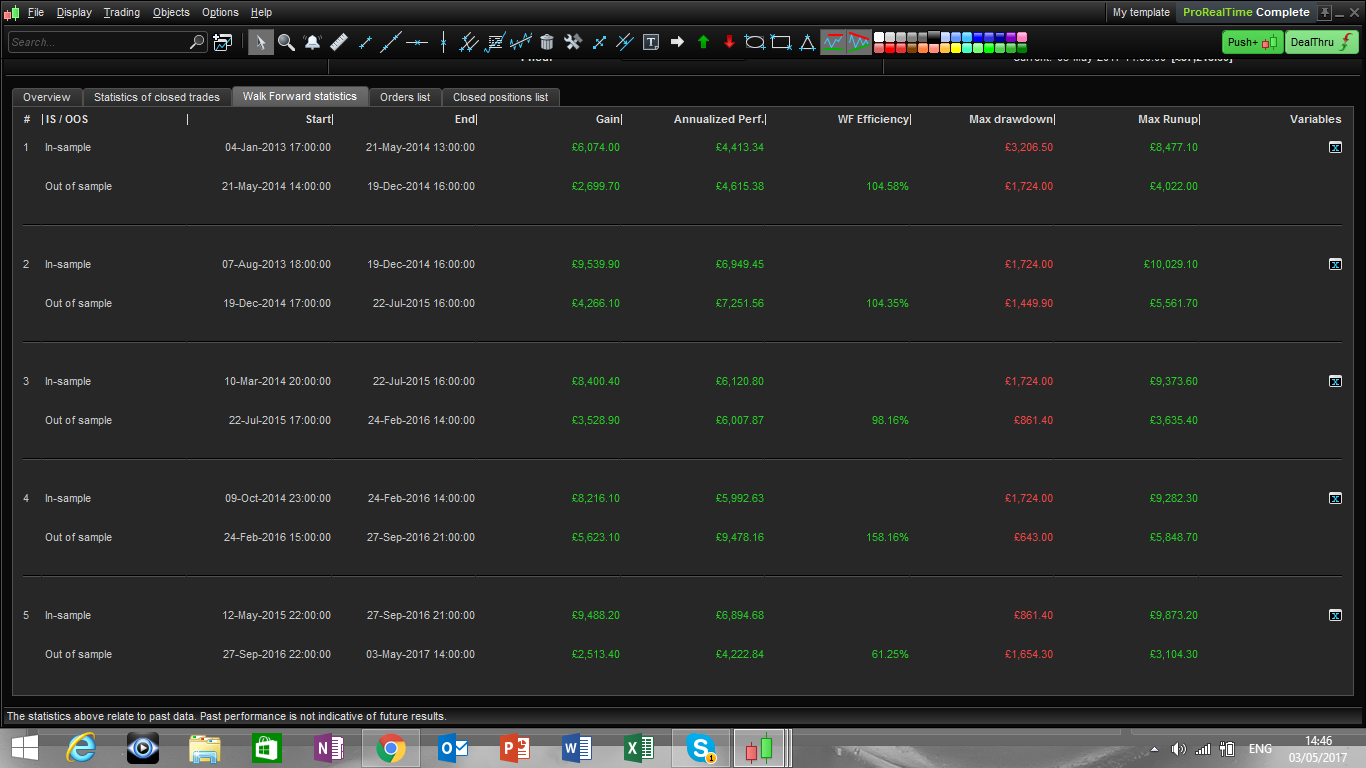
    I have tun a wf test 70/30 for 5 windows.

    the results are quite good for the 100,000 bar case as far I understand as all the WF efficiency are well above 50%

    I attach the results.

    Maybe this strategy just doesnt work before 2014, but in this market I think it makes sense.

    Please let me know your thoughts about it.

    GraHal thanked this post
    wfresults.png wfresults.png
    #34421 quote
    Francesco78Francesco78
    Participant
    Master

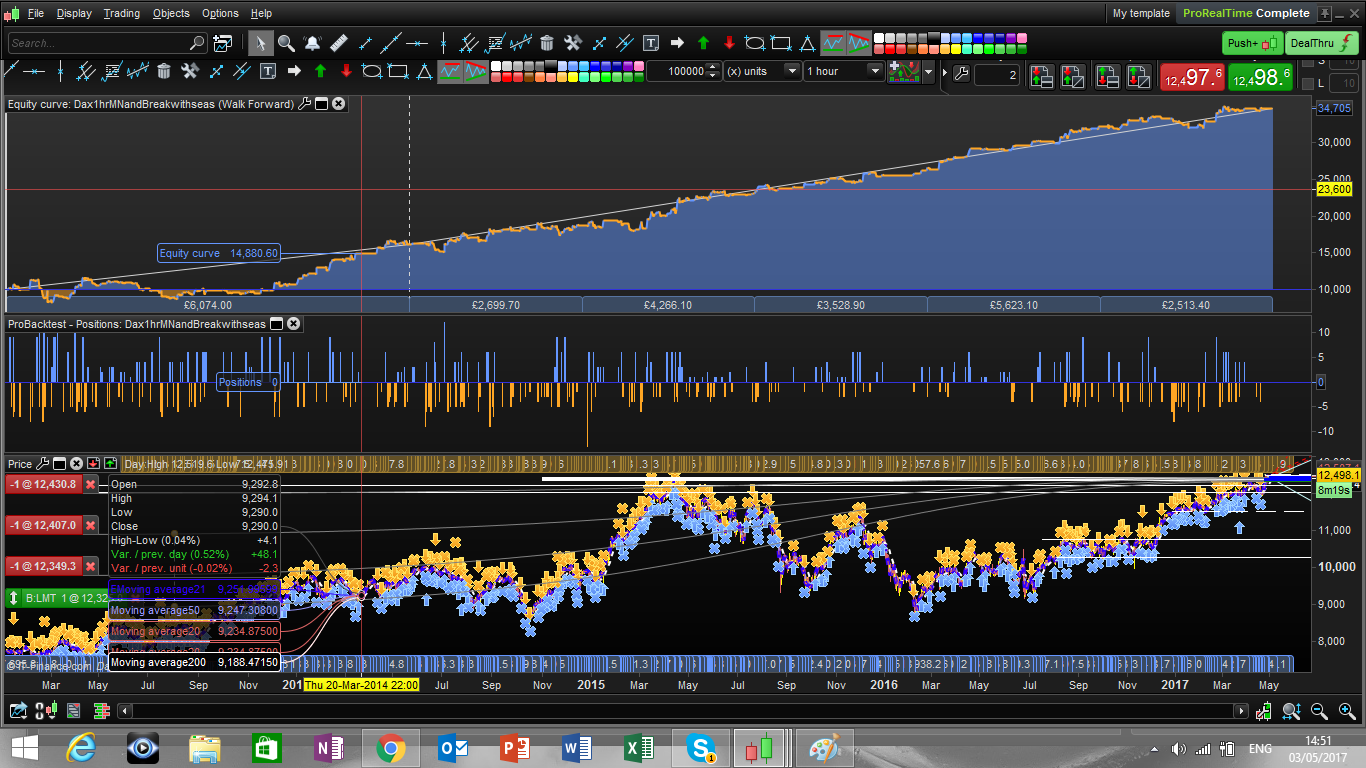
    and the equity line..

    wfchart.png wfchart.png
    #34443 quote
    Francesco78Francesco78
    Participant
    Master

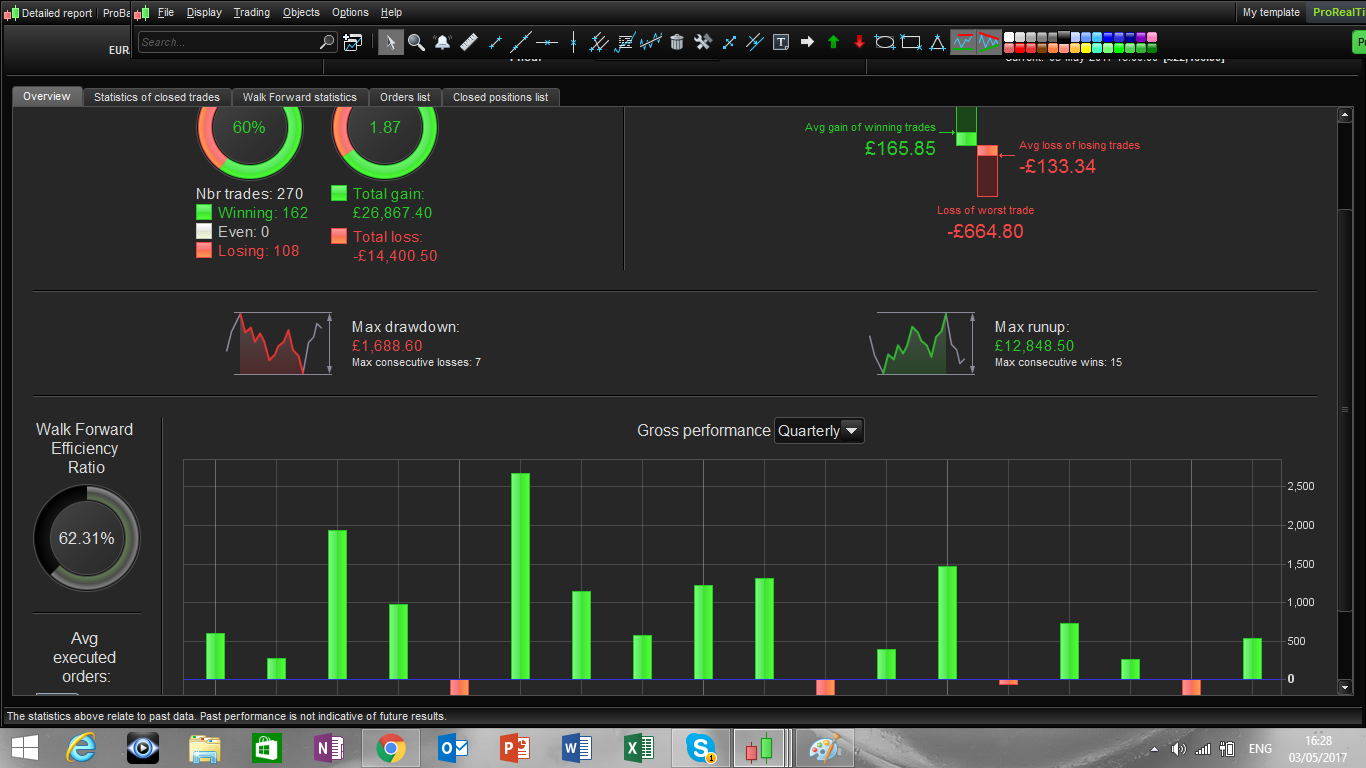
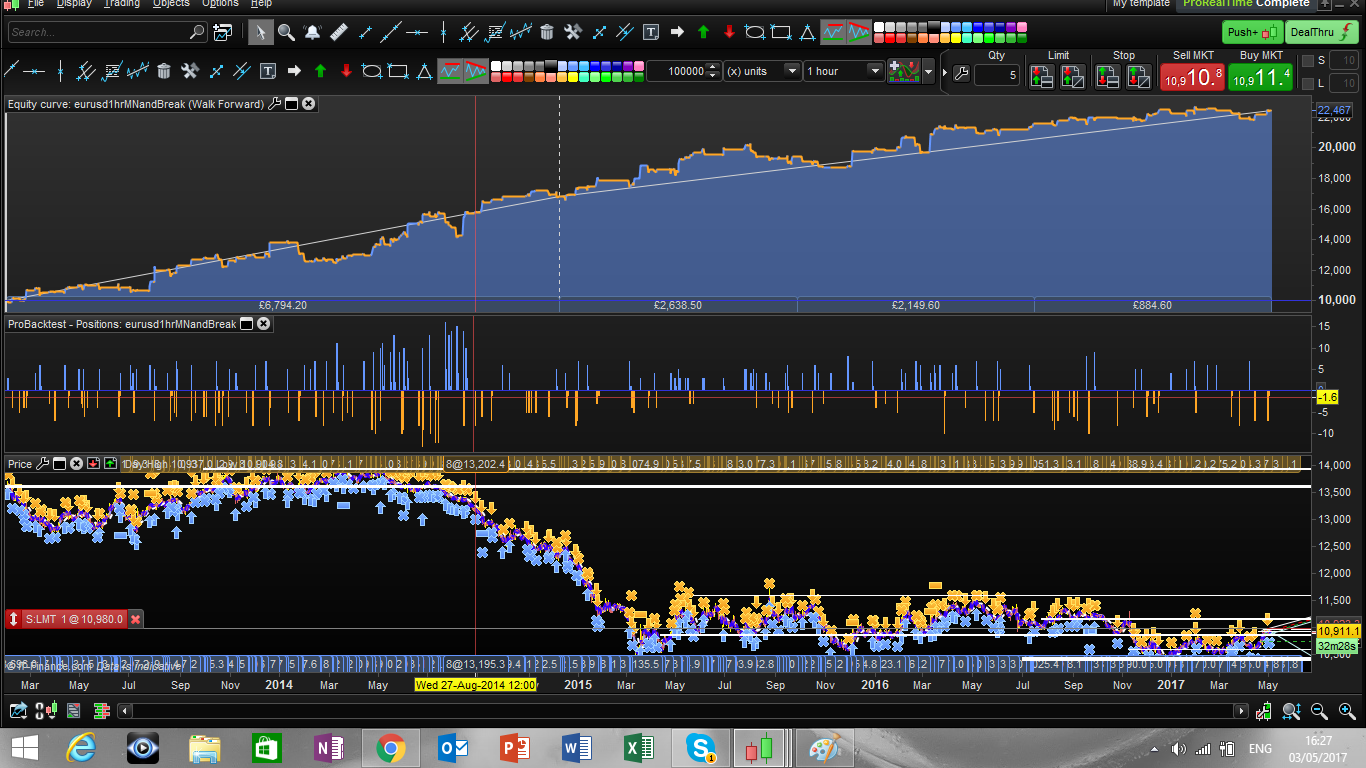
    I have also tried with EURUSD, the results are less good but still accettable.

    Attached.

    Regards

    Francesco

    eurusdwf_2.png eurusdwf_2.png eurusdwf_2-1.png eurusdwf_2-1.png
    #34447 quote
    Francesco78Francesco78
    Participant
    Master
Viewing 15 posts - 16 through 30 (of 83 total)
  • You must be logged in to reply to this topic.
ProRealAI ProRealAI New

Stuck on this ProBuilder code?

Describe what this topic is trying to build, in plain English, and ProRealAI writes the ProRealTime™ indicator, screener or system for you.

Available in 7 languages
Try ProRealAI

Dax adaptable strategy Breackout/Mean reversion


ProOrder: Automated Strategies & Backtesting

New Reply
Author
Summary

This topic contains 82 replies,
has 13 voices, and was last updated by xburrexxburrex
5 years, 9 months ago.

Topic Details
Forum: ProOrder: Automated Strategies & Backtesting
Language: English
Started: 04/22/2017
Status: Active
Attachments: 26 files
ProRealCode ProRealCode
Loading...