






Four EMA trading strategy for DAX (LONG ONLY)
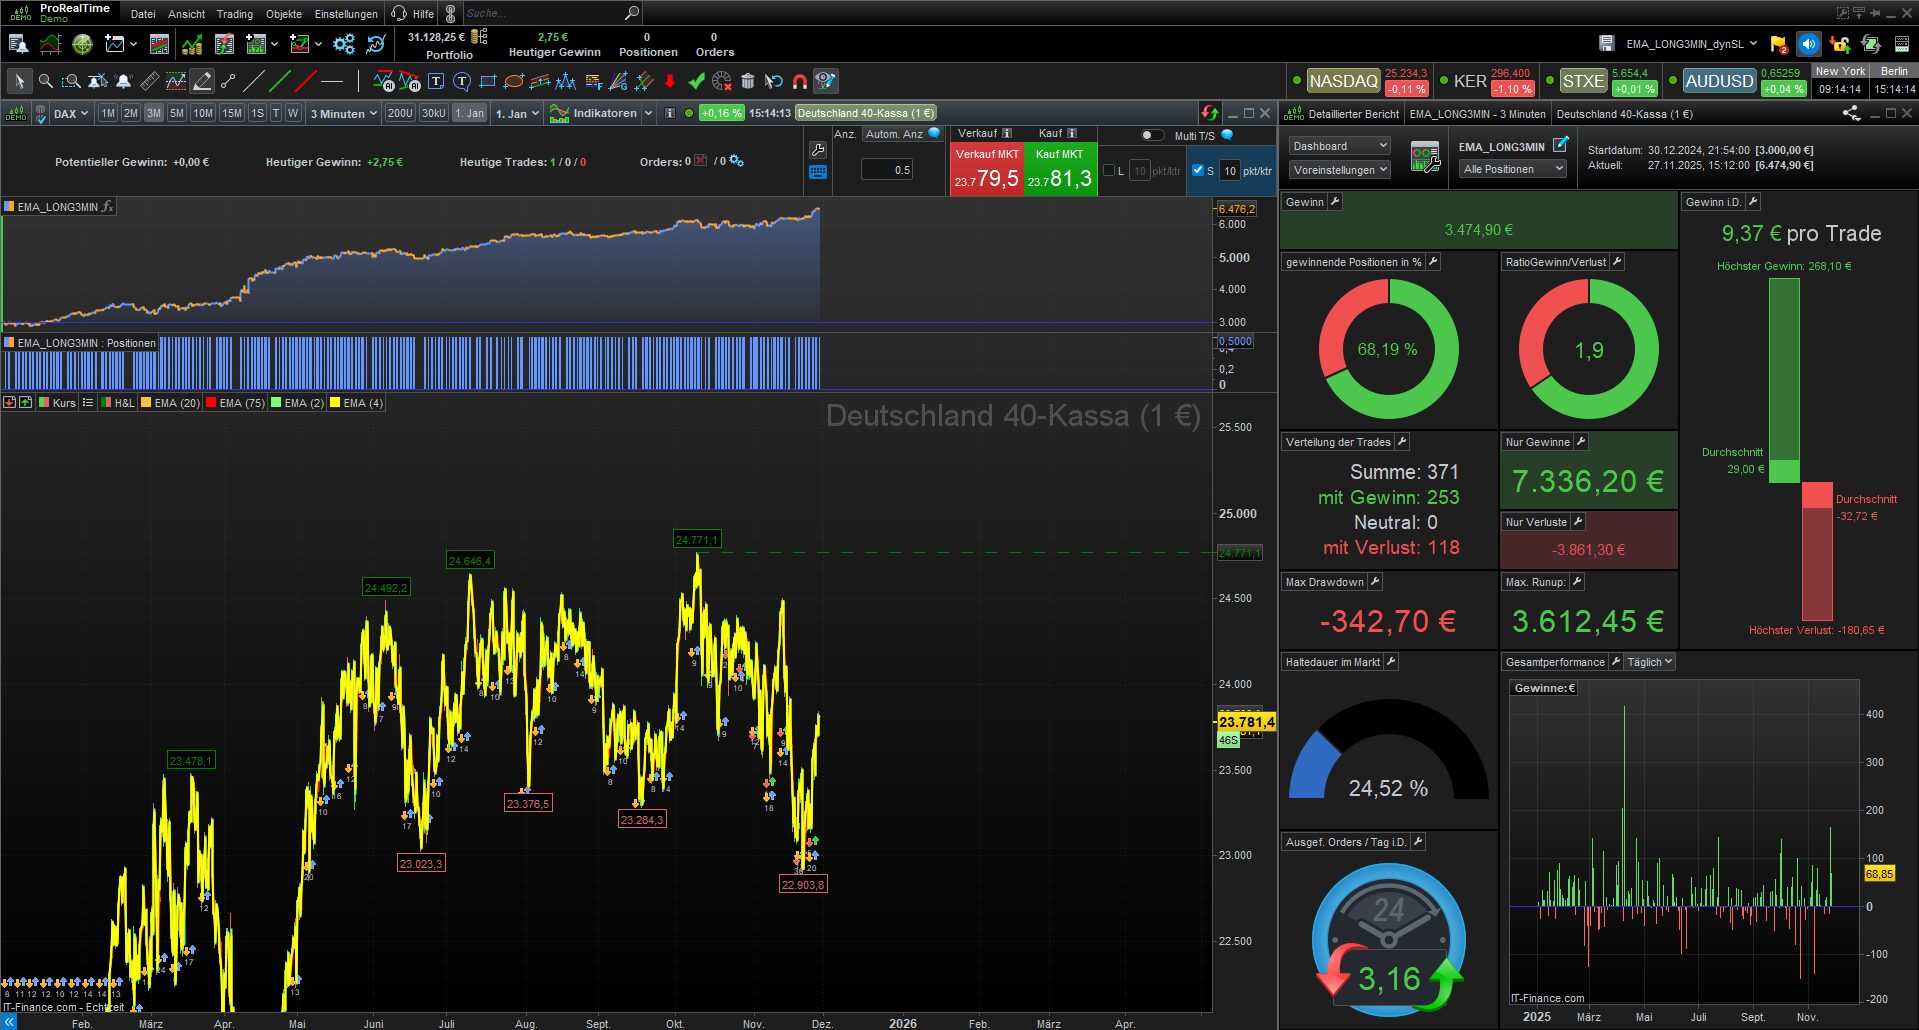
Dear community, Attached is my code for the DAX on a 3-minute basis, long only. It is kept very simple. The conditions are that the EMA 2 crosses above the EMA 4 while the EMA 20 is above the EMA 75. A very tight stop-loss of 0.15 is to be set once the profit reaches 0.25%. At 0.5% the position is closed. The backtest results show clear profits.
//-------------------------------------------------------------------------
// EMA_DAX (LONG ONLY)
// ATR-Filter + fixer TP + später aktivierter Schutz-SL + Hard Stop
//-------------------------------------------------------------------------

DEFPARAM CumulateOrders = false
DEFPARAM PreLoadBars = 1000

once ordersize = 0.5

// ----------------------------------------------------
// Handelszeit
// ----------------------------------------------------
tt = time >= 130000 AND time <= 220000

// ----------------------------------------------------
// Volatilitätsfilter
// ----------------------------------------------------
atrPeriod = 14
atr = AverageTrueRange[atrPeriod]
MinATRLong = 8
VolOKLong = atr > MinATRLong

// ----------------------------------------------------
// EMAs
// ----------------------------------------------------
ema2 = ExponentialAverage[2](close)
ema4 = ExponentialAverage[4](close)
ema20 = ExponentialAverage[20](close)
ema75 = ExponentialAverage[75](close)

// ----------------------------------------------------
// Long-Setup
// ----------------------------------------------------
cLongEntry = ema2 CROSSES OVER ema4
TrendLong = ema20 > ema75 AND close > ema75

// ----------------------------------------------------
// Entry
// ----------------------------------------------------
IF tt THEN
IF cLongEntry AND TrendLong AND VolOKLong AND NOT longonmarket THEN
BUY ordersize CONTRACTS AT MARKET
ENDIF
ENDIF

// ----------------------------------------------------
// Positionsmanagement
// ----------------------------------------------------
IF longonmarket THEN

entry = tradeprice(1)

// Reset bei neuer Position
IF longonmarket AND NOT longonmarket[1] THEN
maxProfit = 0
slActivated = 0 // <-- wichtig!
ENDIF

// Gewinn in %
currentProfit = (close - entry) / entry * 100
maxProfit = MAX(maxProfit, currentProfit)

// ------------------------------------------------
// TAKE PROFIT bei +0,50 %
// ------------------------------------------------
IF maxProfit >= 0.5 THEN
SELL AT MARKET
ENDIF

// ------------------------------------------------
// Aktivierung des Schutz-SL ab +0,25 %
// ------------------------------------------------
IF slActivated = 0 AND maxProfit >= 0.25 THEN
slActivated = 1
slPrice = entry * 1.0015
ENDIF

// Schutz-SL aktiv?
IF slActivated = 1 THEN
SELL AT slPrice STOP
ENDIF

// ------------------------------------------------
// Hard Stop - fester Eurobetrag
// ------------------------------------------------
euroRisk = 175
valuePerPoint = 0.5
stopPoints = euroRisk / valuePerPoint
hardStop = entry - stopPoints

IF low <= hardStop THEN
SELL AT MARKET
ENDIF

ENDIF

// ----------------------------------------------------
// Tagesende Exit
// ----------------------------------------------------
IF time >= 215500 AND longonmarket THEN
SELL AT MARKET
ENDIF
Comments
You must be logged in to post a comment.

Thanks a lot for sharing this code. The way you combine an EMA trend filter with an ATR filter and then manage the trade with a small fixed TP, a late protective stop and a hard stop defined in euros is very instructive. It’s a simple but well-structured concept, and that’s rare enough. The performance is excellent on the time window you posted, but outside that range the edge basically disappears. With slightly different EMA settings (EMA7, EMA13, EMA22, EMA77) the performance is positive from 2020 onwards, but it remains more of a research framework than a plug-and-play system for me. So I really wanted to say thank you for sharing it here.
Thanks for sharing, I think that currentProfit must be "currentProfit = (close - entry) / (entry / 100) " for the right calculation