



More from ProRealCode
ProRealCode - Trading & Coding with ProRealTime™
The ProRealTime™ community on the web! Officially sharing ProRealTime knowledge to Worldwide users since 2015!



John Ehlers Smoothed RSI
August 28, 2018, 9:10 AM
Indicators
0 Comments
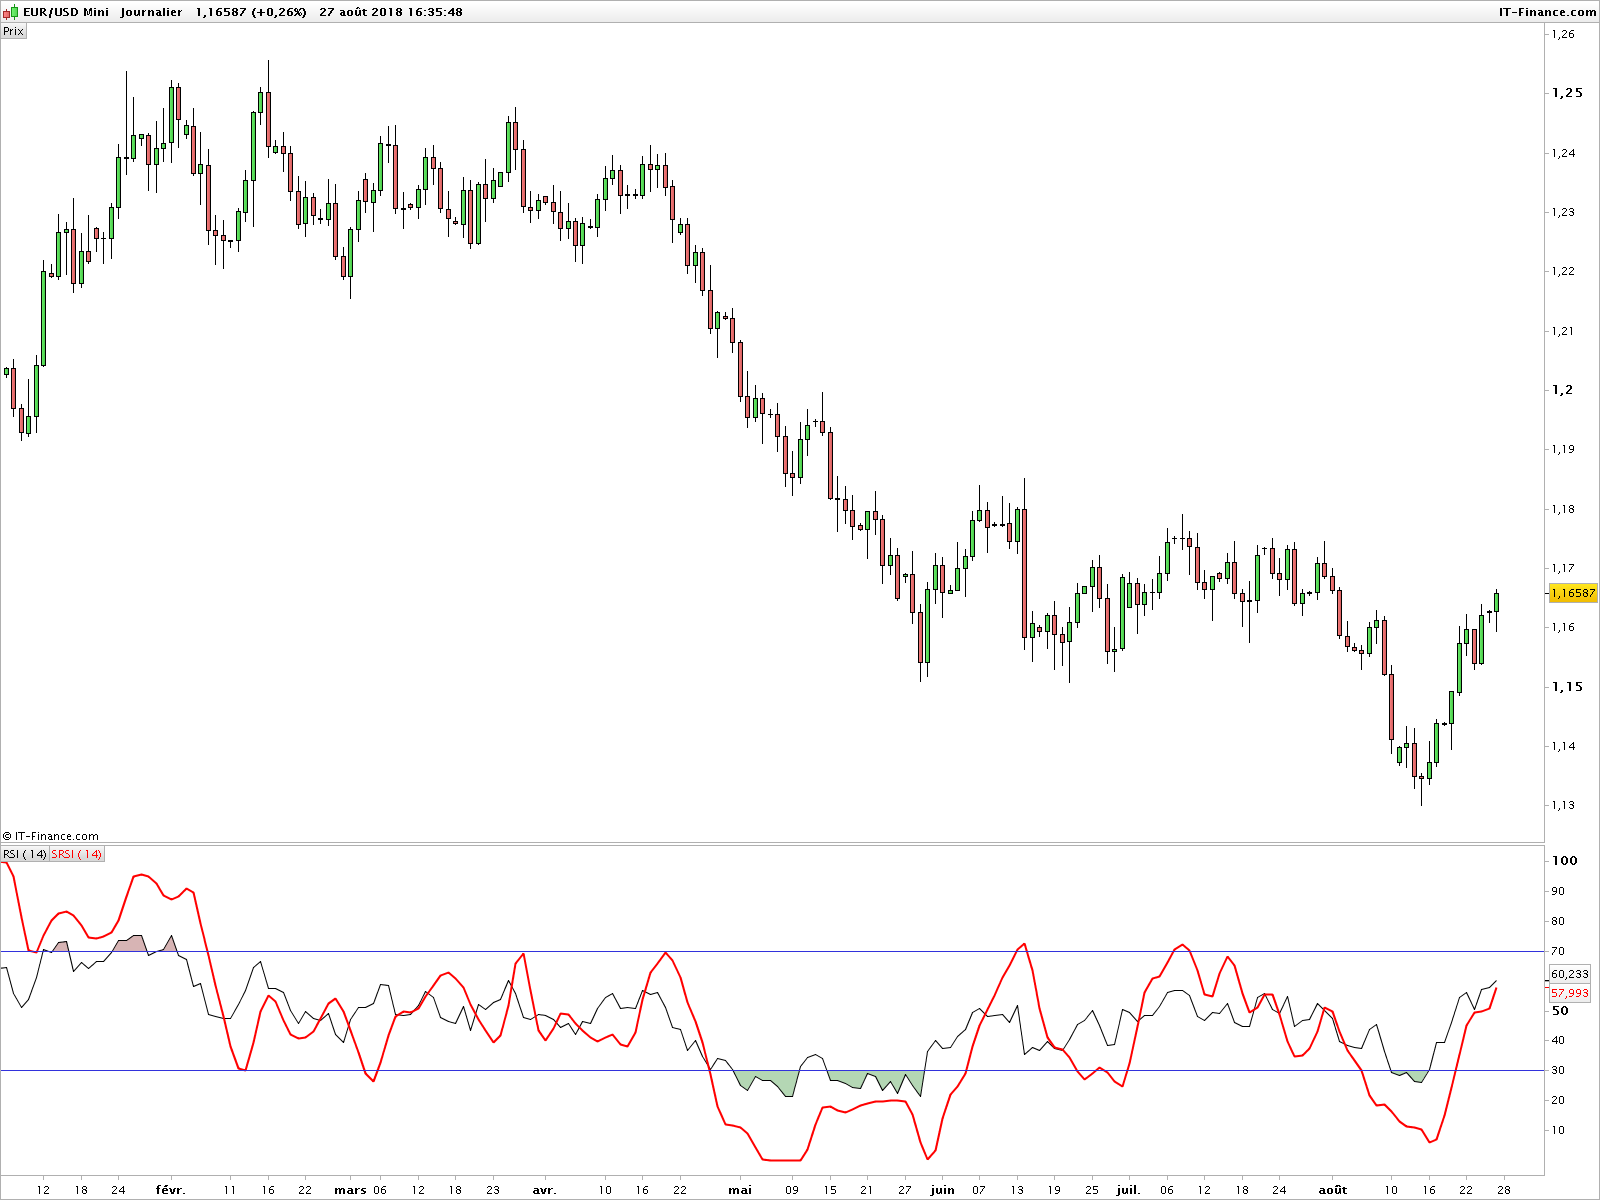
This is an implementation of John Ehlers’ Smoothed RSI, as described in RSI Smoothing.
// Smoothed Relative Strength Index (SRSI)
// RSI Smoothing
// John F. Ehlers
// http://www.stockspotter.com/Files/rsismoothing.pdf

// Parameter
Len = 14

Smooth23 = (Close + 2*Close[1] + 2*Close[2] + Close[3])/6
CU23 = 0
CD23 = 0
For count = 0 to Len - 1 do
	If Smooth23[count] > Smooth23[count + 1] then
		CU23 = CU23 + Smooth23[count] - Smooth23[count + 1]
	Endif
	If Smooth23[count] < Smooth23[count + 1] then
		CD23 = CD23 + Smooth23[count + 1] - Smooth23[count]
	Endif
Next

If CU23 + CD23 <> 0 then
	SRSI = CU23/(CU23 + CD23)
Endif

return SRSI*100 as "SRSI"
The attached screenshot shows J. Welles Wilder’s RSI (black) and John Ehlers’ Smoothed RSI (red) with a period of 14.
Download
Filename:
John-Ehlers-Smoothed-RSI.itf
Downloads:
159
Senior
This author is like an anonymous function, present but not directly identifiable. More details on this code architect as soon as they exit 'incognito' mode.
Author’s Profile
Similar code
John Ehlers SinewaveIndicators
John Ehlers Optimal Tracking FilterIndicators
John Ehlers Instantaneous TrendlineIndicators
John Ehlers – Correlation CycleIndicators
My Stochastic Oscillator – John EhlersIndicators
Loading...