Sharpe ratio >3 ? Seriously ?

Viewing 9 posts - 1 through 9 (of 9 total)
  • Author
    Posts
  • #134659 quote
    zilliqzilliq
    Participant
    Master

    Hi Guys,

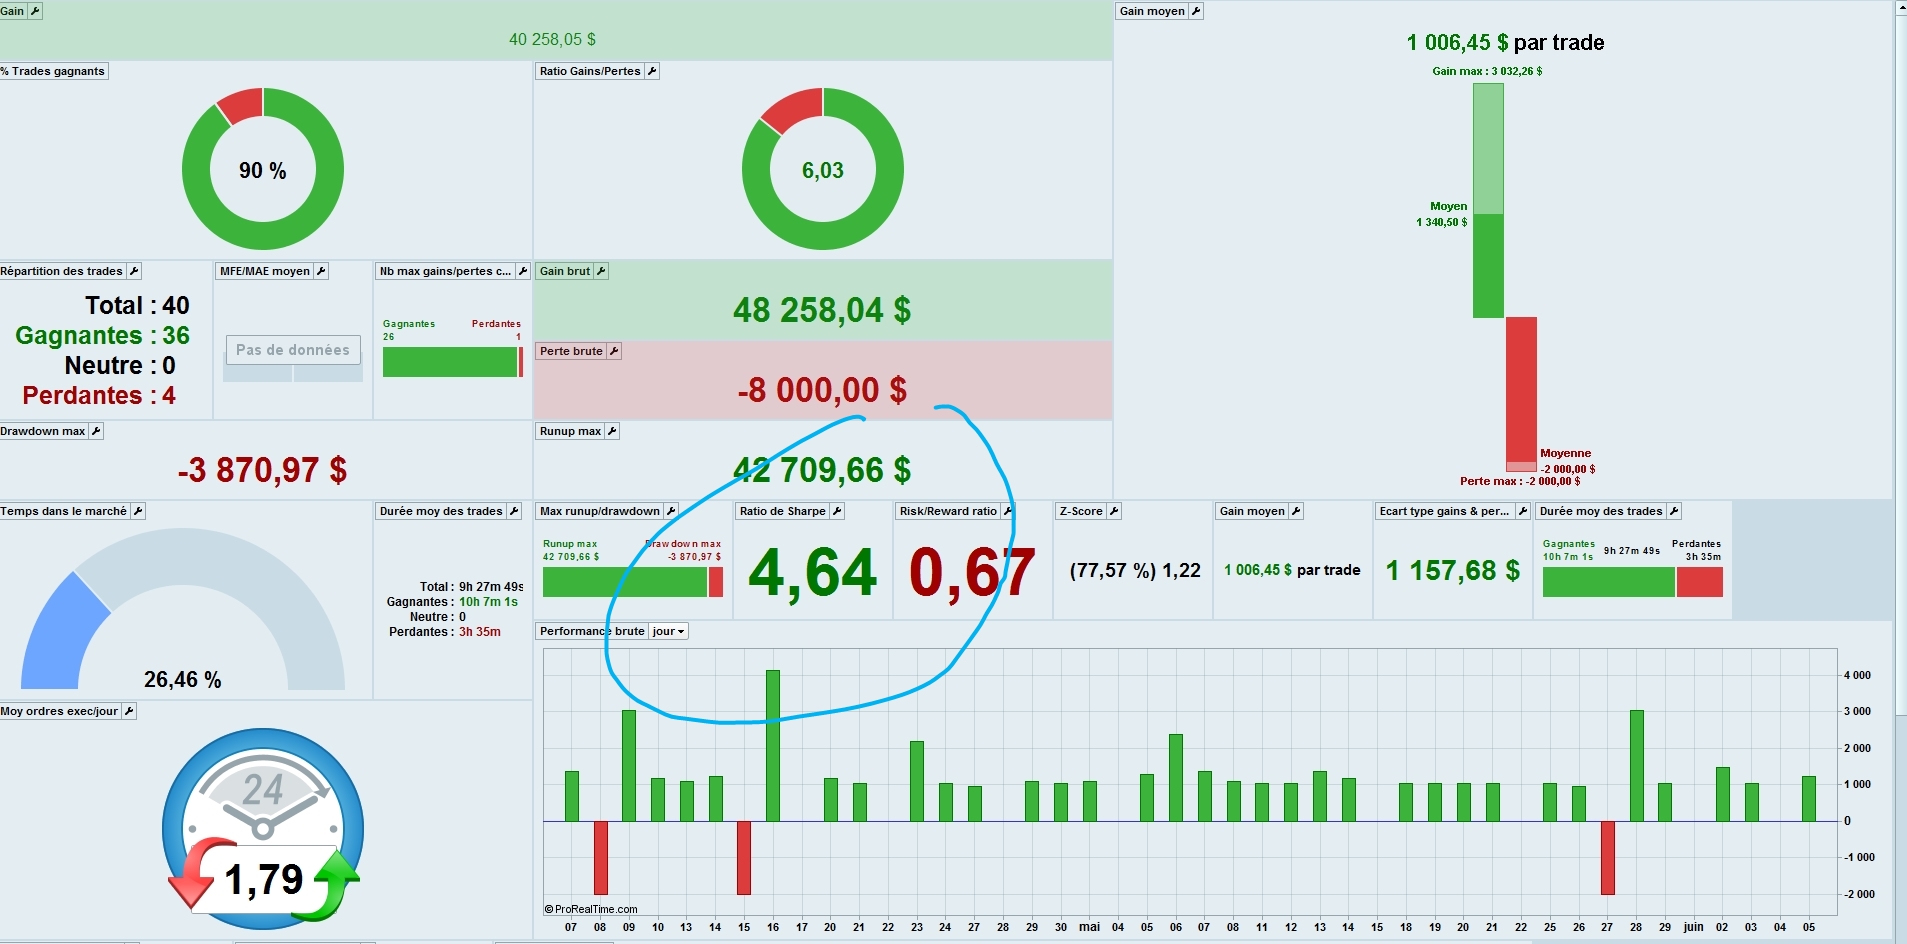
    I play with the new backtest results, but it’s strange, because on Backtest we can have Sharpe Ratio of more than 2 (Here 4.64 ! on 100 000 unit EUR/USD 1 mn, only on 40 trades and so on..)

    Remember that the best trading algo have a Sharpe ratio of 3, so I think a Sharpe ratio of more than 4 is impossible (I’m not stupid and I know we haven’t fin the graal, or the @Grahal 🙂 )

    What’s your Point of view ?

    Cheers

    2020-06-05_10h36_57.jpg 2020-06-05_10h36_57.jpg
    #134662 quote
    NicolasNicolas
    Keymaster
    Legend

    Low quantity of orders means not much data to average a significant ratio. With a high profitability strategy divided by a low standard deviation of gain, you obviously get a high Sharpe Ratio.

    #134674 quote
    zilliqzilliq
    Participant
    Master

    Sharpe ratio is on mean gain Nicolas, not total gain

    “…The Sharpe ratio reveals the average investment return, minus the risk-free rate of return, divided by the standard deviation of returns for the investment…”

    But agree with you on a small trades who makes interpretation difficult (That’s why there is a correction factor on SQN/Van Tharp notably ;,-) )

    Cheers

    #134720 quote
    zilliqzilliq
    Participant
    Master

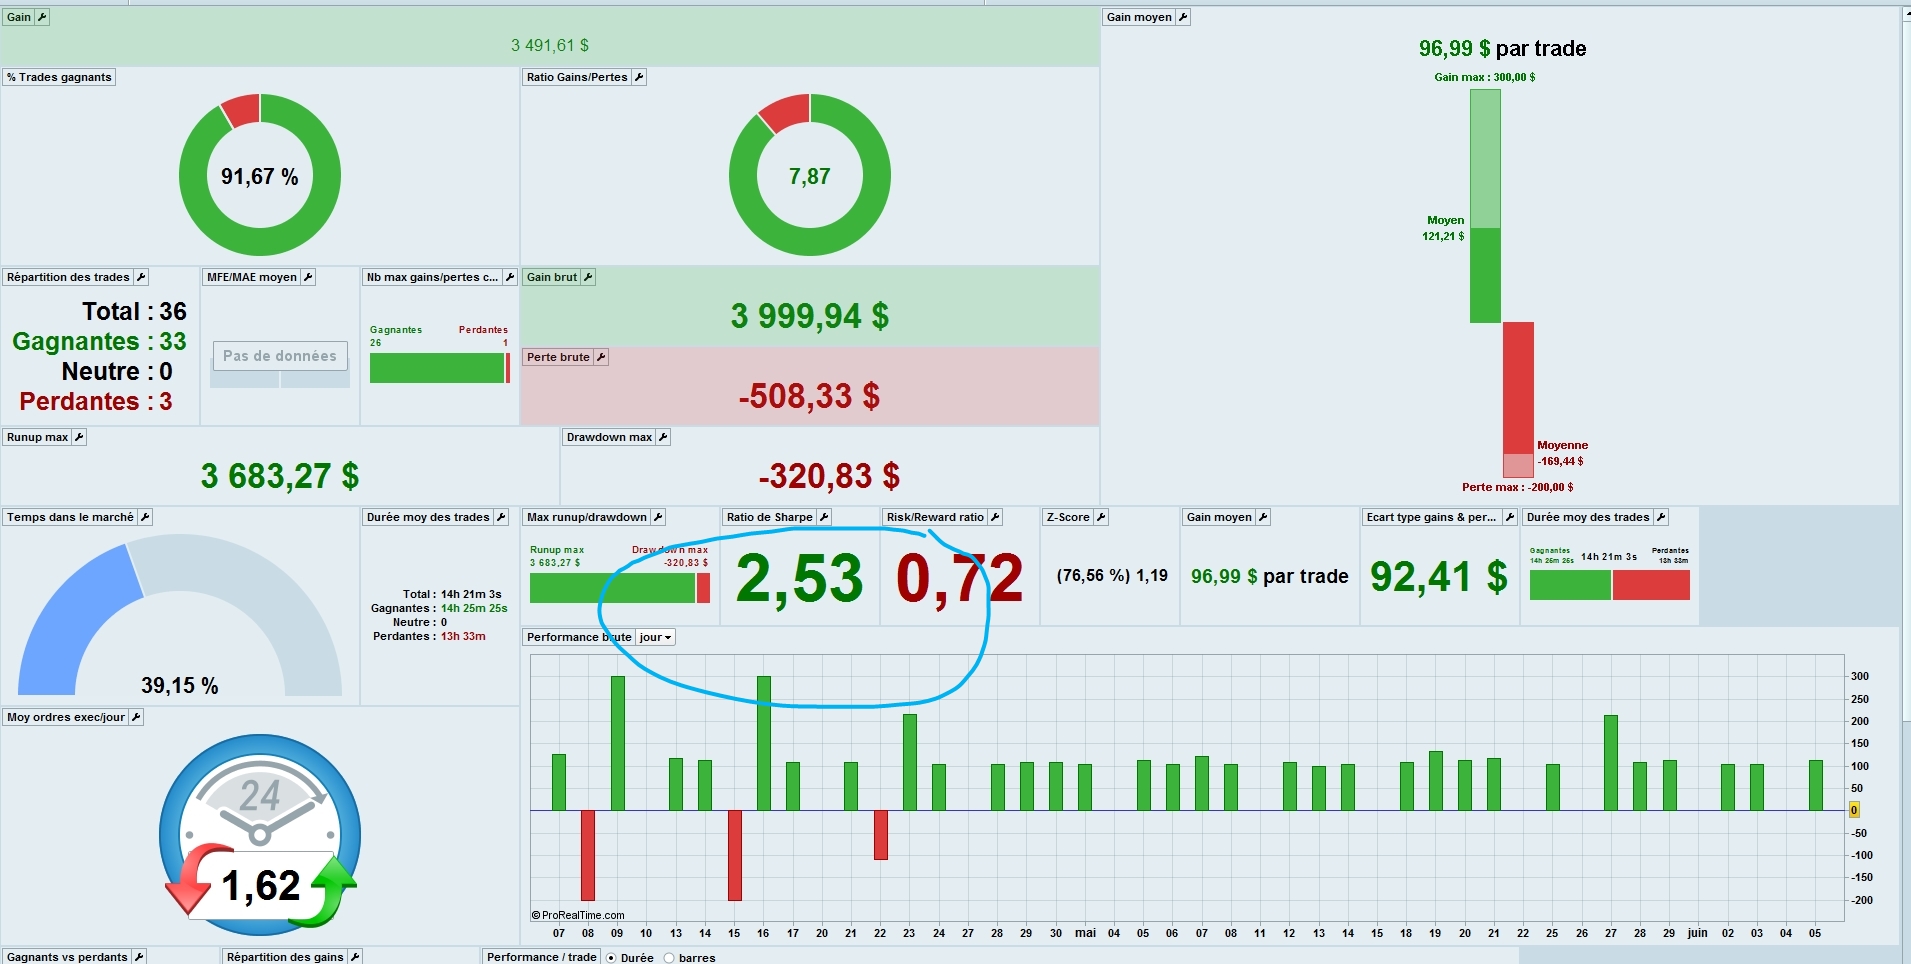
    As you can see, with quite the same number of trade, we can have very good sharpe ratio even with a small gain (+34 % only)

    Have a nice day

    2020-06-05_14h27_28.jpg 2020-06-05_14h27_28.jpg
    #134742 quote
    NicolasNicolas
    Keymaster
    Legend

    Orders are grouped as a daily return:

    dailyReturn[day] = sum(perf)[day] / nb_trades[day]

    Then the Sharpe ratio is calculated:

    sharpe = (average(dailyReturns) – risk free interest rate between start and end of the report) / standard-deviation(dailyReturn)

    The risk free interest rate is automatically calculated by the software with a geometric interpolation.

    zilliq thanked this post
    #134747 quote
    zilliqzilliq
    Participant
    Master

    We are together agree, that’s derived/based on mean gain, that’s why even with a small total gain we can have a beautiful Sharpe ratio (Interest is may be for the “ego” 🙂

    Have a nice day Nicolas

    #135534 quote
    zilliqzilliq
    Participant
    Master

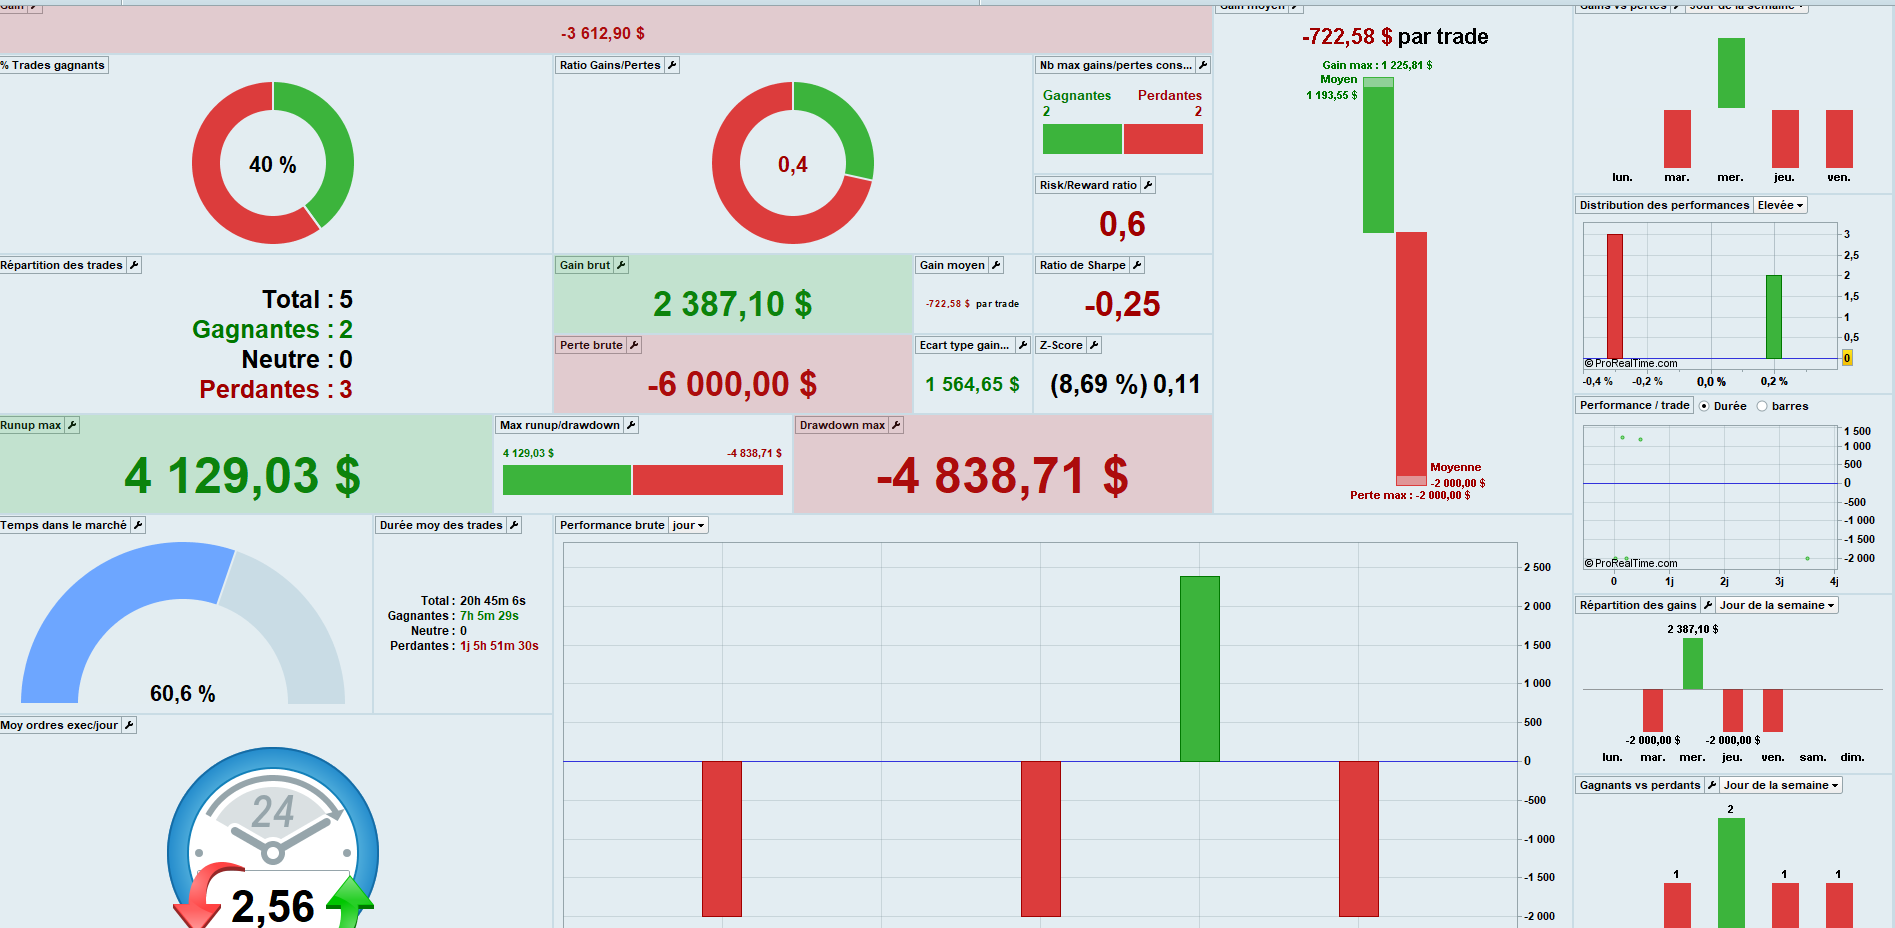
    FYI (very bad) results after some days even with a sharpe ratio of 4.64 ! (And remember 90 % winning trades, 6 win/loss and so on…EUR/USD 1 mn 100 000 units)

    Sharpe ratio don’t do all the job 😉

    2020-06-11_08h51_26.png 2020-06-11_08h51_26.png
    #135555 quote
    NicolasNicolas
    Keymaster
    Legend

    Nothing new if the sharpe ratio is calculated on bias and over-fitted results 🙂

    #135571 quote
    zilliqzilliq
    Participant
    Master

    It wasn’t overfit Nicolas (Only 2-3 parameters as usual), 100 000 units and so on

    It’s jut that Sharpe Ratio isn’t a standalone and need to be interpret with other indicators as we previous seen

    Have a nice day

Viewing 9 posts - 1 through 9 (of 9 total)
  • You must be logged in to reply to this topic.
ProRealAI ProRealAI New

Stuck on this ProBuilder code?

Describe what this topic is trying to build, in plain English, and ProRealAI writes the ProRealTime™ indicator, screener or system for you.

Available in 7 languages
Try ProRealAI

Sharpe ratio >3 ? Seriously ?


ProOrder: Automated Strategies & Backtesting

New Reply
Author
author-avatar
zilliq @zilliq Participant
Summary

This topic contains 8 replies,
has 2 voices, and was last updated by zilliqzilliq
6 years, 3 months ago.

Topic Details
Forum: ProOrder: Automated Strategies & Backtesting
Language: English
Started: 06/05/2020
Status: Active
Attachments: 3 files
ProRealCode ProRealCode
Loading...