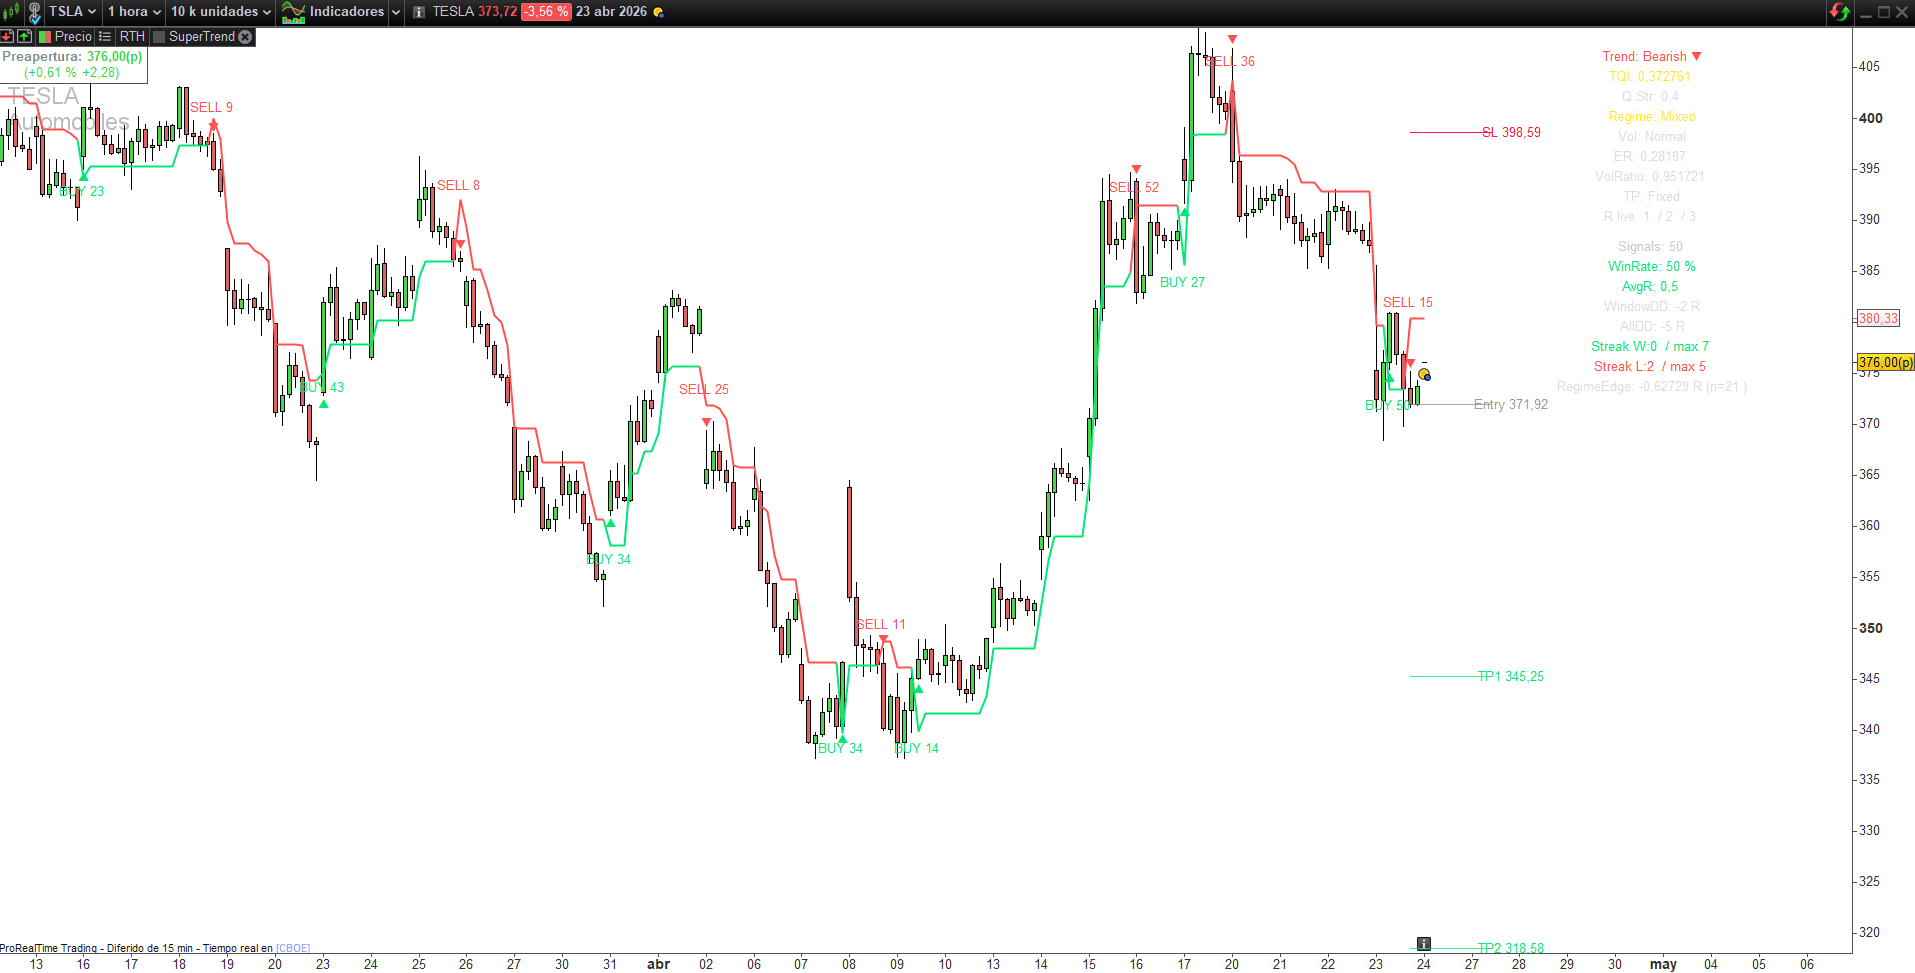
Hi, here you have the translation:
//---------------------------------------------------------
//PRC_Self-Aware Trend System [WillyAlgoTrader]
//version = 0
//21.04.2026
//Iván González @ www.prorealcode.com
//Sharing ProRealTime knowledge
//---------------------------------------------------------
//==========================================================
// 1. INPUTS
//==========================================================
// --- Main ---
atrLen          = 14        // ATR length
baseMult        = 2.0       // base band width (xATR)
// --- Adaptive Engine (legacy ER) ---
useAdaptive     = 1         // 1=on
erLen           = 20        // efficiency window
adaptStrength   = 0.5
atrBaselineLen  = 100
// --- Trend Quality Engine ---
useTqi          = 1
qualityStrength = 0.4
qualityCurve    = 1.5
multSmooth      = 1         // EMA-smooth multipliers
useAsymBands    = 1
asymStrength    = 0.5
useEffAtr       = 1         // efficiency-weighted ATR
useCharFlip     = 1
charFlipMinAge  = 5
charFlipHighTqi = 0.55
charFlipLowTqi  = 0.25
wEr             = 0.35
wVol            = 0.20
wStruct         = 0.25
wMom            = 0.20
structLen       = 20
momLen          = 10
// --- Risk ---
slAtrMult       = 1.5
useDynTp        = 0         // 0=Fixed, 1=Dynamic
tp1R            = 1.0
tp2R            = 2.0
tp3R            = 3.0
// --- Dynamic TP ---
dynTpTqiW       = 0.6
dynTpVolW       = 0.4
dynTpMinScale   = 0.5
dynTpMaxScale   = 2.0
dynTpFloorR1    = 0.5
dynTpCeilR3     = 8.0
labelOffsetBars = 10
tradeMaxAge     = 100
// --- Self-learning ---
useAutoCalib    = 0
calibWindow     = 20
calibBadR       = 0.0
calibGoodR      = 0.7
calibStepQ      = 0.05
calibCooldown   = 5
calibMinQ       = 0.1
calibMaxQ       = 0.9
// --- Score (display) ---
rsiLen          = 14
rsiOB           = 70
rsiOS           = 30
rsiLookback     = 20
pivotLen        = 3
volLen          = 20
useVolScore     = 1
useRsiScore     = 1
useStructScore  = 1
showDash        = 1
showBands       = 1
showSignals     = 1

//==========================================================
// 2. CONSTANTS
//==========================================================
maxHistory     = 50        // rolling signal buffer size (reduced from 100 for PRT cost)
erLow          = 0.25
erHigh         = 0.50
volLow         = 0.7
volHigh        = 1.3
ewmaAlpha      = 0.2
multSmoothAlpha = 0.15

//==========================================================
// 3. WARMUP
//==========================================================
warmup = max(50, max(atrLen, max(erLen, max(rsiLen, max(volLen, max(structLen, momLen))))) + 10)
isWarm = barindex >= warmup

//==========================================================
// 4. BASE CALCULATIONS: ATR, ER, efficiency-weighted ATR
//==========================================================
rawAtr      = averagetruerange[atrLen](close)
atrBase     = average[atrBaselineLen](rawAtr)
if atrBase <= 0 then
   volRatio = 1.0
else
   volRatio = rawAtr / atrBase
endif

// Efficiency Ratio manual (Kaufman)
erChange    = abs(close - close[erLen])
erVolSum    = summation[erLen](abs(close - close[1]))
if erVolSum > 0 then
   erValue = erChange / erVolSum
else
   erValue = 0
endif

if useEffAtr = 1 then
   atrValue = rawAtr * (0.5 + 0.5 * erValue)
else
   atrValue = rawAtr
endif

//==========================================================
// 5. TREND QUALITY INDEX (TQI, 4 factors)
//==========================================================
// Factor 1: ER clamped
tqiEr = min(1.0, max(0.0, erValue))

// Factor 2: Volatility regime
// Z-score del volumen si hay; si no, mapeo sobre volRatio
hasVol = volume > 0
if hasVol then
   vMean = average[volLen](volume)
   vStd  = std[volLen](volume)
   if vStd > 0 then
      volZ = (volume - vMean) / vStd
   else
      volZ = 0
   endif
   // map [-1..2] to [0..1]
   tqiVolRaw = (volZ - (-1.0)) / 3.0
else
   volZ = 0
   // map volRatio [0.6..1.8] to [0..1]
   tqiVolRaw = (volRatio - 0.6) / 1.2
endif
tqiVol = min(1.0, max(0.0, tqiVolRaw))

// Factor 3: Structure (precio en el rango N-barras, desviación de 0.5)
sHi = highest[structLen](high)
sLo = lowest[structLen](low)
sRange = sHi - sLo
if sRange > 0 then
   pricePos = (close - sLo) / sRange
else
   pricePos = 0.5
endif
tqiStruct = min(1.0, max(0.0, abs(pricePos - 0.5) * 2.0))

// Factor 4: Momentum persistence — fracción de barras alineadas con el cambio N
aligned = 0
if barindex > momLen then
   winChg = close - close[momLen]
   for k = 0 to momLen - 1 do
      barChg = close[k] - close[k+1]
      if winChg > 0 and barChg > 0 then
         aligned = aligned + 1
      endif
      if winChg < 0 and barChg < 0 then
         aligned = aligned + 1
      endif
   next
endif
tqiMom = aligned / momLen

// Suma ponderada
wSum = wEr + wVol + wStruct + wMom
if wSum <= 0 then
   wSum = 1.0
endif
if useTqi = 1 then
   tqi = (tqiEr*wEr + tqiVol*wVol + tqiStruct*wStruct + tqiMom*wMom) / wSum
else
   tqi = 0.5
endif
tqi = min(1.0, max(0.0, tqi))

//==========================================================
// 6. ADAPTIVE MULTIPLIERS (active / passive)
//==========================================================
if useAdaptive = 1 then
   legacyAdapt = 1.0 + adaptStrength * (0.5 - erValue)
else
   legacyAdapt = 1.0
endif

// qualityStrength puede ser modificado por auto-calibración
once effQStrength = qualityStrength

if useTqi = 1 then
   qDev = 1.0 - tqi
   if qDev > 0 then
      qDevP = pow(qDev, qualityCurve)
   else
      qDevP = 0
   endif
else
   qDevP = 0.5
endif
tqiMult = 1.0 - effQStrength + effQStrength * (0.6 + 0.8 * qDevP)

symMult = baseMult * legacyAdapt * tqiMult

if useTqi = 1 and useAsymBands = 1 then
   asymTighten = 1.0 - asymStrength * tqi * 0.3
   asymWiden   = 1.0 + asymStrength * tqi * 0.4
   activeMultRaw  = symMult * asymTighten
   passiveMultRaw = symMult * asymWiden
else
   activeMultRaw  = symMult
   passiveMultRaw = symMult
endif

// EMA-smoothing de los multiplicadores
once activeMultSm  = activeMultRaw
once passiveMultSm = passiveMultRaw
if multSmooth = 1 then
   activeMultSm  = activeMultSm  * (1.0 - multSmoothAlpha) + activeMultRaw  * multSmoothAlpha
   passiveMultSm = passiveMultSm * (1.0 - multSmoothAlpha) + passiveMultRaw * multSmoothAlpha
else
   activeMultSm  = activeMultRaw
   passiveMultSm = passiveMultRaw
endif

//==========================================================
// 7. ADAPTIVE SUPERTREND (máquina de estado canónica PRT)
//==========================================================
// Patrón canónico (learning 003): una sola stLine que hace trailing + flip atómico.
// Se preserva el carácter asimétrico: lado activo (tighter) para el trail, lado pasivo (wider) al flipear.
once trendDir      = 1
once stLine        = close
once trendStartBar = 0

// prevTrend robusto en primeras barras
if barindex < 2 then
   prevTrend = 1
else
   prevTrend = trendDir[1]
endif

// Warmup guard: no operar máquina de estado hasta tener ATR válido.
// Durante el warmup stLine queda en su semilla (close de barindex=0) y trendDir = 1.
if barindex >= atrLen then
   // Bandas raw según la dirección previa
   if prevTrend = 1 then
      activeBandRaw = close - activeMultSm * atrValue   // lowerBand "tight"
      flipBandRaw   = close + passiveMultSm * atrValue  // upperBand "wide" tras flip
   else
      activeBandRaw = close + activeMultSm * atrValue   // upperBand "tight"
      flipBandRaw   = close - passiveMultSm * atrValue  // lowerBand "wide" tras flip
   endif

   // Primera barra post-warmup: re-inicializar stLine según dirección
   if barindex = atrLen then
      stLine   = activeBandRaw
      trendDir = 1
   else
      // Máquina de estado: trail + flip
      if prevTrend = 1 then
         // Alcista: stLine = lowerBand, sube (nunca baja)
         if activeBandRaw > stLine then
            stLine = activeBandRaw
         endif
         if close < stLine then
            trendDir = -1
            stLine   = flipBandRaw
         else
            trendDir = 1
         endif
      else
         // Bajista: stLine = upperBand, baja (nunca sube)
         if activeBandRaw < stLine then
            stLine = activeBandRaw
         endif
         if close > stLine then
            trendDir = 1
            stLine   = flipBandRaw
         else
            trendDir = -1
         endif
      endif
   endif
endif

// Character-flip (colapso de TQI fuerza inversión sobre la dirección PREVIA)
// Solo aplica si no hubo ya un price-flip en esta barra.
if barindex < 2 then
   prevTqi = 0.5
else
   prevTqi = tqi[1]
endif
trendAge = barindex - trendStartBar
priceFlipped = trendDir <> prevTrend

charBase = (useCharFlip = 1) and (useTqi = 1) and (prevTqi > charFlipHighTqi) and (tqi < charFlipLowTqi) and (trendAge >= charFlipMinAge)
if charBase and not priceFlipped then
   if prevTrend = 1 then
      trendDir = -1
      stLine   = close + passiveMultSm * atrValue
   else
      trendDir = 1
      stLine   = close - passiveMultSm * atrValue
   endif
endif

// Trend-start tracking
if trendDir <> prevTrend then
   trendStartBar = barindex
endif

flipUp = (trendDir =  1) and (prevTrend = -1)
flipDn = (trendDir = -1) and (prevTrend =  1)

//==========================================================
// 7.5 RSI + PIVOTS (para score de señales)
//==========================================================
rsiVal = rsi[rsiLen](close)

// Pivots high/low simétricos (ventana 2*pivotLen+1)
once lastPivotHigh = 0
once lastPivotLow  = 0
if barindex >= 2*pivotLen then
   if high[pivotLen] = highest[2*pivotLen+1](high) then
      lastPivotHigh = high[pivotLen]
   endif
   if low[pivotLen]  = lowest[2*pivotLen+1](low) then
      lastPivotLow  = low[pivotLen]
   endif
endif

//==========================================================
// 7.6 SIGNAL SCORE (6 componentes)
//==========================================================
bypassScore = 12.0

// Componente 1: momentum (mov en dirección contraria 3 barras previas)
dirMoveBuy  = close[3] - close
dirMoveSell = close - close[3]
if atrValue > 0 then
   momRatioBuy  = dirMoveBuy  / atrValue
   momRatioSell = dirMoveSell / atrValue
else
   momRatioBuy  = 0
   momRatioSell = 0
endif
// mapClamp(x, 0.3, 2.0, 0, 17) → t = (x-0.3)/1.7 clamp, * 17
tMomBuy      = min(1.0, max(0.0, (momRatioBuy  - 0.3) / 1.7))
tMomSell     = min(1.0, max(0.0, (momRatioSell - 0.3) / 1.7))
momScoreBuy  = tMomBuy  * 17.0
momScoreSell = tMomSell * 17.0

// Componente 2: efficiency ratio mapClamp(er, 0.15, 0.7, 0, 17)
tEr     = min(1.0, max(0.0, (erValue - 0.15) / 0.55))
erScore = tEr * 17.0

// Componente 3: volumen Z mapClamp(volZ, 0, 3, 0, 17) o bypass
if hasVol and (useVolScore = 1) then
   tVol   = min(1.0, max(0.0, volZ / 3.0))
   vScore = tVol * 17.0
else
   vScore = bypassScore
endif

// Componente 4: RSI depth
if useRsiScore = 1 then
   rsiWinLow  = lowest[rsiLookback](rsiVal)
   rsiWinHigh = highest[rsiLookback](rsiVal)
   rsiDepthBuy  = max(0.0, rsiOS - rsiWinLow)
   rsiDepthSell = max(0.0, rsiWinHigh - rsiOB)
   tRsiBuy      = min(1.0, max(0.0, rsiDepthBuy  / 15.0))
   tRsiSell     = min(1.0, max(0.0, rsiDepthSell / 15.0))
   rsiScoreBuy  = tRsiBuy  * 17.0
   rsiScoreSell = tRsiSell * 17.0
else
   rsiScoreBuy  = bypassScore
   rsiScoreSell = bypassScore
endif

// Componente 5: structure (distancia al último pivot)
if useStructScore = 1 then
   if lastPivotLow > 0 then
      pivDistBuy = abs(close - lastPivotLow)
   else
      pivDistBuy = 0
   endif
   if lastPivotHigh > 0 then
      pivDistSell = abs(lastPivotHigh - close)
   else
      pivDistSell = 0
   endif
   if atrValue > 0 then
      pivRatioBuy  = pivDistBuy  / atrValue
      pivRatioSell = pivDistSell / atrValue
   else
      pivRatioBuy  = 0
      pivRatioSell = 0
   endif
   // mapClampInv(x, 0, 1.5, 16, 6): desciende con x
   tStructBuy      = min(1.0, max(0.0, pivRatioBuy  / 1.5))
   tStructSell     = min(1.0, max(0.0, pivRatioSell / 1.5))
   structScoreBuy  = 16.0 - tStructBuy  * 10.0
   structScoreSell = 16.0 - tStructSell * 10.0
else
   structScoreBuy  = bypassScore
   structScoreSell = bypassScore
endif

// Componente 6: break depth (profundidad de rotura del SuperTrend previo)
breakDepthBuy  = max(0.0, stLine[1] - close[1])
breakDepthSell = max(0.0, close[1] - stLine[1])
if atrValue > 0 then
   breakRatioBuy  = breakDepthBuy  / atrValue
   breakRatioSell = breakDepthSell / atrValue
else
   breakRatioBuy  = 0
   breakRatioSell = 0
endif
tBrkBuy       = min(1.0, max(0.0, breakRatioBuy))
tBrkSell      = min(1.0, max(0.0, breakRatioSell))
breakScoreBuy  = tBrkBuy  * 16.0
breakScoreSell = tBrkSell * 16.0

// Suma (máx ~102)
buyScore  = momScoreBuy  + erScore + vScore + rsiScoreBuy  + structScoreBuy  + breakScoreBuy
sellScore = momScoreSell + erScore + vScore + rsiScoreSell + structScoreSell + breakScoreSell
buyScoreInt  = round(buyScore)
sellScoreInt = round(sellScore)

//==========================================================
// 8. DYNAMIC TP R-MULTIPLES (per-bar, for live signal use)
//==========================================================
// Scale por blend TQI + volRatio
tqiComp = min(1.0, max(0.0, tqi))
volComp01 = (volRatio - 0.5) / 1.5
volComp = min(1.0, max(0.0, volComp01))
wTpSum = dynTpTqiW + dynTpVolW
if wTpSum <= 0 then
   wTpSum = 1.0
endif
rawScale = (tqiComp * dynTpTqiW + volComp * dynTpVolW) / wTpSum
finalScale = dynTpMinScale + rawScale * (dynTpMaxScale - dynTpMinScale)

// TP base re-ordenados (garantizar tp1<tp2<tp3)
fixedTp1R = min(tp1R, min(tp2R, tp3R))
fixedTp3R = max(tp1R, max(tp2R, tp3R))
fixedTp2R = tp1R + tp2R + tp3R - fixedTp1R - fixedTp3R

if useDynTp = 1 then
   // Floors proporcionales
   tp1Floor = dynTpFloorR1
   if fixedTp1R > 0.01 then
      tp2Floor = dynTpFloorR1 * (fixedTp2R / fixedTp1R)
      tp3Floor = dynTpFloorR1 * (fixedTp3R / fixedTp1R)
   else
      tp2Floor = dynTpFloorR1
      tp3Floor = dynTpFloorR1
   endif
   effTp1R = min(dynTpCeilR3, max(tp1Floor, fixedTp1R * finalScale))
   effTp2R = min(dynTpCeilR3, max(tp2Floor, fixedTp2R * finalScale))
   effTp3R = min(dynTpCeilR3, max(tp3Floor, fixedTp3R * finalScale))
   // Re-sort tras scaling
   sTp1 = min(effTp1R, min(effTp2R, effTp3R))
   sTp3 = max(effTp1R, max(effTp2R, effTp3R))
   sTp2 = effTp1R + effTp2R + effTp3R - sTp1 - sTp3
   liveTp1R = sTp1
   liveTp2R = sTp2
   liveTp3R = sTp3
else
   liveTp1R = fixedTp1R
   liveTp2R = fixedTp2R
   liveTp3R = fixedTp3R
endif

//==========================================================
// 9. ACTIVE TRADE STATE (solo 1 señal viva a la vez)
//==========================================================
once tradeDir      = 0
once tradeClosed   = 1   // 1 = no hay trade vivo; se pone a 0 al abrir
once tradeEntryBar = 0
once tradeEntry    = 0
once tradeSl       = 0
once tradeTp1      = 0
once tradeTp2      = 0
once tradeTp3      = 0
once tradeTp1R     = 1.0
once tradeTp2R     = 2.0
once tradeTp3R     = 3.0
once hitTp1        = 0
once hitTp2        = 0
once hitTp3        = 0
once tradeCellIdx  = -1

confirmedBuy  = flipUp and isWarm
confirmedSell = flipDn and isWarm

if confirmedBuy then
   tEntry = close
   // SL basado en el último pivot low (réplica Pine): el más conservador entre pivot-SL y close-SL
   if lastPivotLow > 0 then
      slBase = lastPivotLow
   else
      slBase = low
   endif
   rawSl = slBase - slAtrMult * atrValue
   minSl = close  - slAtrMult * atrValue
   tSl   = min(rawSl, minSl)
   risk  = tEntry - tSl
   tradeDir      = 1
   tradeClosed   = 0
   tradeEntryBar = barindex
   tradeEntry    = tEntry
   tradeSl       = tSl
   tradeTp1      = tEntry + risk * liveTp1R
   tradeTp2      = tEntry + risk * liveTp2R
   tradeTp3      = tEntry + risk * liveTp3R
   tradeTp1R     = liveTp1R
   tradeTp2R     = liveTp2R
   tradeTp3R     = liveTp3R
   hitTp1        = 0
   hitTp2        = 0
   hitTp3        = 0
endif

if confirmedSell then
   tEntry = close
   // SL basado en el último pivot high (réplica Pine): el más conservador entre pivot-SL y close-SL
   if lastPivotHigh > 0 then
      slBase = lastPivotHigh
   else
      slBase = high
   endif
   rawSl = slBase + slAtrMult * atrValue
   minSl = close  + slAtrMult * atrValue
   tSl   = max(rawSl, minSl)
   risk  = tSl - tEntry
   tradeDir      = -1
   tradeClosed   = 0
   tradeEntryBar = barindex
   tradeEntry    = tEntry
   tradeSl       = tSl
   tradeTp1      = tEntry - risk * liveTp1R
   tradeTp2      = tEntry - risk * liveTp2R
   tradeTp3      = tEntry - risk * liveTp3R
   tradeTp1R     = liveTp1R
   tradeTp2R     = liveTp2R
   tradeTp3R     = liveTp3R
   hitTp1        = 0
   hitTp2        = 0
   hitTp3        = 0
endif

//==========================================================
// 10. HIT DETECTION + REALIZED R + LEARNING
//==========================================================
// Rolling buffer de últimas maxHistory señales cerradas (array $sigR)
once writeIdx = 0         // puntero rotante 0..maxHistory-1
once bufFilled = 0        // cuántos slots llenos (hasta maxHistory)
once winStreak = 0
once lossStreak = 0
once maxWinStreak = 0
once maxLossStreak = 0
once allCount = 0
once allRSum = 0
once allCumR = 0
once allPeak = 0
once allTrough = 0
once signalsSinceCalib = 0

// Regime grid (3×3): idx = erBin*3 + volBin
once gridC0 = 0
once gridC1 = 0
once gridC2 = 0
once gridC3 = 0
once gridC4 = 0
once gridC5 = 0
once gridC6 = 0
once gridC7 = 0
once gridC8 = 0
once gridE0 = 0
once gridE1 = 0
once gridE2 = 0
once gridE3 = 0
once gridE4 = 0
once gridE5 = 0
once gridE6 = 0
once gridE7 = 0
once gridE8 = 0

// Bin del regime actual (para clasificar la señal que se abre)
if erValue < erLow then
   curErBin = 0
elsif erValue < erHigh then
   curErBin = 1
else
   curErBin = 2
endif
if volRatio < volLow then
   curVolBin = 0
elsif volRatio < volHigh then
   curVolBin = 1
else
   curVolBin = 2
endif
curCell = curErBin * 3 + curVolBin

// Memorizar cell del trade cuando abre
if confirmedBuy or confirmedSell then
   tradeCellIdx = curCell
endif

if (tradeDir <> 0) and (tradeClosed = 0) and (barindex > tradeEntryBar) then
   if tradeDir = 1 then
      tp1Reached = high >= tradeTp1
      tp2Reached = high >= tradeTp2
      tp3Reached = high >= tradeTp3
      slHit      = low  <= tradeSl
   else
      tp1Reached = low <= tradeTp1
      tp2Reached = low <= tradeTp2
      tp3Reached = low <= tradeTp3
      slHit      = high >= tradeSl
   endif

   if tp1Reached and (hitTp1 = 0) then
      hitTp1 = 1
   endif
   if tp2Reached and (hitTp2 = 0) then
      hitTp2 = 1
   endif
   if tp3Reached and (hitTp3 = 0) then
      hitTp3 = 1
   endif

   tradeAge = barindex - tradeEntryBar
   timeoutHit = tradeAge >= tradeMaxAge

   if (hitTp3 = 1) or slHit or timeoutHit then
      // Calcular realized R (fórmula Pine: 1/3 por tramo)
      if hitTp3 = 1 then
         realizedR = (tradeTp1R + tradeTp2R + tradeTp3R) / 3.0
      elsif slHit then
         taken = 0
         remaining = 1.0
         if hitTp1 = 1 then
            taken = taken + (1.0/3.0) * tradeTp1R
            remaining = remaining - (1.0/3.0)
         endif
         if hitTp2 = 1 then
            taken = taken + (1.0/3.0) * tradeTp2R
            remaining = remaining - (1.0/3.0)
         endif
         realizedR = taken + remaining * (-1.0)
      else
         // timeout: solo suma los TPs tocados
         taken = 0
         if hitTp1 = 1 then
            taken = taken + (1.0/3.0) * tradeTp1R
         endif
         if hitTp2 = 1 then
            taken = taken + (1.0/3.0) * tradeTp2R
         endif
         if hitTp3 = 1 then
            taken = taken + (1.0/3.0) * tradeTp3R
         endif
         realizedR = taken
      endif
      // Clamp
      realizedR = max(-1.0, min(tradeTp3R, realizedR))

      // Push al buffer rotante
      $sigR[writeIdx] = realizedR
      writeIdx = writeIdx + 1
      if writeIdx >= maxHistory then
         writeIdx = 0
      endif
      if bufFilled < maxHistory then
         bufFilled = bufFilled + 1
      endif

      // Stats acumuladas
      allRSum = allRSum + realizedR
      allCount = allCount + 1
      allCumR = allCumR + realizedR
      if allCumR > allPeak then
         allPeak = allCumR
      endif
      curDD = allCumR - allPeak
      if curDD < allTrough then
         allTrough = curDD
      endif
      if realizedR > 0 then
         winStreak = winStreak + 1
         lossStreak = 0
         if winStreak > maxWinStreak then
            maxWinStreak = winStreak
         endif
      else
         lossStreak = lossStreak + 1
         winStreak = 0
         if lossStreak > maxLossStreak then
            maxLossStreak = lossStreak
         endif
      endif

      // Grid 3×3 EWMA update (despiadadamente manual por falta de arrays anidados)
      if tradeCellIdx = 0 then
         gridC0 = gridC0 + 1
         if gridC0 = 1 then
            gridE0 = realizedR
         else
            gridE0 = gridE0*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif
      if tradeCellIdx = 1 then
         gridC1 = gridC1 + 1
         if gridC1 = 1 then
            gridE1 = realizedR
         else
            gridE1 = gridE1*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif
      if tradeCellIdx = 2 then
         gridC2 = gridC2 + 1
         if gridC2 = 1 then
            gridE2 = realizedR
         else
            gridE2 = gridE2*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif
      if tradeCellIdx = 3 then
         gridC3 = gridC3 + 1
         if gridC3 = 1 then
            gridE3 = realizedR
         else
            gridE3 = gridE3*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif
      if tradeCellIdx = 4 then
         gridC4 = gridC4 + 1
         if gridC4 = 1 then
            gridE4 = realizedR
         else
            gridE4 = gridE4*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif
      if tradeCellIdx = 5 then
         gridC5 = gridC5 + 1
         if gridC5 = 1 then
            gridE5 = realizedR
         else
            gridE5 = gridE5*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif
      if tradeCellIdx = 6 then
         gridC6 = gridC6 + 1
         if gridC6 = 1 then
            gridE6 = realizedR
         else
            gridE6 = gridE6*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif
      if tradeCellIdx = 7 then
         gridC7 = gridC7 + 1
         if gridC7 = 1 then
            gridE7 = realizedR
         else
            gridE7 = gridE7*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif
      if tradeCellIdx = 8 then
         gridC8 = gridC8 + 1
         if gridC8 = 1 then
            gridE8 = realizedR
         else
            gridE8 = gridE8*(1-ewmaAlpha) + realizedR*ewmaAlpha
         endif
      endif

      // Auto-calibración (simplificación 1: determinista histórico)
      signalsSinceCalib = signalsSinceCalib + 1
      if (useAutoCalib = 1) and (bufFilled >= calibWindow) and (signalsSinceCalib >= calibCooldown) then
         // Avg R de los últimos calibWindow samples del buffer
         sumR = 0
         cnt  = 0
         n = calibWindow
         if n > bufFilled then
            n = bufFilled
         endif
         // lee hacia atrás desde writeIdx (que apunta al próximo slot libre)
         for k = 1 to n do
            idx = writeIdx - k
            if idx < 0 then
               idx = idx + maxHistory
            endif
            sumR = sumR + $sigR[idx]
            cnt = cnt + 1
         next
         if cnt > 0 then
            postAvgR = sumR / cnt
            if postAvgR < calibBadR then
               if effQStrength > qualityStrength then
                  drift = 0 - calibStepQ
               else
                  drift = calibStepQ
               endif
               effQStrength = min(calibMaxQ, max(calibMinQ, effQStrength + drift))
               signalsSinceCalib = 0
            elsif postAvgR > calibGoodR then
               signalsSinceCalib = 0
            endif
         endif
      endif

      // Cerrar trade (mantener tradeDir para que las líneas persistan en el dibujo)
      tradeClosed = 1
      tradeCellIdx = -1
   endif
endif

if useAutoCalib = 0 then
   effQStrength = qualityStrength
endif

//==========================================================
// 11. ROLLING STATS (win-rate, avg R, window DD)
//==========================================================
n = calibWindow
if n > bufFilled then
   n = bufFilled
endif
sumR2 = 0
wins = 0
runR = 0
minRun = 0
for k = 1 to n do
   idx = writeIdx - k
   if idx < 0 then
      idx = idx + maxHistory
   endif
   rVal = $sigR[idx]
   sumR2 = sumR2 + rVal
   if rVal > 0 then
      wins = wins + 1
   endif
   runR = runR + rVal
   if runR < minRun then
      minRun = runR
   endif
next
if n > 0 then
   rollWinRate = wins / n
   rollAvgR    = sumR2 / n
else
   rollWinRate = 0
   rollAvgR    = 0
endif
rollWindowDD = minRun

//==========================================================
// 12. DRAW SIGNAL LABELS
//==========================================================
if showSignals = 1 then
   if confirmedBuy then
      // Flecha pegada al mínimo
      drawtext("▲", barindex, low - 0.15*rawAtr) coloured(0, 230, 118, 255)
      // Score junto a la flecha, debajo de stLine (que está debajo del precio en compra)
      drawtext("BUY #buyScoreInt#", barindex, stLine - 0.3*rawAtr) coloured(0, 230, 118, 255)
   endif
   if confirmedSell then
      // Flecha pegada al máximo
      drawtext("▼", barindex, high + 0.15*rawAtr) coloured(255, 82, 82, 255)
      // Score junto a la flecha, encima de stLine (que está encima del precio en venta)
      drawtext("SELL #sellScoreInt#", barindex, stLine + 0.3*rawAtr) coloured(255, 82, 82, 255)
   endif
endif

//==========================================================
// 13. DRAW TP/SL LINES + etiquetas de precio al final
//==========================================================
if tradeDir <> 0 and islastbarupdate then
   xEnd   = barindex + labelOffsetBars
   xLabel = xEnd + 3
   // Redondeo a 2 decimales para texto (evita cola de floats feos)
   entryFmt = round(tradeEntry * 100) / 100
   slFmt    = round(tradeSl    * 100) / 100
   tp1Fmt   = round(tradeTp1   * 100) / 100
   tp2Fmt   = round(tradeTp2   * 100) / 100
   tp3Fmt   = round(tradeTp3   * 100) / 100

   // Entry
   drawsegment(tradeEntryBar, tradeEntry, xEnd, tradeEntry) coloured(150, 150, 150, 200)
   drawtext("Entry #entryFmt#", xLabel, tradeEntry) coloured(150, 150, 150, 255)
   // SL
   drawsegment(tradeEntryBar, tradeSl, xEnd, tradeSl) coloured(255, 23, 68, 255)
   drawtext("SL #slFmt#", xLabel, tradeSl) coloured(255, 23, 68, 255)
   // TPs (color distinto si ya tocado + marca ✓)
   if hitTp1 = 1 then
      drawsegment(tradeEntryBar, tradeTp1, xEnd, tradeTp1) coloured(64, 224, 208, 255)
      drawtext("TP1 #tp1Fmt# ✓", xLabel, tradeTp1) coloured(64, 224, 208, 255)
   else
      drawsegment(tradeEntryBar, tradeTp1, xEnd, tradeTp1) coloured(0, 230, 118, 200)
      drawtext("TP1 #tp1Fmt#", xLabel, tradeTp1) coloured(0, 230, 118, 255)
   endif
   if hitTp2 = 1 then
      drawsegment(tradeEntryBar, tradeTp2, xEnd, tradeTp2) coloured(64, 224, 208, 255)
      drawtext("TP2 #tp2Fmt# ✓", xLabel, tradeTp2) coloured(64, 224, 208, 255)
   else
      drawsegment(tradeEntryBar, tradeTp2, xEnd, tradeTp2) coloured(0, 230, 118, 200)
      drawtext("TP2 #tp2Fmt#", xLabel, tradeTp2) coloured(0, 230, 118, 255)
   endif
   if hitTp3 = 1 then
      drawsegment(tradeEntryBar, tradeTp3, xEnd, tradeTp3) coloured(64, 224, 208, 255)
      drawtext("TP3 #tp3Fmt# ✓", xLabel, tradeTp3) coloured(64, 224, 208, 255)
   else
      drawsegment(tradeEntryBar, tradeTp3, xEnd, tradeTp3) coloured(0, 230, 118, 255)
      drawtext("TP3 #tp3Fmt#", xLabel, tradeTp3) coloured(0, 230, 118, 255)
   endif
endif

//==========================================================
// 14. DASHBOARD (fixed top-right, anchor)
//==========================================================
if showDash = 1 and islastbarupdate then
   // Header
   drawtext("SATS  v1.9", -200, -10) anchor(topright, xshift, yshift) coloured(255,255,255,255)
   // Trend
   if trendDir = 1 then
      drawtext("Trend: Bullish ▲", -200, -30) anchor(topright, xshift, yshift) coloured(0, 230, 118, 255)
   else
      drawtext("Trend: Bearish ▼", -200, -30) anchor(topright, xshift, yshift) coloured(255, 82, 82, 255)
   endif
   // TQI
   if tqi > 0.6 then
      tqR = 0
      tqG = 230
      tqB = 118
   elsif tqi > 0.35 then
      tqR = 255
      tqG = 235
      tqB = 59
   else
      tqR = 255
      tqG = 82
      tqB = 82
   endif
   drawtext("TQI: #tqi#", -200, -50) anchor(topright, xshift, yshift) coloured(tqR, tqG, tqB, 255)
   // Q.Strength (efectivo, puede diferir del input por calibración)
   drawtext("Q.Str: #effQStrength#", -200, -70) anchor(topright, xshift, yshift) coloured(220,220,220,255)
   // Regime ER
   if erValue >= erHigh then
      drawtext("Regime: Trending", -200, -90) anchor(topright, xshift, yshift) coloured(0, 230, 118, 255)
   elsif erValue >= erLow then
      drawtext("Regime: Mixed", -200, -90) anchor(topright, xshift, yshift) coloured(255, 235, 59, 255)
   else
      drawtext("Regime: Choppy", -200, -90) anchor(topright, xshift, yshift) coloured(255, 82, 82, 255)
   endif
   // Vol regime
   if volRatio < volLow then
      drawtext("Vol: Low", -200, -110) anchor(topright, xshift, yshift) coloured(150,150,255,255)
   elsif volRatio < volHigh then
      drawtext("Vol: Normal", -200, -110) anchor(topright, xshift, yshift) coloured(220,220,220,255)
   else
      drawtext("Vol: High", -200, -110) anchor(topright, xshift, yshift) coloured(255, 180, 100, 255)
   endif
   drawtext("ER: #erValue#", -200, -130) anchor(topright, xshift, yshift) coloured(220,220,220,255)
   drawtext("VolRatio: #volRatio#", -200, -150) anchor(topright, xshift, yshift) coloured(220,220,220,255)
   // TP mode
   if useDynTp = 1 then
      drawtext("TP: Dynamic ×#finalScale#", -200, -170) anchor(topright, xshift, yshift) coloured(100,200,255,255)
   else
      drawtext("TP: Fixed", -200, -170) anchor(topright, xshift, yshift) coloured(220,220,220,255)
   endif
   drawtext("R live: #liveTp1R# / #liveTp2R# / #liveTp3R#", -200, -190) anchor(topright, xshift, yshift) coloured(220,220,220,255)
   // Stats
   drawtext("Signals: #bufFilled#", -200, -220) anchor(topright, xshift, yshift) coloured(200,200,200,255)
   if bufFilled >= 5 then
      if rollWinRate >= 0.5 then
         wrR = 0
         wrG = 230
         wrB = 118
      else
         wrR = 255
         wrG = 82
         wrB = 82
      endif
   else
      wrR = 150
      wrG = 150
      wrB = 150
   endif
   wrPct = rollWinRate * 100
   drawtext("WinRate: #wrPct#%", -200, -240) anchor(topright, xshift, yshift) coloured(wrR, wrG, wrB, 255)
   if bufFilled >= 5 then
      if rollAvgR > 0 then
         arR = 0
         arG = 230
         arB = 118
      else
         arR = 255
         arG = 82
         arB = 82
      endif
   else
      arR = 150
      arG = 150
      arB = 150
   endif
   drawtext("AvgR: #rollAvgR#", -200, -260) anchor(topright, xshift, yshift) coloured(arR, arG, arB, 255)
   drawtext("WindowDD: #rollWindowDD#R", -200, -280) anchor(topright, xshift, yshift) coloured(220,220,220,255)
   drawtext("AllDD: #allTrough#R", -200, -300) anchor(topright, xshift, yshift) coloured(220,220,220,255)
   drawtext("Streak W:#winStreak# / max #maxWinStreak#", -200, -320) anchor(topright, xshift, yshift) coloured(0,230,118,255)
   drawtext("Streak L:#lossStreak# / max #maxLossStreak#", -200, -340) anchor(topright, xshift, yshift) coloured(255,82,82,255)
   // Current regime edge (de la celda actual)
   if curCell = 0 then
      regC = gridC0
      regE = gridE0
   elsif curCell = 1 then
      regC = gridC1
      regE = gridE1
   elsif curCell = 2 then
      regC = gridC2
      regE = gridE2
   elsif curCell = 3 then
      regC = gridC3
      regE = gridE3
   elsif curCell = 4 then
      regC = gridC4
      regE = gridE4
   elsif curCell = 5 then
      regC = gridC5
      regE = gridE5
   elsif curCell = 6 then
      regC = gridC6
      regE = gridE6
   elsif curCell = 7 then
      regC = gridC7
      regE = gridE7
   else
      regC = gridC8
      regE = gridE8
   endif
   drawtext("RegimeEdge: #regE#R (n=#regC#)", -200, -360) anchor(topright, xshift, yshift) coloured(220,220,220,255)
endif

//==========================================================
// 15. PLOT: SuperTrend (patrón canónico PRT — ver PRC_Supertrend-TV)
//==========================================================
// UNA sola variable con coloured(r,g,b) dinámico. PRT pinta por tramos correctamente.
if trendDir = 1 then
   stR = 0
   stG = 230
   stB = 118
else
   stR = 255
   stG = 82
   stB = 82
endif

if isWarm then
   plotLine = stLine
else
   plotLine = undefined
endif

return plotLine coloured(stR, stG, stB) style(line, 2) as "SuperTrend"