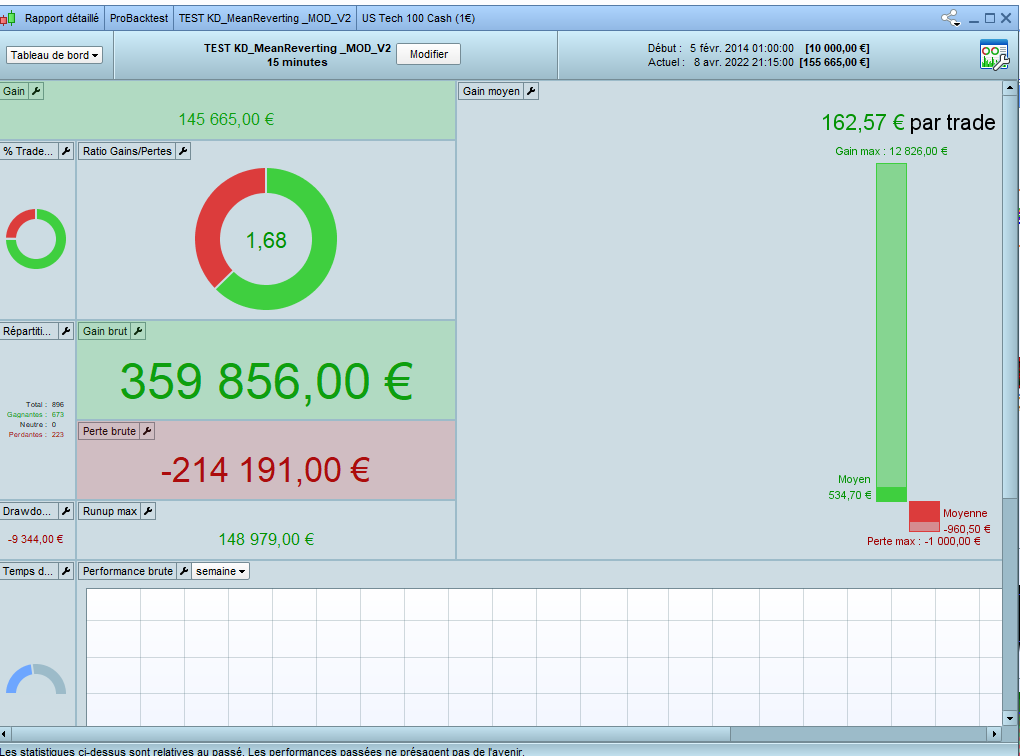
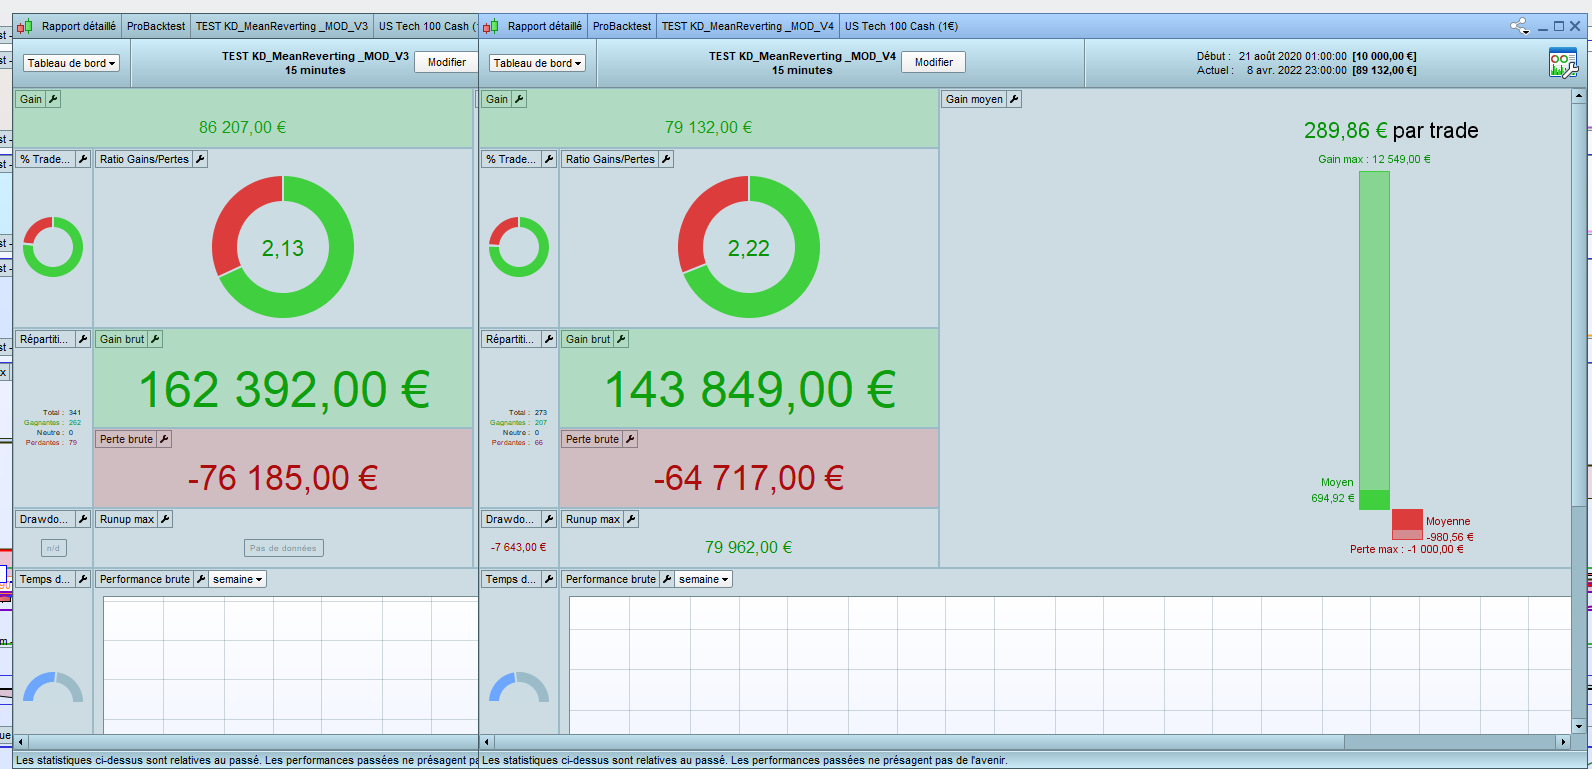
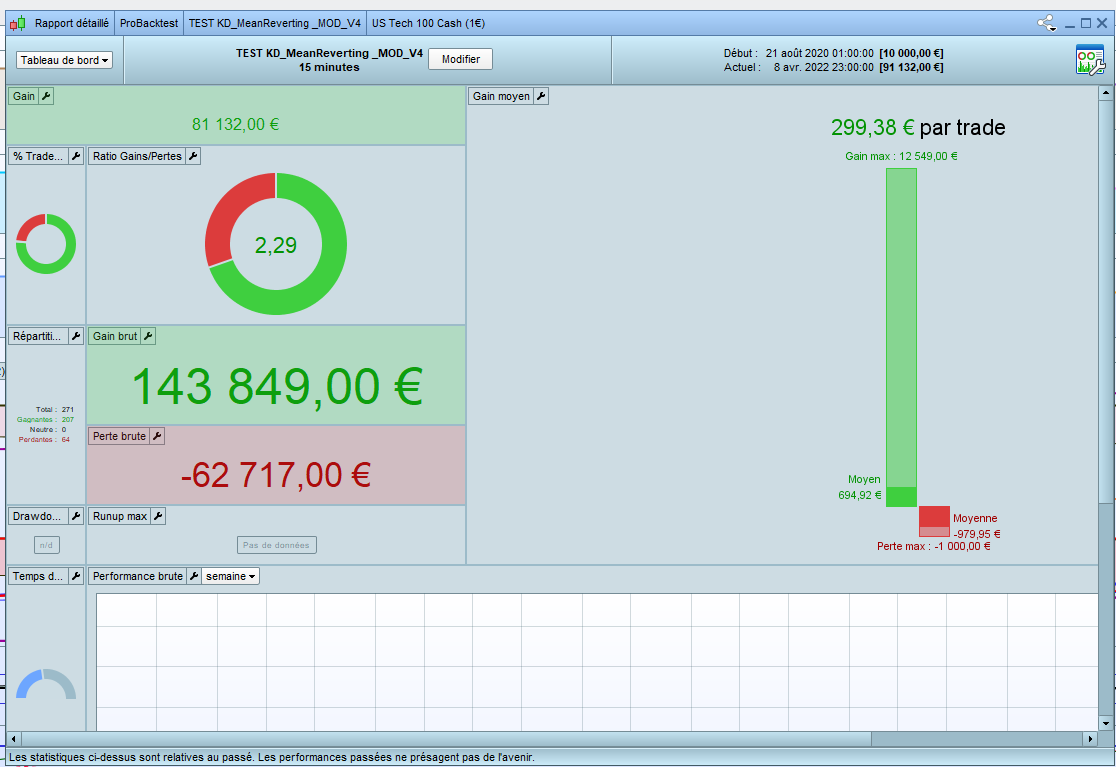
At the bottom of my code, I added this line
if longonmarket and close>positionprice and RSI[14](close)crosses under 70  and barindex-tradeindex>30 and opentime<130000 and close[1]-open[1]>20 then
sell at market
ENDIF
I modified the code for long entry and the difference between the two versions is high-high[1]>5
MM=average[30]
//and high-high[1]>5
cndLong= OPEN>MM and dopen(0)<close and high-close>1 and  high-close<20 and low[1]<close
// Conditions to enter long positions
If close > lowest[Pbars](low) and c1 and opendayofweek <> 5 and F1 and cndLong then
Buy PositionSize CONTRACTS AT MARKET
ENDIF
or this version
MM=average[30]
//
cndLong= OPEN>MM and dopen(0)<close and high-close>1 and  high-close<20 and low[1]<close and high-high[1]>5 and not(open<low[1])
// Conditions to enter long positions
If close > lowest[Pbars](low) and c1 and opendayofweek <> 5 and F1 and cndLong then
Buy PositionSize CONTRACTS AT MARKET
ENDIF
Hi Robert841 – Depending on the index, and whether it’s CFD or Spreadbet, it’s 0.2 or 0.5. Once you’ve run it in demo for a bit and are happy then you can try it on a small size.
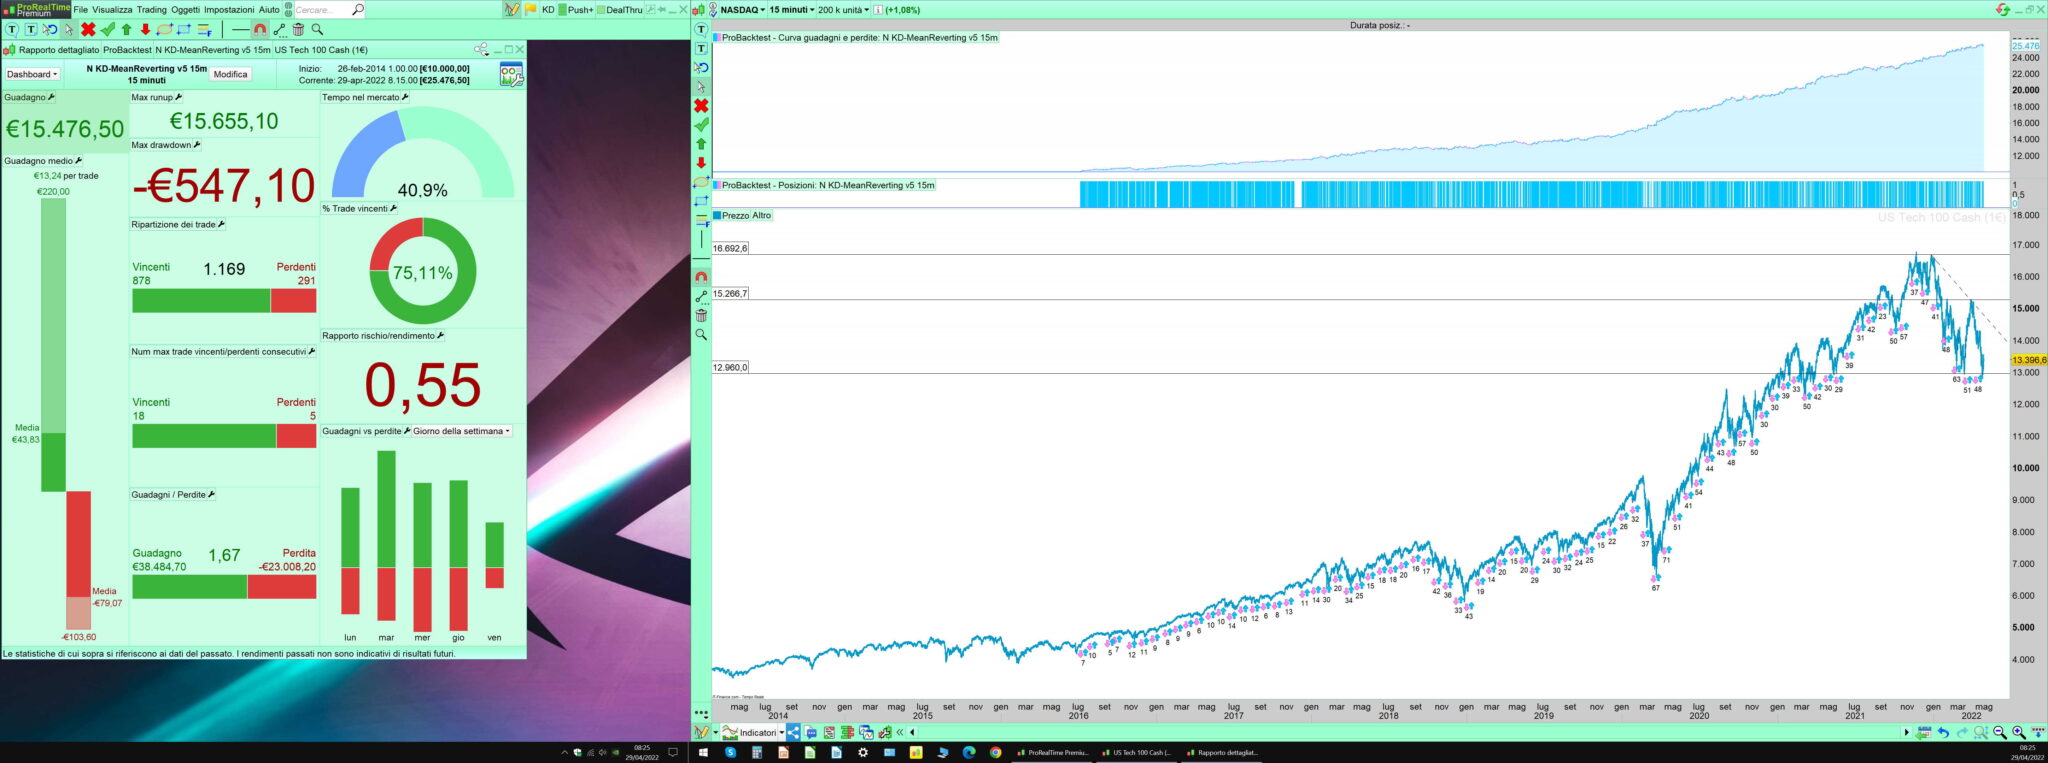
Hi, this is one of my revised and simplified versions (v5) with the addition of Fifi improvement.
//TS KD Mean Reverting v5 - Nasdaq 15 min
// spread 2 points
DEFPARAM CUMULATEORDERS = FALSE
positionSize = 1
//--------------------------------------------------------
avgHull = average[150,7]
nBarsVolume = 15
average30 = average[30](close)
//--------------------------------------------------------
c1L = close > avgHull
c2L = volume < volume[nBarsVolume]
c3L = open > average30 and dOpen(0)< close and high - close > 1 and high - close < 20 and low[1] < close  // [Fifi improvement "cndLong": rif. 191539]
//--------------------------------------------------------
If c1L and c2L and c3L and nLoss < nLossMax and openDayOfWeek <> 5 then
buy positionSize contracts at market
endif
//-------------------------------------------------------------------------------------
set target pProfit 220
set stop pLoss 100
//-------------------------------------------------------------------------------
once nLoss = 0
nLossMax = 2   //max N daily losses
if intradayBarIndex = 0 then
nLoss=0
endif
if strategyProfit < strategyProfit[1] then
nLoss=nLoss +1
endif
//------------------------------------------------------------------------
EZT = 1 //EZT (exit zombie trades - Nonetheless)
if EZT then
if longOnMarket and (barIndex-tradeIndex(1)>= 1600 and positionPerf<0)  then
sell at market
endif
endif
//-----------------------------------------------------
EWT = 1   //(exit winning trades - MauroPro)
nCandles = 8
percentTP        =  1.8
endTime   = 080000
if EWT then
if longOnMarket and (barIndex-tradeIndex(1)>nCandles and positionPerf*100 > percentTP) and (time>000000 and time<endTime) then
sell at market
endif
endif
//------------------------------------------------------------------
myRsi = rsi[14](close)      //RSI exit
if myRsi < 30  and longOnMarket and close > positionPrice  then
sell at market
endif
//----
if longOnMarket and close>positionPrice and RSI[14](close)>70 and  close-open>100 then  //added by Fifi
sell at market
ENDIF
//-------------------------------------------------------------------------------------------
pointToReachLong = 38*pointSize   // 30
pointToKeepLong =  12*pointSize
If not onMarket then
newSL = 0
endif
If longOnMarket then
If newSL = 0 and high-tradePrice(1)>pointToReachLong then
newSL = tradePrice(1)+ pointToKeepLong
endif
If newSL > 0 and close-newSL>pointToReachLong then
newSL = newSL+pointToKeepLong
endif
endif
If newSL > 0 then
sell at newSL STOP
endif
//-----------------------------------------------------------------------------------------------------
once bollPeriod = 20              // bollPercent Exit
once multiplier = 2
avgBoll = average[bollperiod,1](close)
stDevBoll = std[bollperiod]
bollUp = avgBoll + multiplier * stDevBoll
bollDown = avgBoll - multiplier * stDevBoll
bollPercent = 100 * (close - bollDown) / (bollUp - bollDown)
//-----------------------------------------------------------------------------
once rangeOk = 40
once timeOk = 0
if time <= 090000 or time >= 210000 and (high - low) > rangeOk then
timeOk = 0
endif
IF time >= 080000 and time <= 200000 and (high - low) > rangeOk then
timeOk = 1
endif

period = 4     // exit with 2 of the last 4 bars below the threshold of 40 bollPerCent
levelPercent = 40
candleNum = 2
if  timeOk = 1 and (barIndex - tradeIndex) < 12 and summation[period](bollPercent < levelPercent) = candleNum then
sell at market
endif
//------------------------------------------------------------------------------------------------------------