Linear Regression Universal Strategy, how to improve it?

Viewing 3 posts - 31 through 33 (of 33 total)
  • Author
    Posts
  • #199676 quote
    GraHal
    Participant
    Master

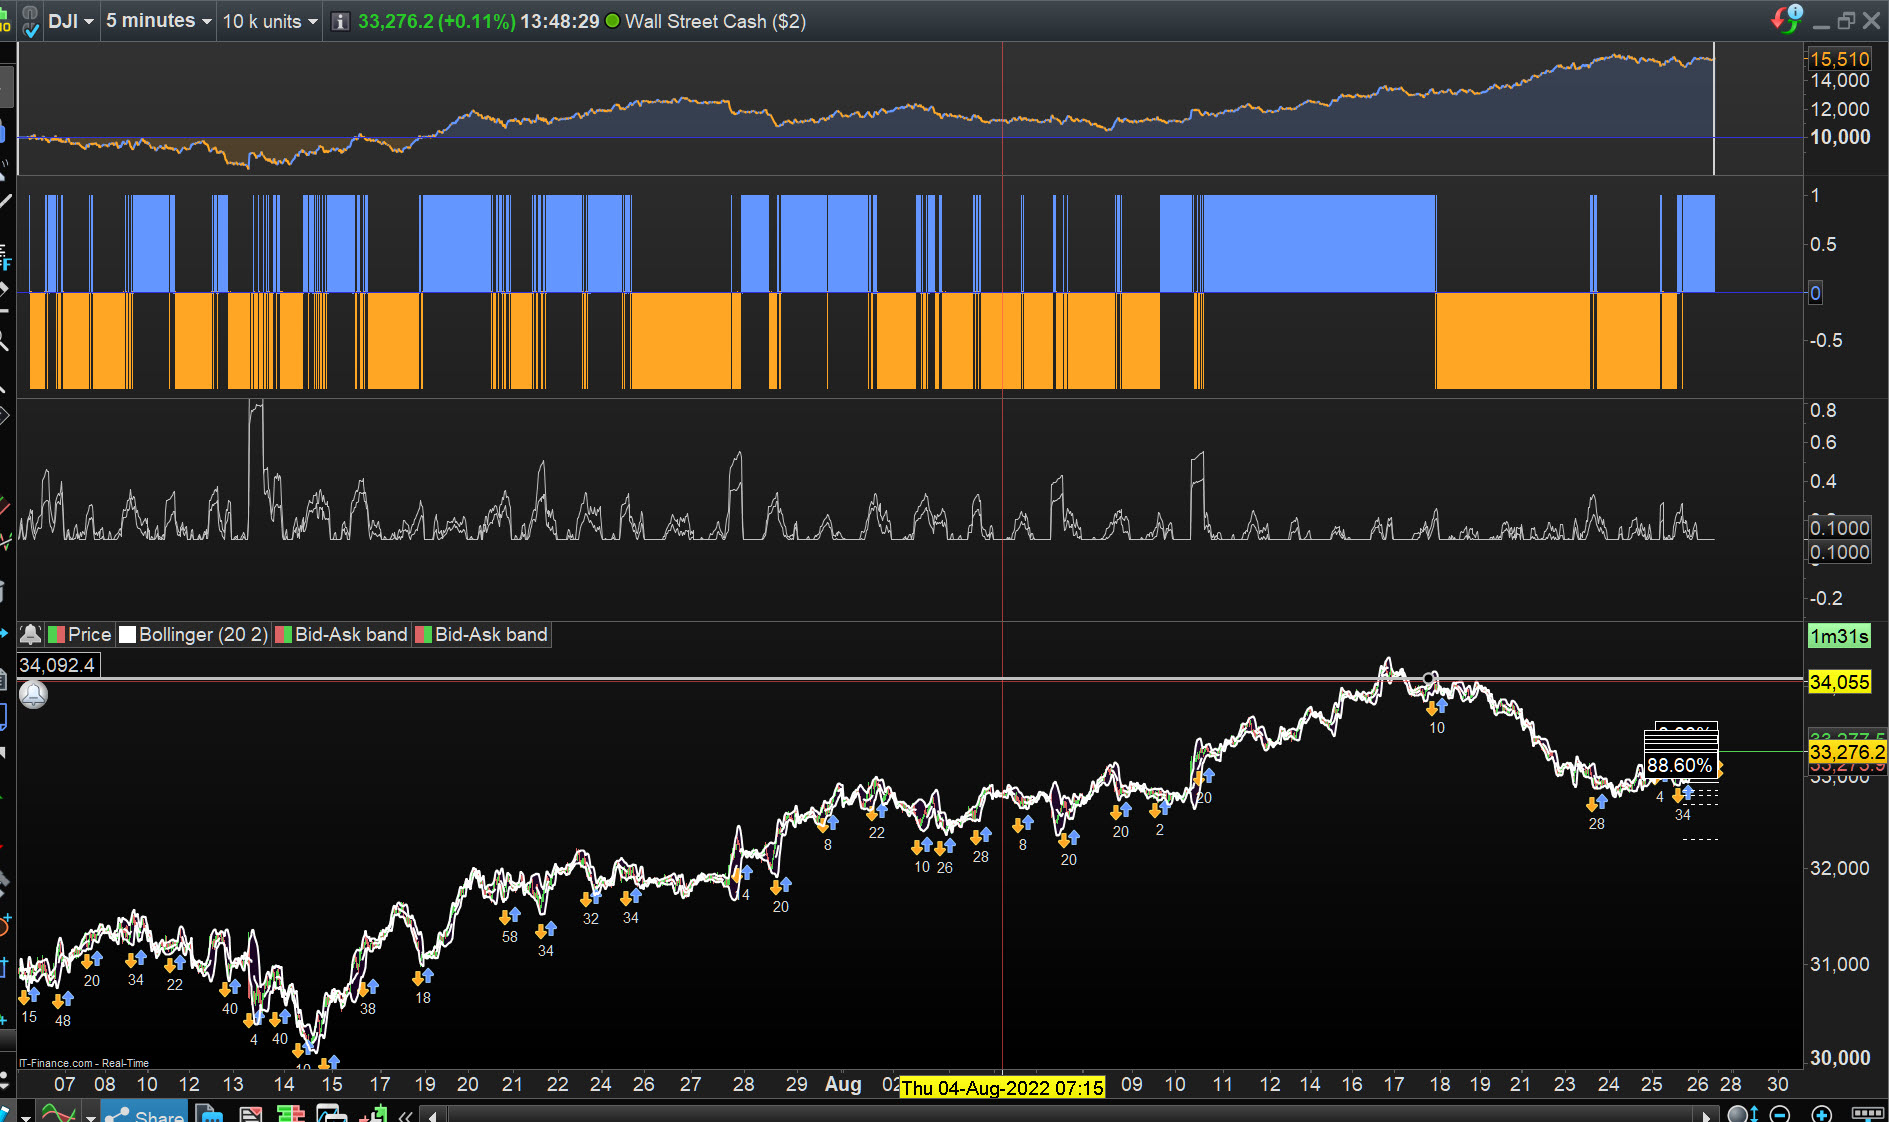
    I tried below, didnt affect results (attached) but still got Rejected!

    //https://www.prorealcode.com/topic/linear-regression-universal-strategy-how-to-improve-it/#post-199478//Linear Regression Universal Strategy
    // instrument: CNHJPY
    // timezone : europetime, berlin
    // timeframe : Daily
    // Spread: 0.7
    // created and coded by davidelaferla
    //————————————————————————-
     
    defparam cumulateorders=false
    DEFPARAM PRELOADBARS = 10000
     
    //***********************************************************************************************************
    N = 1
    //------------------ VARIABILI DEL SISTEMA---------------------------------------
    //CNHJPY Values:      -------------------------------------------- Ottimization info
    Volatilityperiod=A15 //15// different fixed value for each currency pair: range=3-20, with step=1
    Regression1period=A16 //18// Linear Regression Imput Signal:              range=6-100 with step=1
    Regression2period=A17 //1.3//Linear Regression Output Signal:             range=1-2, with step=0.01
    //***********************************************************************************************
    //------------------ INDICATOR ---------------------------------------
    if barindex>=10000 then
    hv=Max(0.1,HistoricVolatility[VolatilityPeriod](close))
    hv2=Max(0.1,HistoricVolatility[VolatilityPeriod](typicalprice))
    endif
    if barindex>=10000 then
    lr=linearregression[max(1,ROUND(Regression1Period*Regression2Period*hv2))](typicalprice)
    st=linearregression[max(1,ROUND(Regression1Period*hv))](close)
    endif
    //st=linearregression[ROUND(Regression1Period*hv)](close)
    //lr=linearregression[ROUND(Regression1Period*Regression2Period*hv2)](typicalprice)
     
    // Condizioni per uscire da posizioni short e entrare su posizioni long
    IF st<lr THEN
    BUY n contract AT lr stop
    ENDIF
    // Condizioni per uscire da posizioni long e entrare su posizioni short
    IF st>lr THEN
    SELLshort n contract At st stop
    ENDIF
    
    GRAPH HV
    GRAPH HV2
    
    Rejects.jpg Rejects.jpg
    #199682 quote
    JC_Bywan
    Moderator
    Master

    Maybe Linearregression doesn’t like the easy job of having just 1 point to look at, and wants 2 points at least before deeming it acceptable to play with us pleb…

    so: max(2,ROUND(…  (to modify twice)  (worked without rejection this time)

    defparam cumulateorders=false
    DEFPARAM PRELOADBARS = 10000
    
    //***********************************************************************************************************
    ONCE A15 = 25.0
    ONCE A16 = 10.0
    ONCE A17 = 0.8
    N = 1
    //------------------ VARIABILI DEL SISTEMA---------------------------------------
    //CNHJPY Values: -------------------------------------------- Ottimization info
    Volatilityperiod=A15 //15// different fixed value for each currency pair: range=3-20, with step=1
    Regression1period=A16 //18// Linear Regression Imput Signal: range=6-100 with step=1
    Regression2period=A17 //1.3//Linear Regression Output Signal: range=1-2, with step=0.01
    //***********************************************************************************************
    //------------------ INDICATOR ---------------------------------------
    
    hv=HistoricVolatility[VolatilityPeriod](close)
    hv2=HistoricVolatility[VolatilityPeriod](typicalprice)
    
    if barindex>=VolatilityPeriod then
    lr=linearregression[max(2,ROUND(Regression1Period*Regression2Period*hv2))](typicalprice)
    st=linearregression[max(2,ROUND(Regression1Period*hv))](close)
    endif
    
    //
    IF st<lr THEN
    if close<lr then
    BUY n contract AT lr stop
    elsif close>lr then
    BUY n contract AT lr limit
    ENDIF
    //
    IF st>lr THEN
    if close>st then
    SELLshort n contract At st stop
    elsif close<st then
    SELLshort n contract At st limit
    endif
    ENDIF
    GraHal and Midlanddave thanked this post
    #199691 quote
    GraHal
    Participant
    Master

    Genius JC! Thank You!

    I have a 1 hour TF and 12 min TF version running, both have run through a ‘first full bar’ and neither have been rejected!

Viewing 3 posts - 31 through 33 (of 33 total)
  • You must be logged in to reply to this topic.
ProRealAI ProRealAI New

Stuck on this ProBuilder code?

Describe what this topic is trying to build, in plain English, and ProRealAI writes the ProRealTime™ indicator, screener or system for you.

Available in 7 languages
Try ProRealAI

Linear Regression Universal Strategy, how to improve it?


ProOrder: Automated Strategies & Backtesting

New Reply
Author
Summary

This topic contains 32 replies,
has 6 voices, and was last updated by GraHal
4 years ago.

Topic Details
Forum: ProOrder: Automated Strategies & Backtesting
Language: English
Started: 08/23/2022
Status: Active
Attachments: 4 files
Logo Logo
Loading...