Hi guys !
This is the first system I post here.
I made my own version of Reiners Trend surfer DAX, whith Nicolas´ TDI indicator and my own parameters but the backtest doesn´t work,
I think it might be because of the trailing stop and take profit which are variables (a and b in the code) that I want to optimize because this will be how I exit the trades, no exit on signal, just sl/tp.
The message just says “an error occured” but doesn´t say where or why.
Here´s the code :
// Trend Surfer DAX Modified

// code-Parameter
DEFPARAM FlatAfter = 173000
DEFPARAM FlatBefore = 093000

// DAX trading window
ONCE BuyTimeMorning = 093000
ONCE SellTimeMorning = 110000
ONCE BuyTimeAfternoon = 130000
ONCE SellTimeAfternoon = 170000

ONCE lengthRSI = 13
ONCE lengthband = 34
ONCE lengthrsipl = 3
ONCE lengthtradesl = 7
ONCE lineup = 68
ONCE linemid = 50
ONCE linedown = 32

// trading parameter
ONCE PositionSize = 1
ONCE sl = a
ONCE tp = b*sl

// emergency stop
IF STRATEGYPROFIT <-500 THEN
QUIT ENDIF

// position management during trading window
IF (Time >= BuyTimeMorning AND Time <= SellTimeMorning) OR (Time >= BuyTimeAfternoon AND Time <= SellTimeAfternoon) THEN

// calculate TDI indicator
r = rsi[lengthrsi](close)
ma = average[lengthband](r)
offs = (1.6185 * std[lengthband](r))
blueup = ma+offs
bluedn = ma-offs
jaune = (blueup+bluedn)/2
vert = average[lengthrsipl](r)
rouge = average[lengthtradesl](r)

// open position
// long
IF Not ONMARKET AND rouge<bluedn AND vert CROSSES OVER rouge OR rouge<linedown AND vert CROSSES OVER rouge THEN
BUY PositionSize CONTRACT AT MARKET
ENDIF
IF Not ONMARKET AND rouge>linemid AND vert CROSSES OVER rouge THEN
BUY PositionSize CONTRACT AT MARKET
ENDIF
IF Not ONMARKET AND rouge CROSSES OVER jaune THEN
BUY PositionSize CONTRACT AT MARKET
ENDIF


// short
IF Not ONMARKET AND rouge>blueup AND vert CROSSES UNDER rouge OR rouge>lineup AND vert CROSSES UNDER rouge THEN
SELL PositionSize CONTRACT AT MARKET
ENDIF
IF Not ONMARKET AND rouge<linemid AND vert CROSSES UNDER rouge THEN
SELL PositionSize CONTRACT AT MARKET
ENDIF
IF Not ONMARKET AND rouge CROSSES UNDER jaune THEN
SELL PositionSize CONTRACT AT MARKET
ENDIF

// stop and profit
SET STOP pTRAILING sl
SET TARGET pPROFIT tp

ENDIF
can someone help please ?
Remove ENDIF from line 28 and place it at line 29.
Okay ! It does work now (the backtest not the system…yet) thank you ! .
I´ve got another problem now (I put fixed sl/tp for now) : the system only goes long and cumulates orders, I don´t get it !
It never goes short and sometimes it takes 2 long positions instead of one.
I tried to fixe the problem and put EXITs on trades at market when it should reverse, but it doesn´t work, any ideas ?
Here´s the modified code :
// open position
// long
IF Not ONMARKET AND rouge<bluedn AND vert CROSSES OVER rouge OR rouge<linedown AND vert CROSSES OVER rouge OR rouge>linemid AND vert CROSSES OVER rouge OR rouge CROSSES OVER jaune THEN
IF SHORTONMARKET THEN
BUY AT MARKET
ENDIF
BUY PositionSize CONTRACT AT MARKET
ENDIF


// short
IF Not ONMARKET AND rouge>blueup AND vert CROSSES UNDER rouge OR rouge>lineup AND vert CROSSES UNDER rouge OR rouge<linemid AND vert CROSSES UNDER rouge OR rouge CROSSES UNDER jaune THEN
IF LONGONMARKET THEN
SELL AT MARKET
ENDIF
SELL PositionSize CONTRACT AT MARKET
ENDIF

// stop and profit
SET STOP pTRAILING sl
SET TARGET pPROFIT tp

ENDIF
You need below as the 1st line of code …
DEFPARAM CumulateOrders = False
Thank you Grahal ! That´s it for cumulated orders.
Now the system doesn´t short, worse, it takes long positions where it shoud sell, I read it again and again but can´t figure it out.
BUY //Opens a long position
SELL //Closes a long position

SELLSHORT //Opens a short position
EXITSHORT //Closes a short position
You are using a SELL where you need a SELLSHORT
wow I didn´t know that, thank you !
I am sorry to waste your time with beginners problems,
The good thing is that I have an edge now ! Yeeeaahh ! I just need to optimise sp/tp
so here´s the code for now:
// Trend Surfer DAX Modified
DEFPARAM CumulateOrders = False

// code-Parameter
DEFPARAM FlatAfter = 173000
DEFPARAM FlatBefore = 090500

// DAX trading window
ONCE BuyTimeMorning = 090500
ONCE SellTimeMorning = 110000
ONCE BuyTimeAfternoon = 130000
ONCE SellTimeAfternoon = 170000

ONCE lengthRSI = 13
ONCE lengthband = 34
ONCE lengthrsipl = 3
ONCE lengthtradesl = 7
ONCE lineup = 68
ONCE linemid = 50
ONCE linedown = 32

// trading parameter
ONCE PositionSize = 1
ONCE sl = 50
ONCE tp = 50

// emergency stop
IF STRATEGYPROFIT <-500 THEN
QUIT
ENDIF


// position management during trading window
IF (Time >= BuyTimeMorning AND Time <= SellTimeMorning) OR (Time >= BuyTimeAfternoon AND Time <= SellTimeAfternoon) THEN

// calculate TDI indicator
r = rsi[lengthrsi](close)
ma = average[lengthband](r)
offs = (1.6185 * std[lengthband](r))
blueup = ma+offs
bluedn = ma-offs
jaune = (blueup+bluedn)/2
vert = average[lengthrsipl](r)
rouge = average[lengthtradesl](r)

// open position
// long
IF Not ONMARKET AND rouge<bluedn AND vert CROSSES OVER rouge OR rouge<linedown AND vert CROSSES OVER rouge OR rouge>linemid AND vert CROSSES OVER rouge OR rouge CROSSES OVER jaune THEN
BUY PositionSize CONTRACT AT MARKET
ENDIF


// short
IF Not ONMARKET AND rouge>blueup AND vert CROSSES UNDER rouge OR rouge>lineup AND vert CROSSES UNDER rouge OR rouge<linemid AND vert CROSSES UNDER rouge OR rouge CROSSES UNDER jaune THEN
SELLSHORT PositionSize CONTRACT AT MARKET
ENDIF

// stop and profit
SET STOP pTRAILING sl
SET TARGET pPROFIT tp

ENDIF
So, optimisation gives me Trailingstop = 49 and tp= 2.9*sl , but only on 10 000 bars, could someone test it on a 100 000 bars version ?
Now I have another problem, there are still bits where the trade is taken in the opposite direction (i.e. 23/01/2018 after 9H00 and goes on all day long) of where it should go, I will see if I can solve it.
Which also this system can give us more, I will pursue the investigation.
I am sorry to waste your time with beginners problems,
We are happy to help when we get a good explanation of the Issue (as you have done).
What Timeframe is this to be run on? I can’t see TF anywhere sorry?
could someone test it on a 100 000 bars version ?
We are all willing to help, but you should be able to test yourself on 100k bars.
@Grahal : it is on 5min.
@Nicolas : hi ! On ut 5 min, I only got 10 000 bars, maybe if I put x bars and 100 000 it will work, I will try as soon as I get home.
maybe if I put x bars and 100 000 it will work,
Yes! That’s how it works! 😉
Great ! Thanks !
I can’t wait to get home, 16h of bus, from berlin to Paris, this will hurt…
Okay, back from Berlin,
It’s 4:30 am, I spent the night, backtesting and optimising the strategy (on 100 000 candles 😉 ), I even broke it into pieces, optimizing each one and ….
it goes nowhere, ratios are not good or not good enough.
So I threw it away and started a new one. This is a trend surfer DAX too, so I think we can keep it in the same thread.
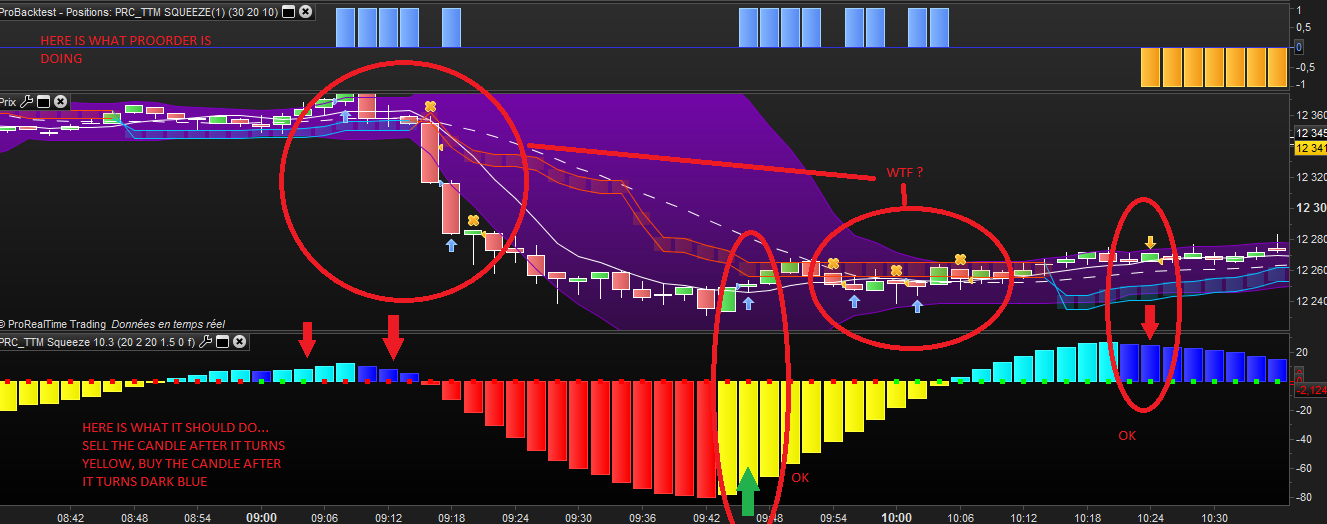
It’s 2min, 1pt spread, based on nicolas’ PRC_TTM SQUEEZE and Verdi’s Breakeven that I found in Grahal’s snippets.
It’s simple : buy when it turns from red to yellow and sell when it turn from blue to dark blue.
I’m close to get it right, I just got one problem, the system buys on every yellow (next candle of course) and sells on every blue (see the picture attached).
Here is the code :
// Trend Surfer DAX Modified
DEFPARAM CumulateOrders = False

// code-Parameter
DEFPARAM FlatAfter = 180000
DEFPARAM FlatBefore = 080500

// DAX trading window
ONCE BuyTimeMorning = 090500
ONCE SellTimeMorning = 110000
ONCE BuyTimeAfternoon = 130000
ONCE SellTimeAfternoon = 173000

// trading parameter
ONCE sl = a
ONCE tp = b
ONCE lengthKC=20

// position management during trading window
IF (Time >= BuyTimeMorning AND Time <= SellTimeMorning) OR (Time >= BuyTimeAfternoon AND Time <= SellTimeAfternoon) THEN

value = (Highest[lengthKC](high)+Lowest[lengthKC](low)+average[lengthKC](close))/3
val = linearregression[lengthKC](close-value)


if val>0 and val<val[1] then
IF LONGONMARKET THEN
SELL 1 SHARES AT MARKET
SELLSHORT 1 SHARES AT MARKET
ELSE
SELLSHORT 1 SHARES AT MARKET
ENDIF
ENDIF


if val<0 and val>val[1] then
IF SHORTONMARKET THEN
EXITSHORT 1 SHARES AT MARKET
BUY 1 SHARES AT MARKET
ELSE
BUY 1 SHARES AT MARKET

ENDIF
ENDIF


StopdistanceBreakeven = c
NormalStop = sl

nb = barindex - tradeindex
minprice = lowest[nb + 1](Low)
maxprice = highest[nb + 1](High)

If longonmarket then
If maxprice >= positionprice + StopdistanceBreakeven then
sell at (positionprice + 1) stop
else
sell at positionprice - NormalStop stop
endif
endif

If shortonmarket then
If minprice <= positionprice - StopdistanceBreakeven then
exitshort at (positionprice - 1) stop
else
exitshort at positionprice + NormalStop stop
endif
endif
// stop and profit
//SET STOP pLOSS sl
SET TARGET pPROFIT tp

ENDIF
My guess is I should define what is yellow and dark blue (this I think I can do) and then buy/sell on the change of color (this I have no idea, how do you say “buy if red then yellow ???)
Can you help ?
Also, when I do the backtest, I have MFE and MAE in the closed positions toggle, which one should I trust ? (Cause I like MAE 🙂 )
Should I do a “e-ratio” like I read somewhere on the internet ?
Also, when I do the backtest, I have MFE and MAE in the closed positions toggle, which one should I trust ? (Cause I like MAE )
Glad you got back safe, shouldn’t you have been sleeping at 4:30 AM? 🙂
My brain has not woken enough yet re most of the questions, but MFE is Max Profit and MAE is Max Loss during that trade.
I check these and if a Strategy shows big MAE and then eventually a small MFE for lots of individual trades then I consider the Strat not good (even if overall a good profit shows). Reason: it would mean I’ve been sitting there stressing while the trade has had big drawdowns! Okay eventually it managed repeatedly to hitch-hike onto a favourable trend and come out smelling of roses / profit in the end, but the journey was tiring … just like yours from Berlin to Paris! 🙂
Cheers
GraHal
PS I drew same conclusion as you re your original Strat, but I didn’t like to say.
Thank you for your sterling effort through the night on the new version Strat, I will test it out later.