






USDJPY 3candles and reversal strategy with ADX and VOL filter.
Dear all
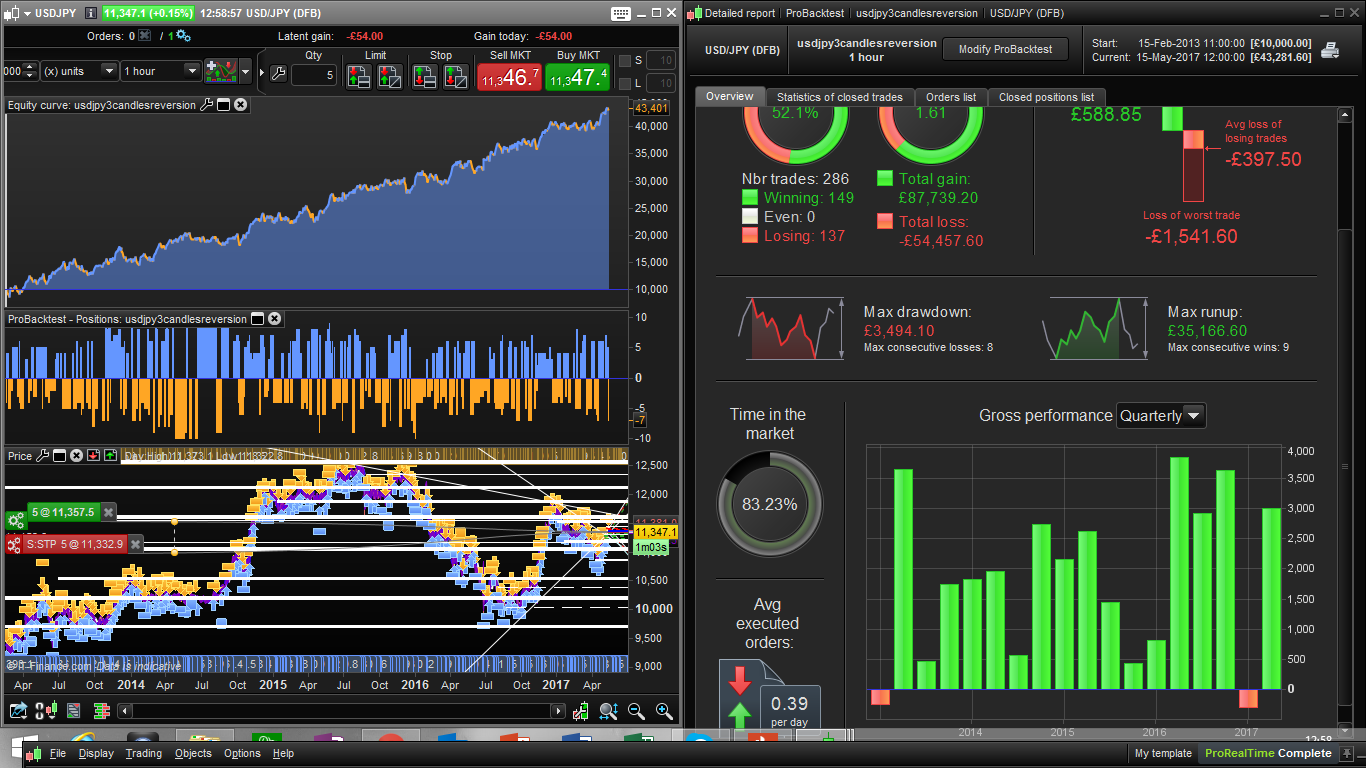
I have been playing around with the concept of reversal after n consecutive bullish or bearish bars and I found a quite nice result in the USD JPY 1 hr timeframe.
The strategy has 3 condition:
- 3 consecutive bars of hte same colour
- ADX > ADXmin
- Vol > Volmin ( expressed in ATR )
In attachment you find the results of a WF static analysis 70/30 with 3 variables.
Please feel free to comment, any constructive criticism will be greatly appreciated!
//USDJPY TF 1hr spread 1.5 pips

DEFPARAM CUMULATEORDERS = False
//DEFPARAM FLATBEFORE = 090000
//DEFPARAM FLATAFTER = 220000

//n = 3  // number of consecutive bars with the same colour
fastavperiod=5 /// period of fast moving average
slowavperiod=100// period of slow moving average
atrmin= 10 // take poistion only if there is enough vol
//adxval = 25 // take position only if there is a trend
//t = 7 // multiplier for exit strategy

volindic = averagetruerange[14]
fastav = average[fastavperiod](close)
slowav = average[slowavperiod](close)
cl = summation[n](close<open) = n
cs = summation[n](close>open) = n
volok = volindic > atrmin
ctrend = adx[14]>adxval
position = round(100/averagetruerange[14])

if cl and ctrend and fastav > slowav and volok then
 buy position contract at market
endif

if cs  and ctrend and fastav < slowav and volok then
 sellshort  position contract at market
endif

set target profit t*volindic
set stop ploss 2*t*volindic
Comments
You must be logged in to post a comment.
Hi Pepmartorell, please let's continue the discussion on the forum thread so that we can share pictures, I would like to see a snapshot of your screen when you try the backtest in order to help you.
this is the link
https://www.prorealcode.com/topic/ncandle-and-reversal-filtered-strategy/
Hi Pepmartorell, please let's continue the discussion on the forum thread so that we can share pictures, I would like to see a snapshot of your screen when you try the backtest in order to help you.

It seems it doesn't work, even with the change proposed by Francesco78. In fact the maximum amount of winning trades in my nacktest simulation is under 10%...
Where's my error? I apply the code on USDJPY at 1-hour frame, wth 1.5 pips, etc.
ciao Dario,
try to change line 19 with
volok = volindic > atrmin*pointsize
Let me know.
Best

THIS doesn't work. no operations
Hi Grahal, thanks for your attention to my strategy, yes there is a forum thread I opened.
https://www.prorealcode.com/topic/ncandle-and-reversal-filtered-strategy/

Thanks! I hope this will sort the issues some people were experiencing

The problem is at line 19, you should adapt the 'atrmin' variable to the pointsize of the current security:
volok = volindic > atrmin*pointsize
I think there might be a problem in the stoploss size, you should use "loss" instead of "ploss", to be perfectly compatible with any instrument:
set stop loss 2*t*volindic
(like you did correctly for the takeprofit).
Ok thank you, I hope we will be able to find what is missing so that we can share our results more efficently in the future.
Ciao

Unfortunately not. However it is possible that there is a setting somewhere on your system that is different to ours.
The strategy however still holds merit as I can produce decent results on other markets, proving it is a valid strategy to outperform a given market.
I have strategies in place that outperform it on the 1 hr but the results are still good and the strategy can definitely be built upon.
ok I see, many thanks, so you are not able to replicate the results on USDJPY right?
Hi Francesco, I did use v10.3, however like the others I am having trouble running it on FX pairs on the original code. But the re-written code work well.
Your strategy also adapts very well to other markets. I have managed to get some good results out of it on some of the indexes.
It's a very cool idea. Well Done
are you all using v 10.3?
Guys volok means VOLATILITY ok.
there is no reference to volume in this code whatsoever

Guys can you pls let me know if any one of you can run the code at all?
Thanks
@ DEIO
what do you mean? you mean that id doesnt give you any trade for currencies?
From what I have been looking at, it works well with USDCAD, GBPJPY, CADJPY and BUND
Hi Junaji, thank for your comments, I have always backtested in tick by tick mode. Please do not use any flat bore and flat after. I forgot to remove them from the original code. With flatbefore and flatafter the results are negative.
Best
I think the problem lies with the 'volok' parameter (line 19 in original code). I have rewritten the code to systematically determine where the problem might be (my flatbefore time is different due to my timezone).
Unfortunately using tick by tick testing yields negative results. Without tcik by tick the code performs very well in test period March 2013 to Current except for a period between March and October 2014 where there is a large draw down period.
//USDJPY TF 1hr spread 1.5 pips
DEFPARAM CUMULATEORDERS = False
DEFPARAM PRELOADBARS = 14
DEFPARAM FLATBEFORE = 010000
DEFPARAM FLATAFTER = 200000
possize = 1//round(100/averagetruerange[14])
n = 3 // number of consecutive bars with the same colour
fastma = 5 /// period of fast moving average
slowma = 100// period of slow moving average
adxval = 25 // take position only if there is a trend
t = 7 // multiplier for exit strategy
atr = averagetruerange[14](close)
atrmin = 10 // take poistion only if there is enough vol
fastav = average[fastma,1](close)
slowav = average[slowma,1](close)
red = 0
green = 0
For i = 1 to n
If close[i] > open[i] then
red = red + 1
ElsIf close[i] < open[i] then
green = green + 1
EndIf
Next
volok = 1 //no volume for security
If atr > atrmin then
volok = 1
EndIf
ctrend = 0
If adx[14] > adxval Then
ctrend = 1
EndIf
if countofposition = 0 and red >= n and ctrend = 1 and fastav > slowav and volok = 1 then
buy possize contract at market
endif
if countofposition = 0 and green >= n and ctrend = 1 and fastav < slowav and volok = 1 then
sellshort possize contract at market
endif
set target pprofit t*atr
set stop ploss 2*t*atr
Is it for working for anyone of you?

mm ok.. Im really wondering what's going on..
I'm testing it across many different currency pair and bund and seems to stay up quite nicely in most of the cases and most of timeframes.. I have a UK account but it shouldn't make any difference.
Try to use constant position maybe?
Nicolas was it working properly when you reviewed it?
mm ok.. Im really wondering what's going on..
I'm testing it across many different currency pair and bund and seems to stay up quite nicely in most of the cases and most of timeframes.. I have a UK account but it shouldn't make any difference


Hi there, i am looking at your Strategy however when you put in automatic trading mode its saying that I have to remove all the variables from the "Probacktest" and to replace them with specific numeric values in the code of the trading system? can you help me as I am not sure how to do this? Thank you