






As simple as it gets: EURUSD 2h ATR strength
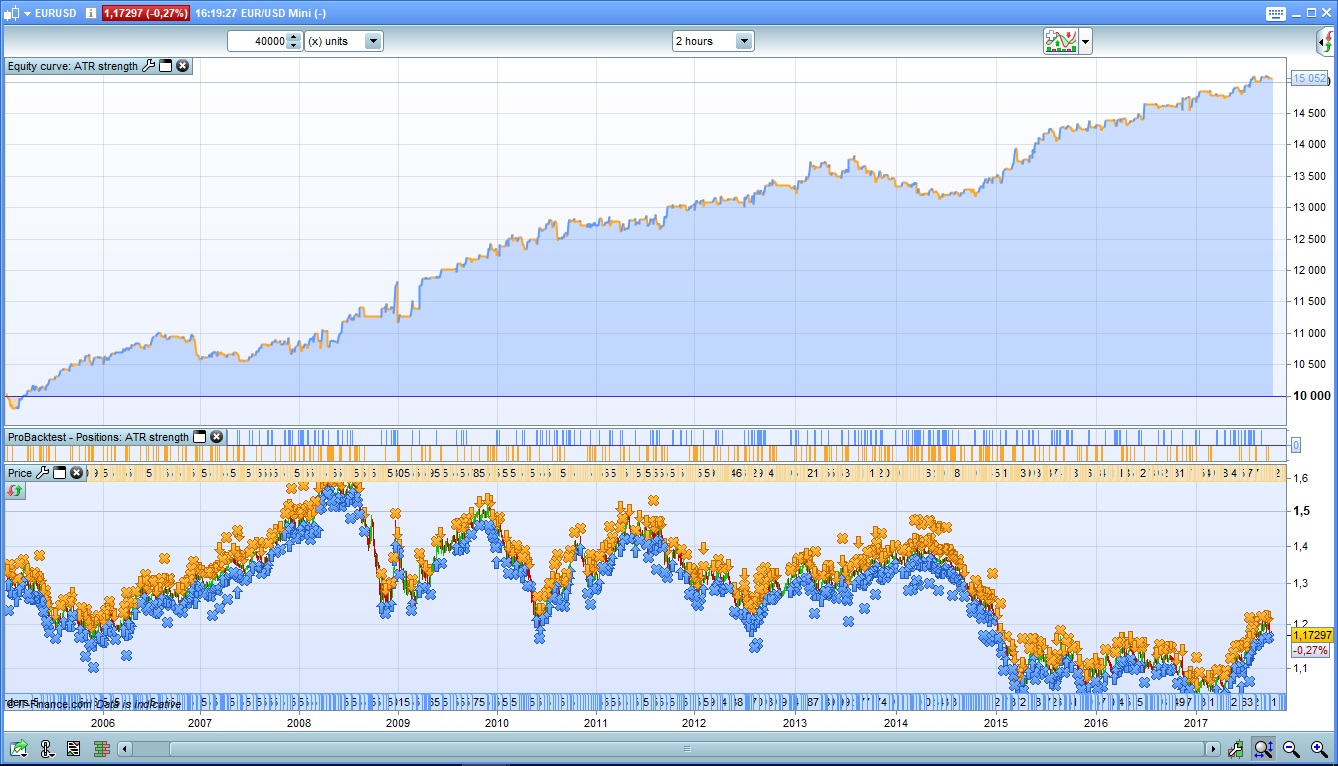
This is a really simple system in its base form. It has no filters or money management. I submit it only to show what can be done with VERY simple entry & exit rules. I’m pretty sure this could be developed further into an implementable system.
The basis is EUR/USD on 2h timeframe. It might work on other assets, I haven’t tried yet.
The system will initiate a long if there is a green body exceeding ATR(20)*2. It will exit the long on another green body exceeding ATR(20)*2, or on the 9th bar after entry, or if a short position is initiated.
The system will initiate a short if there is a red body exceeding ATR(20)*2. It will exit the short on another red body exceeding ATR(20))*2, or on the 9th bar after entry, or if a long position is initiated.
There you go, as simple as that. Good luck with your adaptations!
ATR = AverageTrueRange[14](close)

LongEntry = close - open > ATR * 2
LongExit = close - open > ATR * 2 OR BarIndex = TradeIndex + 8

ShortEntry = open - close > ATR * 2
ShortExit = open - close > ATR * 2 OR BarIndex = TradeIndex + 8

Maxpos = 1

// Conditions to enter long positions
IF CountOfLongShares < MaxPos AND LongEntry THEN
 BUY 1 CONTRACTS AT MARKET
ENDIF

// Conditions to exit long positions
If LongOnMarket AND LongExit THEN
 SELL AT MARKET
ENDIF

// Conditions to enter short positions
IF CountOfShortShares < MaxPos AND ShortEntry THEN
 SELLSHORT 1 CONTRACTS AT MARKET
ENDIF

// Conditions to exit short positions
IF ShortOnMarket AND ShortExit THEN
 EXITSHORT AT MARKET
ENDIF
Comments
You must be logged in to post a comment.
Hi Sam, Thank you for the comment. I ageee completely and do not find your question trivial. Please allow me to check the code and come back with an answer. I can spontaneously say that this is not the same as codes I have implemented (yes, I do run variations on this idea live on several markets). Let me have a look and revert with an explanation. Kind regards, Fredrik
Great system, I love its simplicity. Thank you.
Thanks!
How does the backtest change with AverageTrueRange[14](close)? Better, worse, unchanged?
Hi all, Sorry revisiting an old post. This algo is simple, and simplicity is the ultimate sophistication. I am wondering if anyone has any adaptation of this strategy? I tried putting a bid on retracement instead of buying straight away at the next candle's opening. But because this strategy is momentum, pull back is shallow and missing key opportunities. If anyone has more thoughts on this, will appreciate if you can share. Tks.