


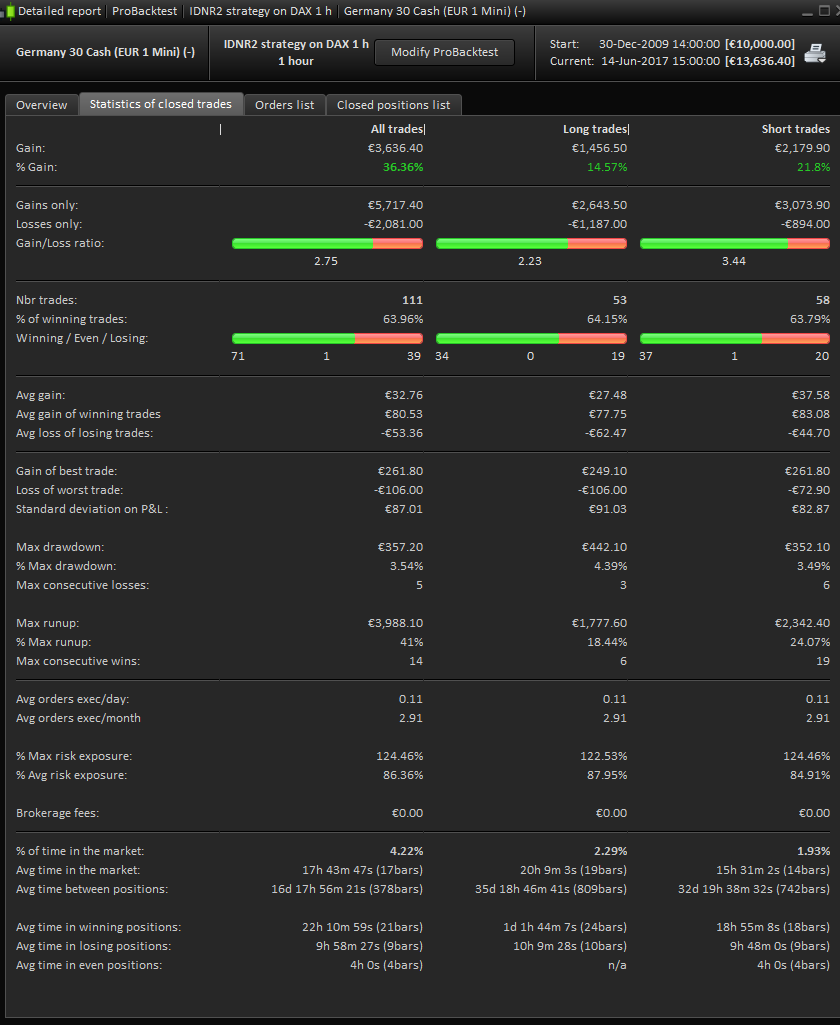
IDNR2 pattern strategy on DAX 1 h
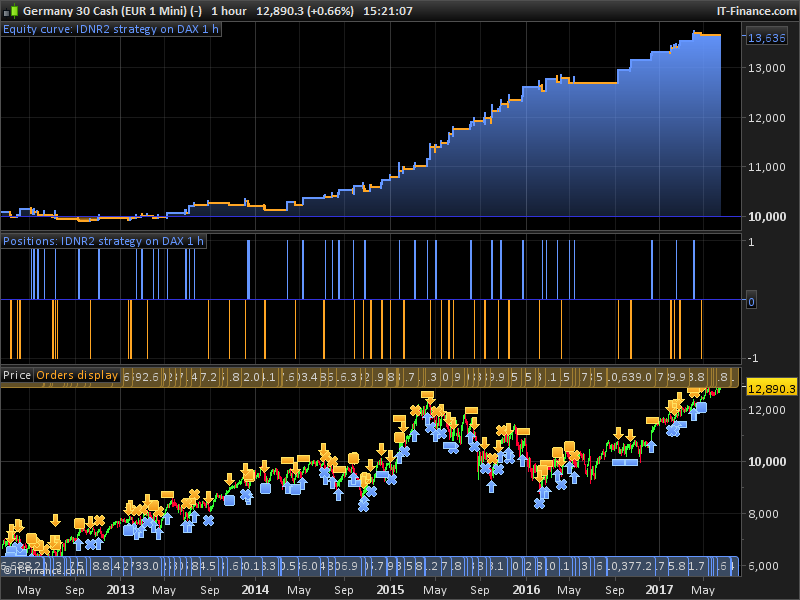
I just wrote this strategy
It works very well on dax 1 h
It is based on the IDNR pattern with 2 periods instead of 4
As filter It uses the following: the squeze of the bollinger band (band width < lowest[period]) , adx > min and atr[1] > atr[period]
As trailing stop I used a code that I found in this library
It does not seem over fitted because changing parameters the result remains good and also It seems to work quite well on FTSE MIB 1 h too
However It seem to me that It makes too few trades on the historic that I have available to be sure of its reliability
NR10 = high < high[1]  and low  > low[1]and range  < LOWEST[2](range)[1]
bbwdt =BollingerBandWidth[20](close) < lowest[17](BollingerBandWidth[20](close)[1])

// long entry
l1 = nr10
l1 = l1 and bbwdt
l1 = l1 and hour < 20
l1 = l1 and adx[10] > 17
l1 = l1 and AverageTrueRange[1](close) > AverageTrueRange[9](close)
IF not onmarket AND l1   THEN
 BUY 1 CONTRACTS AT high+1.5 stop
ENDIF

// short entry
s1 = nr10
s1 = s1 and bbwdt
s1 = s1 and hour < 20
s1 = s1 and adx[10] > 17
s1 = s1 and AverageTrueRange[1](close) > AverageTrueRange[9](close)
IF not onmarket AND s1   then
 SELLSHORT 1 CONTRACTS AT low -1.5 stop
ENDIF

// TRAILING STOP LOGIK
TGL =AverageTrueRange[14](close)*2.5
TGS=AverageTrueRange[14](close)*1.7

if not onmarket then
 MAXPRICE = 0
 MINPRICE = close
 PREZZOUSCITA = 0
ENDIF

if longonmarket then
 MAXPRICE = MAX(MAXPRICE,close)
 if MAXPRICE-tradeprice(1)>=TGL*pointsize then
  PREZZOUSCITA = MAXPRICE-TGL*pointsize
 ENDIF
ENDIF

if shortonmarket then
 MINPRICE = MIN(MINPRICE,close)
 if tradeprice(1)-MINPRICE>=TGS*pointsize then
  PREZZOUSCITA = MINPRICE+TGS*pointsize
 ENDIF
ENDIF

if onmarket and PREZZOUSCITA>0 then
 EXITSHORT AT PREZZOUSCITA STOP
 SELL AT PREZZOUSCITA STOP
ENDIF

//stop and target
SET STOP PLOSS AverageTrueRange[14](close)*2.7
SET TARGET PPROFIT AverageTrueRange[14](close)*7.2
Comments
You must be logged in to post a comment.
sorry, but your strategie doesn't work. When i implement the file, i have the error : backtest.limit.optimisation.occurrence.teasing
First of all, many thanks for sharing! These shares are much appreciated.
I hate to potentially spoil the party, but the concept appeared so interesting that I decided tp test it on several other major developed market equity indices (without any spreads and/or commissions). Unfortunately I can report that it appears to be almost consistently negative, to such a degree that I am tempted to test it in reversal.
I hate to potentially spoil the party, but the concept appeared so interesting that I decided tp test it on several other major developed market equity indices (without any spreads and/or commissions). Unfortunately I can report that it appears to be almost consistently negative, to such a degree that I am tempted to test it in reversal.
Made good money today :)
Grazie! it is beautiful indeed
This code doesn't work on 10.3 platform(IG), neither with copy/paste nor with itf import, any suggestion?