






FTSE Italian index MIB goes on at night
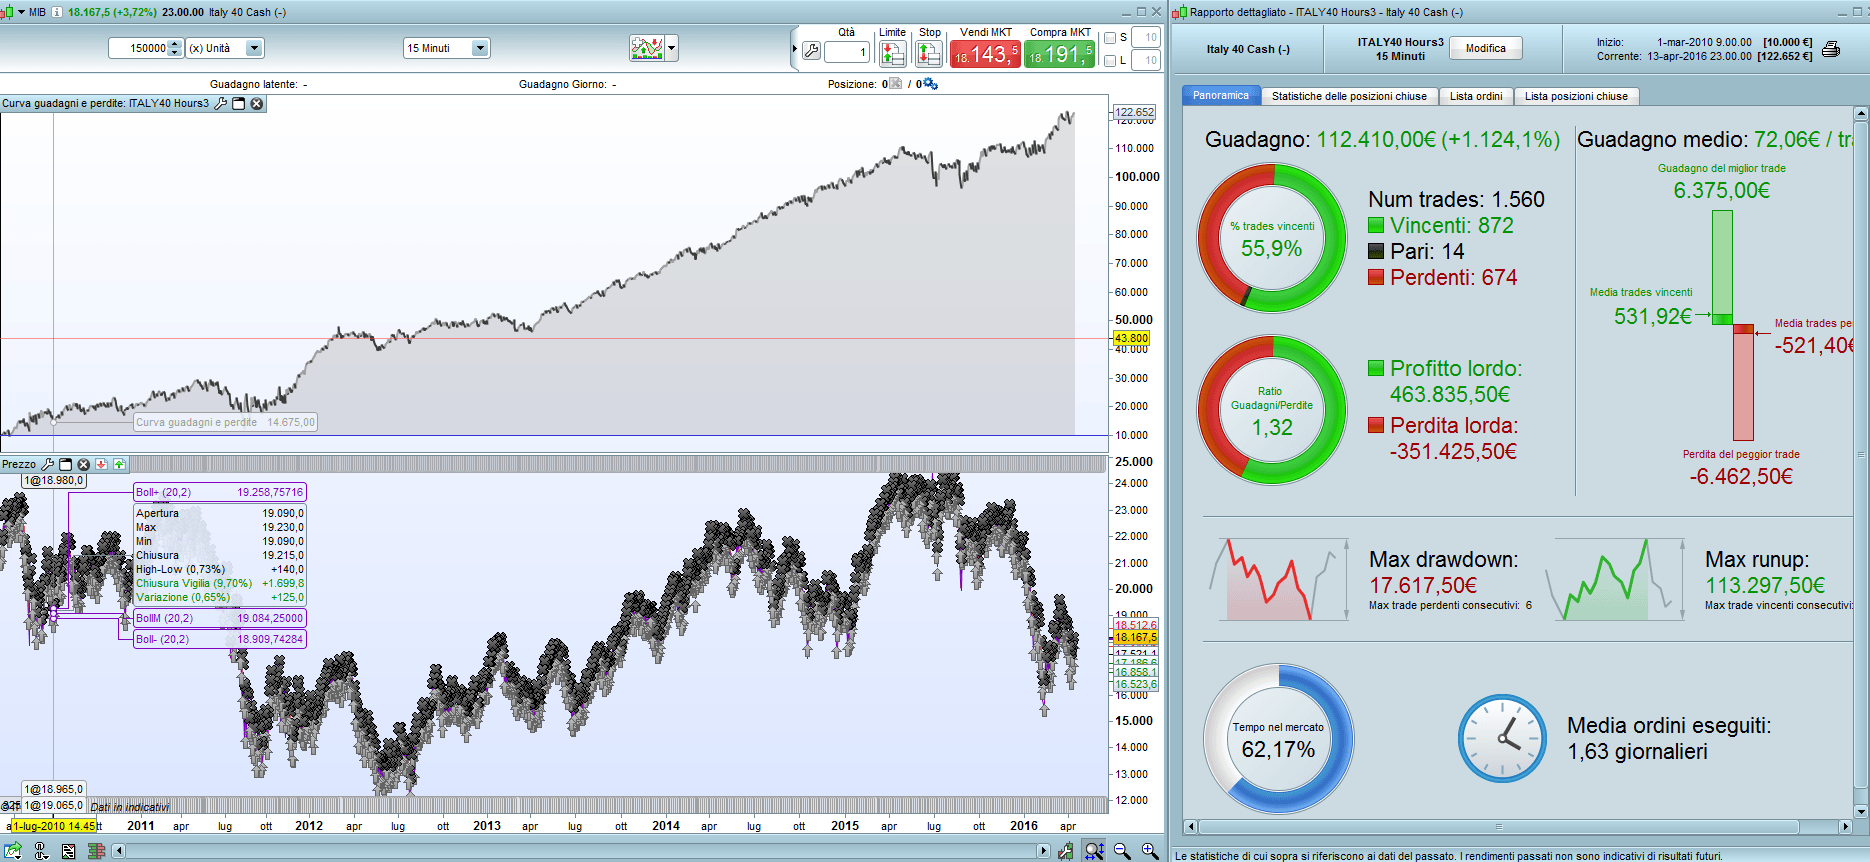
This system is really simple:
if it is 17:30 (closing market) buy at market, sell next day at 9:15 (shortly after it opened) :
// Condizioni per entrata long
IF NOT OnMarket and trading=1 and time=173000THEN
BUY 1 CONTRACTS AT MARKET
ENDIF

// Condizioni per uscire da posizioni long
If LongOnMarket AND time=091500 THEN
SELL 1 CONTRACT AT MARKET
ENDIF
It should be tested with calculated overnight fees though, for a better comparison with real time trades.
Comments
You must be logged in to post a comment.


Yes, nice improvement !
You should test it with 20 points spread (common spread on IG Markets).
What is the filter code ?
You're right, it is not good considering the spread... the cfd are too expensive, better to use mini futures
I write this is just a starting point for a system.
But look the picture, I sent to you by email, is the same motor with my personal filters, i put 15 points of spreads.
The spread is 20 points by IG markets :
http://www.ig.com/fr/conditions-indices
With this spread, the results are awful :
http://www.doctrading.fr/wp-content/uploads/2016/05/test-FTSE-MIB-avec-Spread.png
Am I wrong ?
This nice strategy seems regularly profitable before 2010 ; see picture :
http://www.doctrading.fr/wp-content/uploads/2016/05/test-FTSE-MIB-night.png
Strange that it isn't before.


I tried the system but does not work, it does not open positions, in any market
so I tried to change it so, for testint it only on the US market
// Condizioni per entrata long
IF NOT OnMarket and time>210000 THEN
BUY 1 CONTRACTS AT MARKET
ENDIF

// Condizioni per uscire da posizioni long
If LongOnMarket AND time>091500 THEN
SELL 1 CONTRACT AT MARKET
ENDIF

set target pprofit 40
the result is that the system open positions only on Sunday to close on Monday .... I use IG account, and i do not understand what the problem is


con quale timeframe hai provato sul dax ?