






Dax Bollinger break with volume. 1 Hour

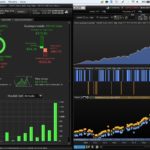
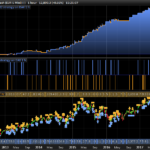
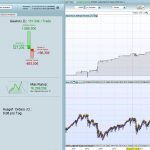
I have added my basic Dax Bollinger strat. It works that if the dax breaks out the Bollinger up or down with Volume above 8000. Its for a 1 hour time frame, working with a 2/1 RR
Happy for your comments and maybe ways optimize especially if the trade is in profit.
I know only basic code so please keep it simple for me.
Thanks.
// Definition of code parameters
DEFPARAM CumulateOrders = False // Cumulating positions deactivated
// The system will cancel all pending orders and close all positions at 0:00. No new ones will be allowed until after the "FLATBEFORE" time.
DEFPARAM FLATBEFORE = 070000
// Cancel all pending orders and close all positions at the "FLATAFTER" time
DEFPARAM FLATAFTER = 181500

// Prevents the system from placing new orders on specified days of the week
daysForbiddenEntry = OpenDayOfWeek = 6 OR OpenDayOfWeek = 0

// Conditions to enter long positions
indicator1 = BollingerUp[20](close)
c1 = (close > indicator1)
indicator2 = Volume
c2 = (indicator2 >= 8000)

IF (c1 AND c2) AND not daysForbiddenEntry THEN
 BUY 10 PERPOINT AT MARKET
ENDIF

// Conditions to enter short positions
indicator3 = BollingerDown[20](close)
c3 = (close < indicator3)
indicator4 = Volume
c4 = (indicator4 >= 8000)

IF (c3 AND c4) AND not daysForbiddenEntry THEN
 SELLSHORT 10 PERPOINT AT MARKET
ENDIF

// Stops and targets
SET STOP pLOSS 30
SET TARGET pPROFIT 60
Comments
You must be logged in to post a comment.



Thanks for sharing your automated trading strategy idea. Even if you accumulate loosing orders, it seems working just "fine". Closing all orders each day is also more secure and I think it is the best way to prevent account wipe out! 8)
Trading the breakout of Bollinger Bands is not new, but add Volumes information into your order conditions is clever. Your strategy is an interesting declination and I believe it could be improved in many ways, thank you.
Ok. Potential here to build onto this. Have opened a forum thread for further discussion:
https://www.prorealcode.com/topic/strat-bol-break-with-vol-filtr-dax-h1-seemore/
See hread for further code and variable optimization
Cheers,
M