






3 moving average trading strategy EURUSD
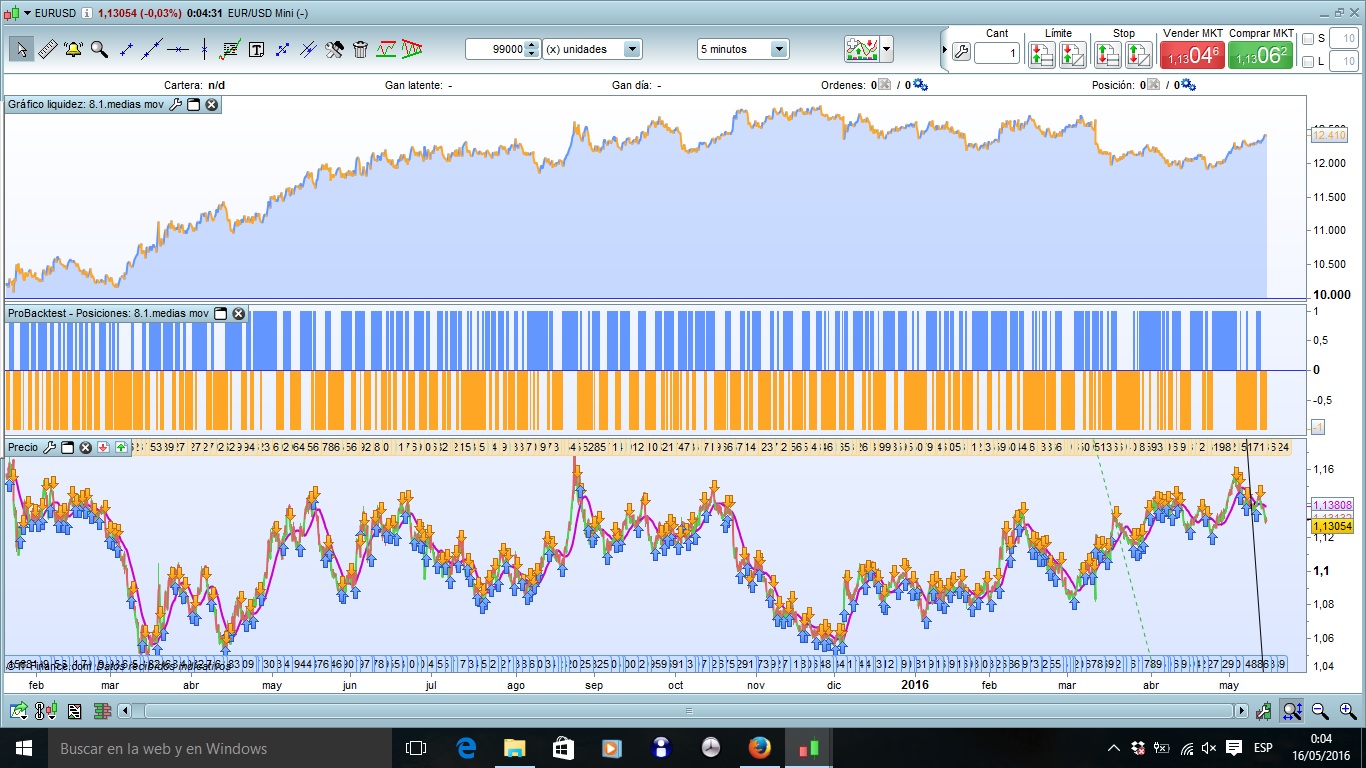
EN/ A small strategy that seems to be working. It is based on three moving average. in 5 minutes it is ok. I encourage you modify and test in other timeframes and pairs. It is made for Eur-Usd. Thank you.
ES/ Una pequeña estrategia que parece que puede funcionar. Se basa en tres medias mobiles. en 5 minutos va ok. Animo a que modifiqueis y proveis en otros tiempos y pares. A Eur-Usd. gracias.
// Condiciones para entrada de posiciones largas
DEFPARAM CumulateOrders = false
mm3= average[297]
mm2= average[99]
mm1= average[50]

if mm1<mm2 and mm2<mm3 then
 sellshort 1 contract at market
endif

if mm1>mm2 and mm2>mm3 then
 buy 1 contract at market
endif
Comments
You must be logged in to post a comment.
I made a simple risk management twice varying breakdown i max up or down in this program the number of lots according to the strategyprofit entered. Bring us and try it, thanks.
// Condiciones para entrada de posiciones largas
DEFPARAM CumulateOrders = false
once n=2
q= strategyprofit[0]
mm3= average[297]
mm2= average[99]
mm1= average[50]
n=(q/1000)+5
if mm1<mm2 and mm2<mm3 then
sellshort n contract at market
endif

if mm1>mm2 and mm2>mm3 then
buy n contract at market
endif// Condiciones para entrada de posiciones largas
DEFPARAM CumulateOrders = false
once n=2
q= strategyprofit[0]
mm3= average[297]
mm2= average[99]
mm1= average[50]
n=(q/1000)+5
if mm1<mm2 and mm2<mm3 then
sellshort n contract at market
endif
if mm1>mm2 and mm2>mm3 then
buy n contract at market
endif
Doctor how do you make to made a good riskmananagement?
Sorry for my english. I never cumulating orders. Always I made programs with defparam = False
tonight will schedule more fun moneymanagement, programming strategy through profit the number of lots. seguros.Lo good results more important is the security of your account, that being able to spend what people do not like that happens, we lose never will be 0
Hello MikeGC
when you put "defparameters = true" in each candle you put an order, it is important when you put so many orders know if you put the corresponding spread the pair in which these testing strategy. I'm glad you like my little work. the spread in Gbp / Jpy is 2.5 pips. and Eur / Usd 1.5 which is the typical spread, not the minimum spread. If ahun with the strategy that works I would give as valid. It is important to play with the money management not as a monkey with a revolver. if not everyone knows how you can finish the game.
Hi Pablo,
I have optimised this beautifully simple strategy for the GBPJPY and changed the CumulateOrders to "true". This has produced a rather spectacular result over the course of 12 months on the - too good to be true?
With the same optimised settings, it produces 68% gain on the EURUSD over 12 months.
Many thanks.
Best regards,
Mike
// Condiciones para entrada de posiciones largas
DEFPARAM CumulateOrders = true
mm3= average[100]
mm2= average[80]
mm1= average[90]

if mm1<mm2 and mm2<mm3 then
sellshort 1 contract at market
endif

if mm1>mm2 and mm2>mm3 then
buy 1 contract at market
Hello every one hope everyone ok)) I was just traying to maximize the strategy by closing with the stochastic. Any idea how the code my sound))