






2 days buy and hold SP500
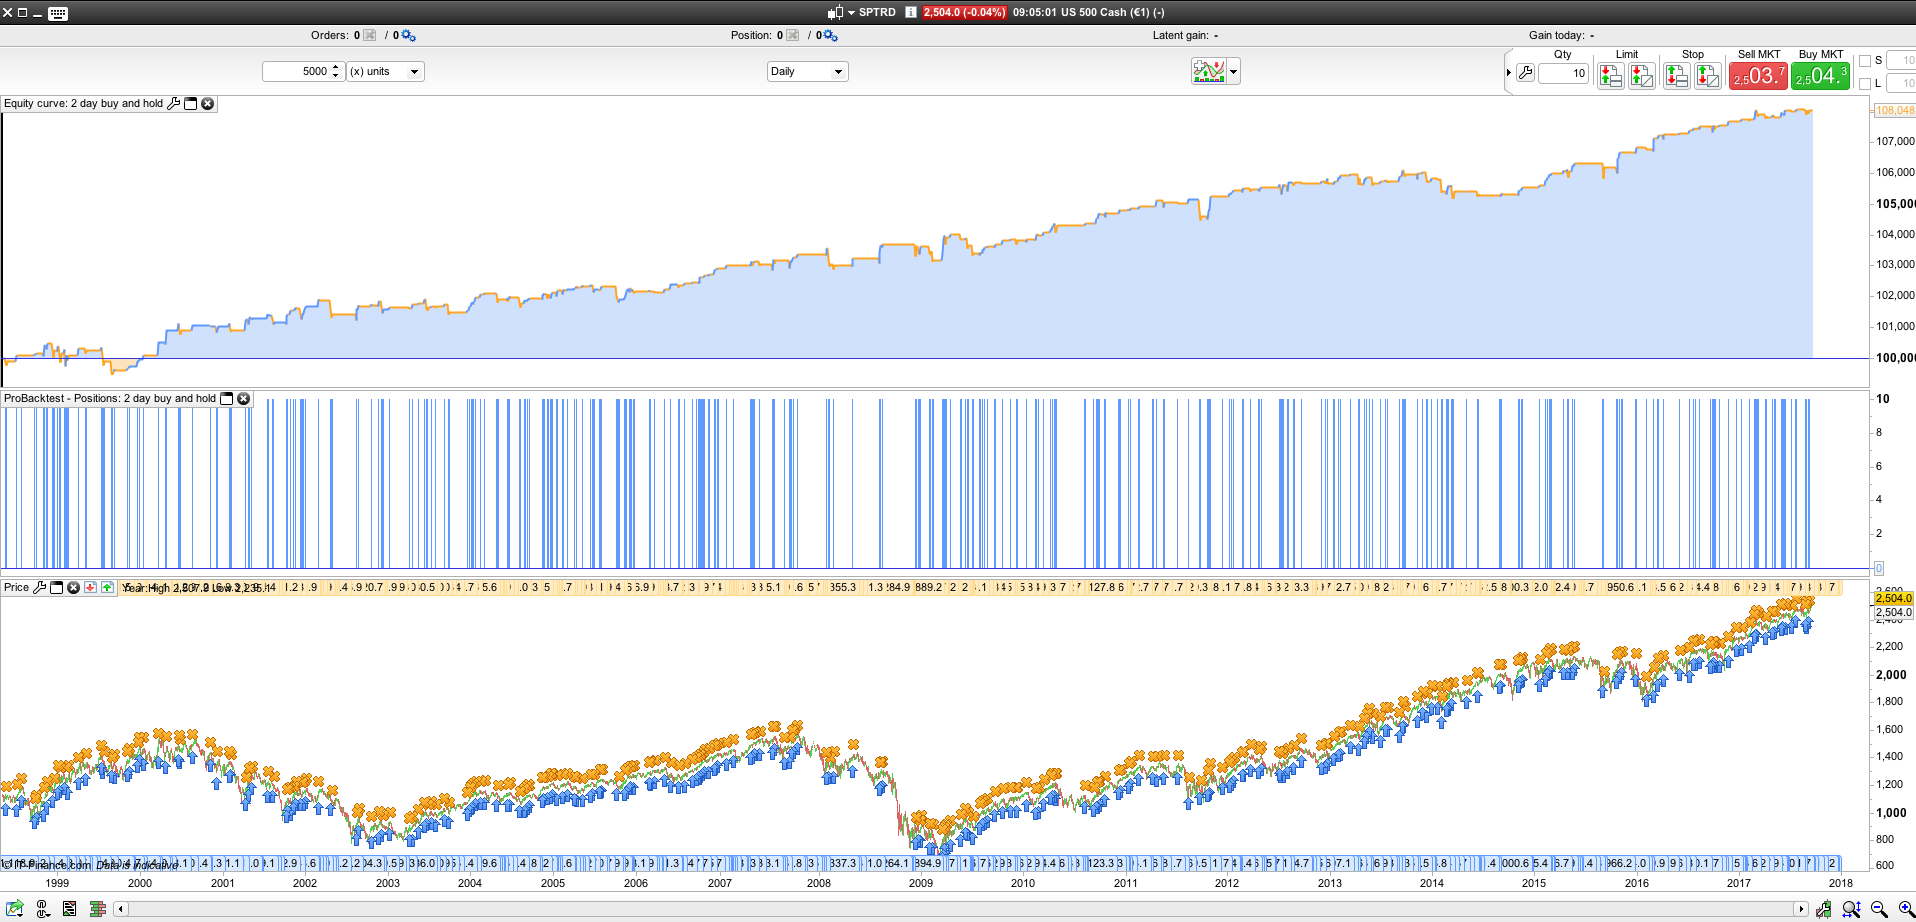
I found the baseline of this long only code online and did a few small changes to it.
It works as follow:
Entry rules:
- 2 periods moving average 1 day ago is greater than moving average of today.
- 2 periods moving average 10 days ago is greater than 11 days ago.
- Close above 7 periods moving average
Exit rule:
When the first entry rule is no longer true; exit.
DEFPARAM CumulateOrders = False
DEFPARAM PreloadBars    = 200

//Position size
positionsize = 10

//Indicators
ma1 = average [2](close)
ma2 = average [7](close)

// Entry condition
// b1 = moving average at close of one day ago is greater than the moving average of today
// b2 = moving average at close 10 days ago is greater than the moving average of the close 11 days ago

b1 = ma1[1]>ma1[0]
b1 = b1 and ma1[10]>ma1[11]
b1 = b1 and close > ma2

// Entry
if b1 then
 buy positionsize contracts at market
endif

// Exit
e1 = ma1[1]<=ma1[0]

if e1 then
 sell at market
endif

// Stoploss
set stop ploss 100
Comments
You must be logged in to post a comment.


Since 2018 this strategy leads to bankruptcy)))))))

The problem is that the markup is assuming you're writing. markup :)
Try the code tags, might do the trick, e.g.
b3 = ma1[1]<ma1[0]
Well that didn't work. Next attempt: b3 = ma1[1]<ma1[0] https://www.freeformatter.com/html-escape.html#ad-output (Try this site)


@Nicolas do you think you can solve the issue with copy paste code into this comment field? Thanks
Hi! replace the code at the line 43 by the code below. Thank's b3 = ma1[1]<ma1[0] b3 = b3 and ma1[10]<ma1[11] b3 = b3 and close < ma2 // Entry if b1 then buy positionsize contracts at market endif if b3 then sellshort positionsize contracts at market endif // Exit e1 = ma1[1]ma1[0]
Hi! it's still incorrect. There's something wrong when you copy codes to this comment section. I've had this problem here too. If you don't mind could you pls put the code in a new forum topic?
thanks victor! below the original code modified with no errors. //------------------------------------------------------------------------- // Code principal : buy sell and hold DAX 4h //------------------------------------------------------------------------- DEFPARAM CumulateOrders = False DEFPARAM PreloadBars = 200 // Money Management Equity = 500+(StrategyProfit*3) Risk = 0.1 n = Max(1,Equity*Risk/51/PipValue) // ------------ Losses = positionperf(38)>0 Wins = positionperf(38)ma1[0] b1 = b1 and ma1[10]>ma1[11] b1 = b1 and close > ma2 b3 = ma1[1]<ma1[0] b3 = b3 and ma1[10]<ma1[11] b3 = b3 and close < ma2 // Entry if b1 then buy positionsize contracts at market endif if b3 then sellshort positionsize contracts at market endif // Exit e1 = ma1[1]ma1[0] if e1 and longonmarket then sell at market endif if e3 and shortonmarket then exitshort at market endif // Stoploss and Profit set stop %loss sl set target %profit tp
Hi victor, below "Buy Sell and Hold" code optimized with money management on DAX 4h. Thank's DEFPARAM CumulateOrders = False DEFPARAM PreloadBars = 200 // Money Management Equity = 500+(StrategyProfit*3) Risk = 0.1 n = Max(1,Equity*Risk/51/PipValue) // ------------ Losses = positionperf(38)>0 Wins = positionperf(38)ma1[0] b1 = b1 and ma1[10]>ma1[11] b1 = b1 and close > ma2 b3 = ma1[1]<ma1[0] b3 = b3 and ma1[10]<ma1[11] b3 = b3 and close < ma2 // Entry if b1 then buy positionsize contracts at market endif if b3 then sellshort positionsize contracts at market endif // Exit e1 = ma1[1]ma1[0] if e1 and longonmarket then sell at market endif if e3 and shortonmarket then exitshort at market endif // Stoploss and Profit set stop %loss sl set target %profit tp
thanks! works alright but I think something when wrong in the last part of the code you attached (from "b3" and down)? There is no command for entry.
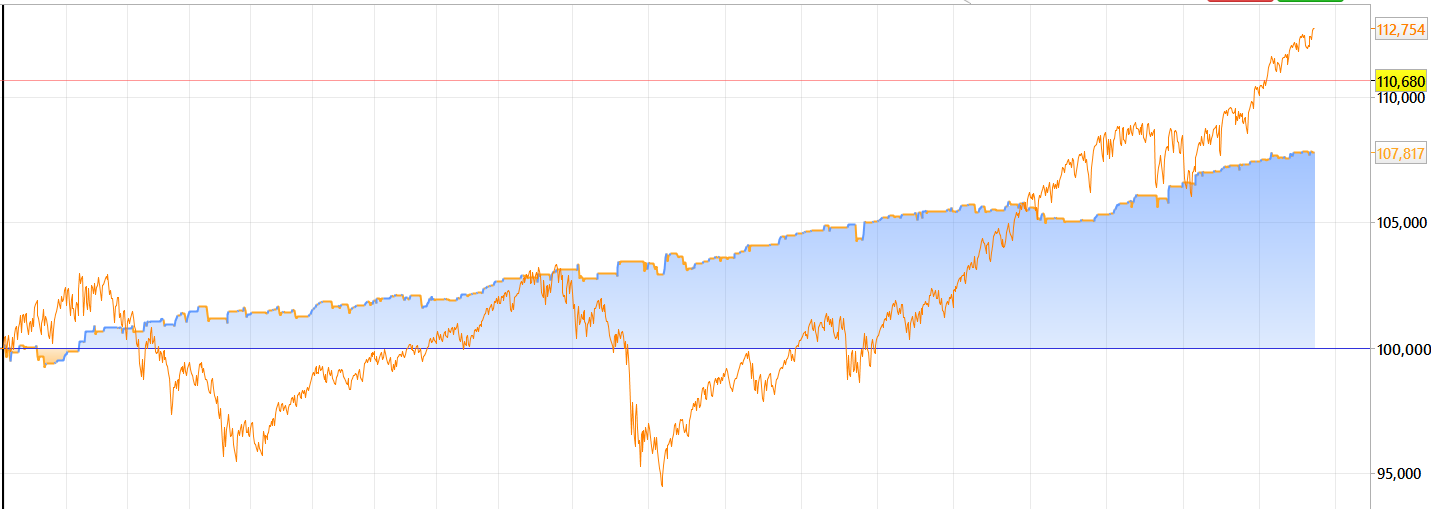
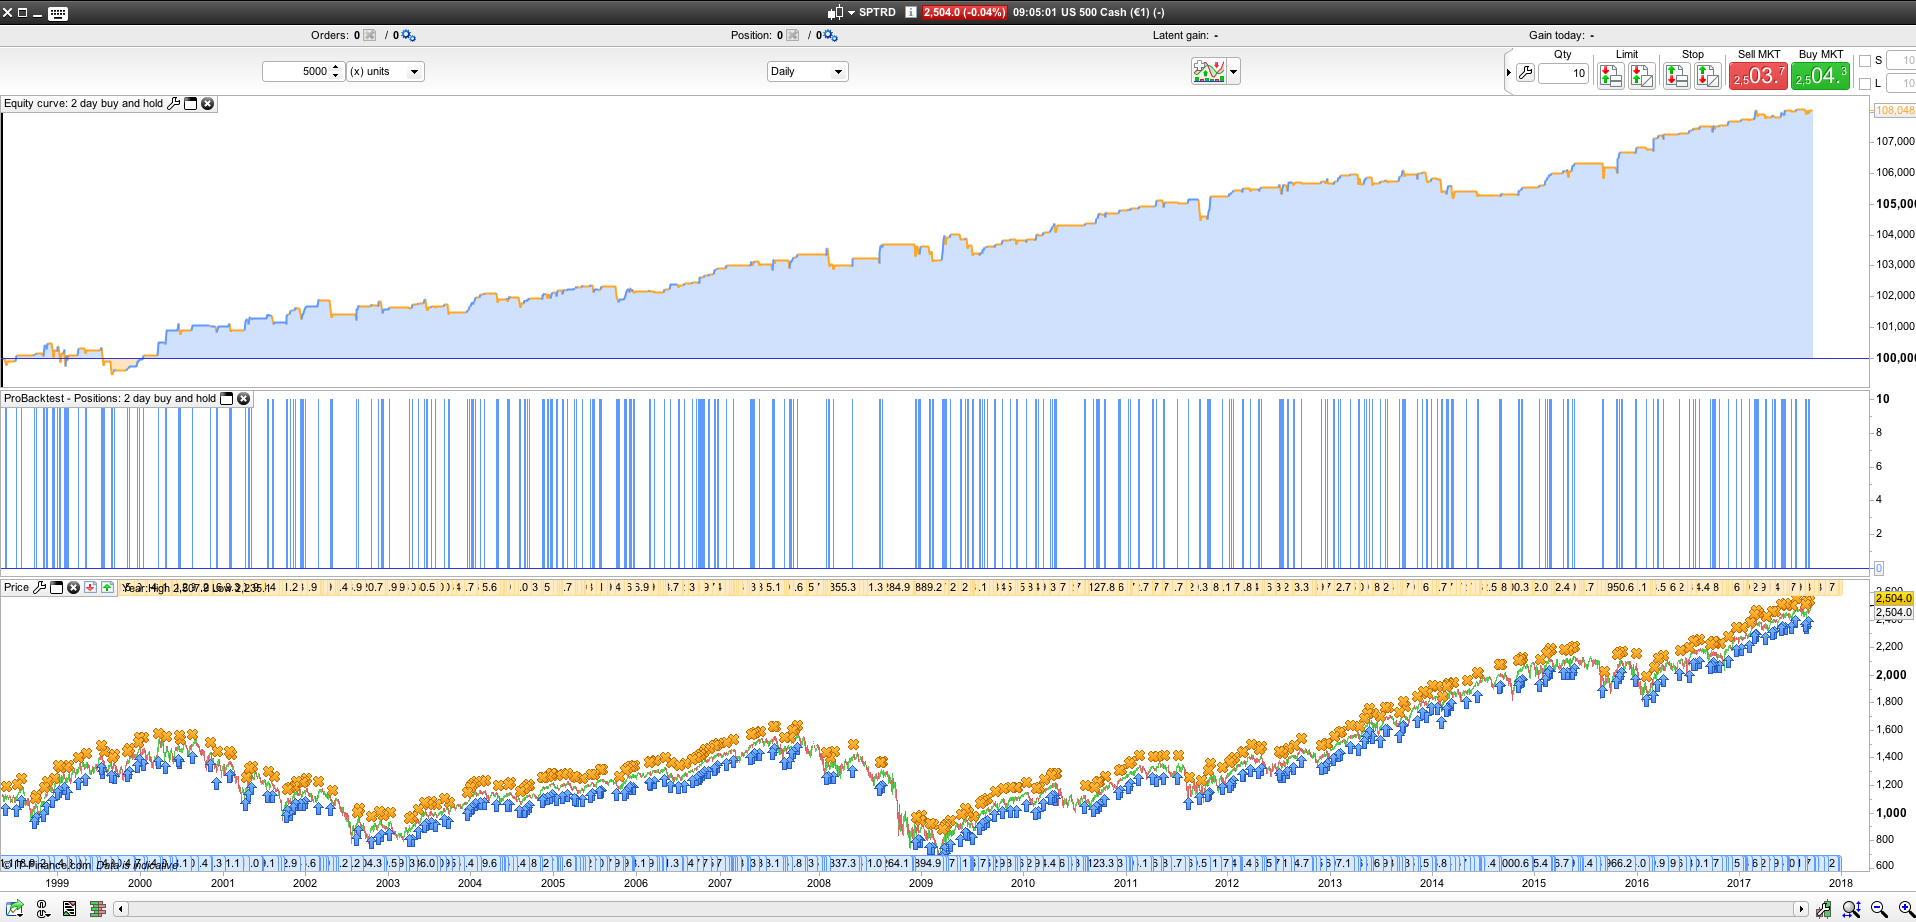
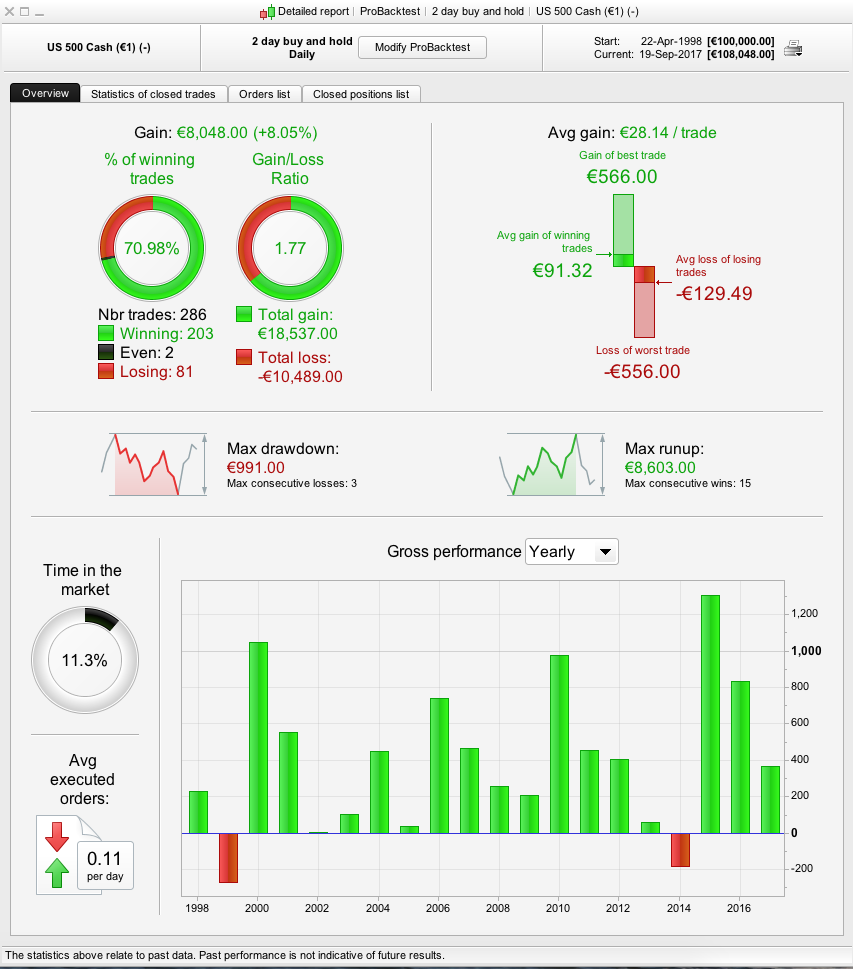
Thanks for the comparsion. This code would need some additional money management to take advantage of the steady equity curve in order to make sense. The selection of number of days to use for entry signal can also be optimised for a better return.
As an exersize in writing code its fine but as a tool to make money not so much . If you happy with less than treasury bond returns this is for you .