




More from ProRealCode
ProRealCode - Trading & Coding with ProRealTime™
The ProRealTime™ community on the web! Officially sharing ProRealTime knowledge to Worldwide users since 2015!


Deep oversold trending stock screener
January 15, 2018, 9:41 AM
Screeners
2 Comments
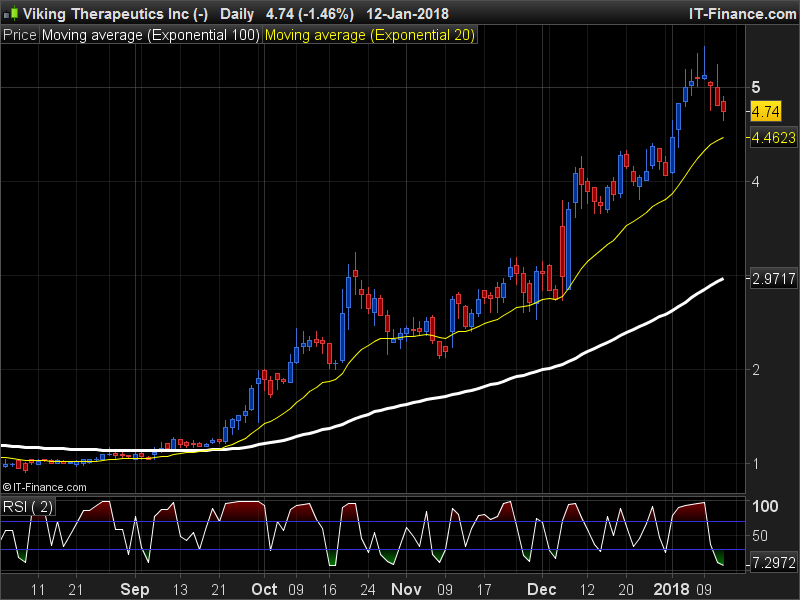
Based on a mean reversion hypothesis with the classic RSI 2 periods, this stock screener will fetch and find stocks that are in a long term trend and with sufficient Volumes.
The RSI 2 periods with oversold criteria (RSI is below 10) should give a good opportunity to set long order.
//PRC_DeepOversold TrendingStock | screener
//15.01.18
//Nicolas @ www.prorealcode.com
//Sharing ProRealTime knowledge
//translated from AFL code

ProfitSer = ROC[1](Close)
ProfitSMA = average[100](ProfitSer)
sqn = sqrt(100) * ProfitSMA / StD[100](ProfitSer)

Filter = RSI[2] < 10 AND sqn >= 2.5 AND Average[52](Close*Volume) > 3000000

screener [Filter]
Download
Filename:
PRC_DeepOversold-TrendingStock.itf
Downloads:
605
Legend
I created ProRealCode because I believe in the power of shared knowledge. I spend my time coding new tools and helping members solve complex problems.
If you are stuck on a code or need a fresh perspective on a strategy, I am always willing to help. Welcome to the community!
Author’s Profile
Similar code
Dr. Elders “Fallen Angel Screener”Screeners
FEARZONE SCREENERScreeners
Fearzone indicatorIndicators
Delorean STO SC-SV v.2.0Indicators
Loading...
Hello Nicolas, Nice screener, I appreciate the way you always try to condense at maximum the code you propose. Why do not use the Stochastic in this case? (in another way, for which reasons did you choose the RSI)? Thanks