How to calculate Relative Performance on Backtest?

Viewing 1 post (of 1 total)
  • Author
    Posts
  • #90098 quote
    DavidDavid
    Participant
    Average

    Hi

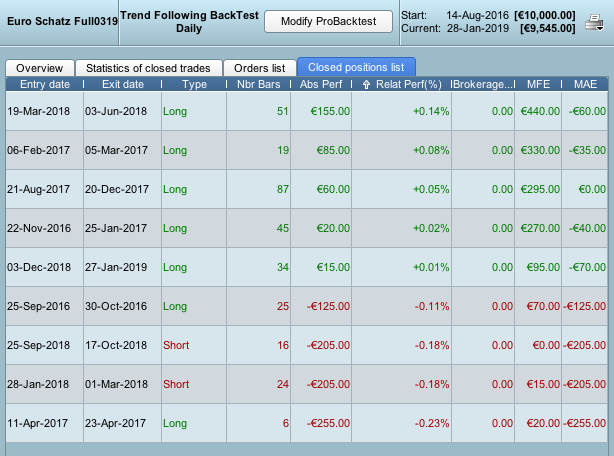
    Could anyone tell me how Relative Performance % is calculated in backtests?

    Is this the performance of the trade based on the initial capital after each trade? Or is it the cumulative profit plus capital after each trade?

    My aim is to backtest several markets and, because I can only do one at a time, I need to stitch the results together to get the trades in date. Therefore, I need a way of calculating the gain or loss on each trade to see how the strategy does over time. If the relative performance is cumulative profit plus capital that should be fine. But if it is based on initial capital then it will skew what I am trying to do with the multiple backtests. Unless you have any other suggestions to stitch several backtests together?

    Thanks

    Screen-Shot-2019-01-29-at-17.26.43.png Screen-Shot-2019-01-29-at-17.26.43.png
Viewing 1 post (of 1 total)
  • You must be logged in to reply to this topic.
ProRealAI ProRealAI New

Stuck on this ProBuilder code?

Describe what this topic is trying to build, in plain English, and ProRealAI writes the ProRealTime™ indicator, screener or system for you.

Available in 7 languages
Try ProRealAI

How to calculate Relative Performance on Backtest?


Platform Support: Charts, Data & Broker Setup

New Reply
Author
author-avatar
David @david Participant
Summary

This topic contains 1 voice and has 0 replies.

Topic Details
Forum: Platform Support: Charts, Data & Broker Setup
Language: English
Started: 01/30/2019
Status: Active
Attachments: 1 files
ProRealCode ProRealCode
Loading...