Help with errors in strategy

Viewing 3 posts - 1 through 3 (of 3 total)
  • Author
    Posts
  • #244206 quote
    JoshPhoenixJoshPhoenix
    Participant
    New

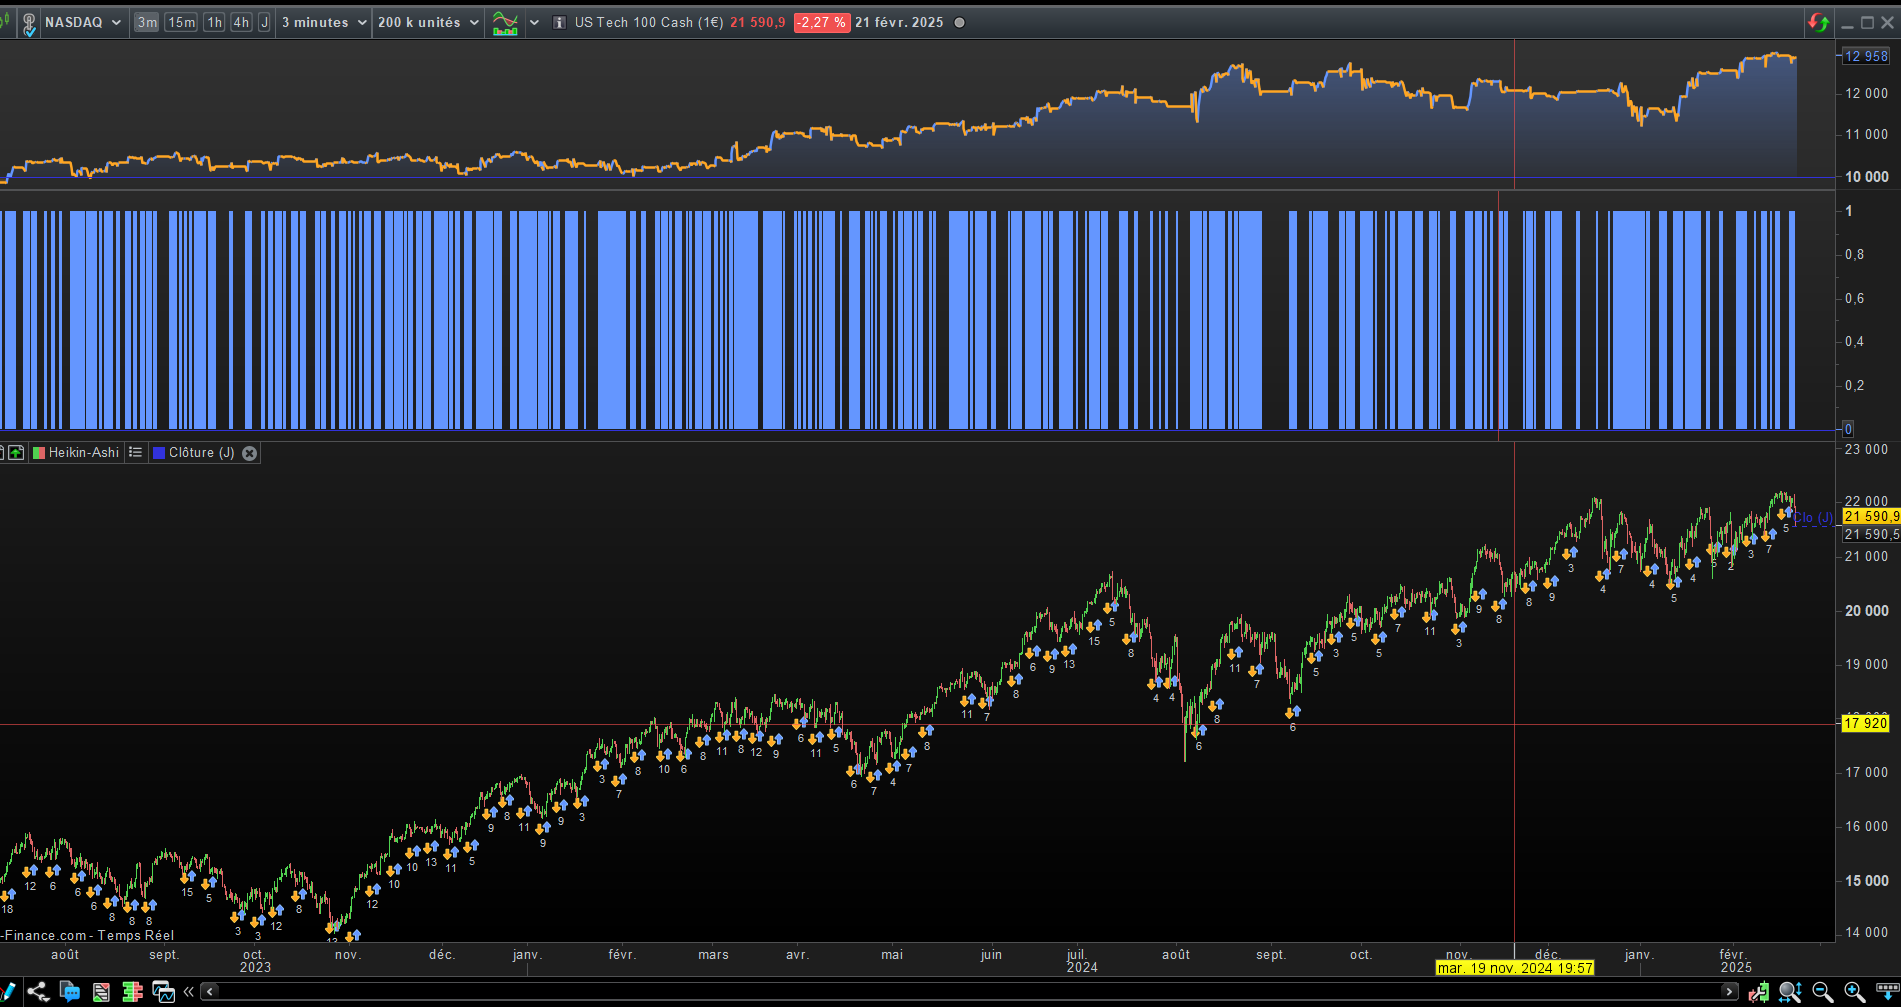
    Someone on X/Twitter has shared a good strategy, I am trying to implement it but there are errors generated.

    I’ve asked AI to convert it to code/txt from the image they shared. The strategy looks quite good, they’ve documented it in the post.

    https://x.com/AlgomaticTrade/status/1893249375758893545

    can anyone help / figure out why it’s not working?


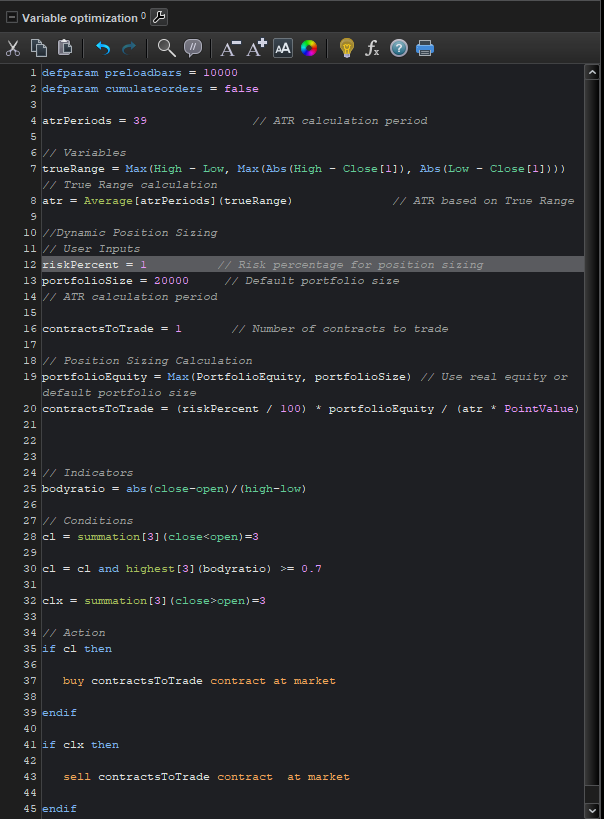
    Here’s the converted code:


    defparam preLoadBars = 10000
    defparam cumulateOrders = false
    atrPeriods = 39  // ATR calculation period
    
    // Variables
    trueRange = Max(High - Low, Max(Abs(High - Close[1]), Abs(Low - Close[1])))
    atr = Average[atrPeriods](trueRange)  // ATR based on True Range
    
    // Dynamic Position Sizing
    // User Inputs
    riskPercent = 1  // Risk percentage for position sizing
    portfolioSize = 20000  // Default portfolio size
    // ATR calculation period
    
    contractsToTrade = 1  // Number of contracts to trade
    
    // Position Sizing Calculation
    positionEquity = Max(PortfolioEquity, portfolioSize)  // Use real equity or default portfolio size
    contractsToTrade = (riskPercent / 100 * positionEquity) / (atr * PointValue)
    
    // Indicators
    bodyRatio = abs(close-open) / (high-low)
    
    // Conditions
    cl = summation[3](close-open)=3
    cl = cl and highest[3](bodyRatio) >= 0.7
    clk = summation[3](close-open)=-3
    
    // Action
    if cl then
        buy contractsToTrade contract at market
    endif
    
    if clk then
        sell contractsToTrade contract at market
    endif
    strat.png strat.png
    #244211 quote
    fifi743fifi743
    Participant
    Master
    #244239 quote
    JSJS
    Participant
    Master

    • I have adjusted the conditions, can you see if you mean this…

    • // Checks if the closing price has been higher than the opening price for the last 3 candles
    • C1 = SUMMATION[3](close > open) = 3

    • // Checks if the highest BodyRatio in the last 3 candles is at least 0.7
    • C2 = HIGHEST[3](ABS(close – open) / (high – low)) >= 0.7

    • // Long signal when both conditions are met
    • LongSignal = C1 AND C2

    • // Sell signal when the closing price has been lower than the opening price for the last 3 candles
    • SellSignal = SUMMATION[3](close < open) = 3

    • // Execution of buy and sell orders
    • IF LongSignal THEN
    • BUY contractsToTrade CONTRACT AT MARKET
    • ENDIF

    • IF SellSignal THEN
    • SELL contractsToTrade CONTRACT AT MARKET
    • ENDIF

    JoshPhoenix thanked this post
Viewing 3 posts - 1 through 3 (of 3 total)
  • You must be logged in to reply to this topic.
ProRealAI ProRealAI New

Stuck on this ProBuilder code?

Describe what this topic is trying to build, in plain English, and ProRealAI writes the ProRealTime™ indicator, screener or system for you.

Available in 7 languages
Try ProRealAI

Help with errors in strategy


ProOrder: Automated Strategies & Backtesting

New Reply
Author
Summary

This topic contains 2 replies,
has 3 voices, and was last updated by JSJS
1 year, 6 months ago.

Topic Details
Forum: ProOrder: Automated Strategies & Backtesting
Language: English
Started: 02/23/2025
Status: Active
Attachments: 3 files
ProRealCode ProRealCode
Loading...